


 |
市場調查報告書
商品編碼
2119871
越南資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Vietnam Data Center Networking - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,越南資料中心網路市場在 2025 年的價值為 4.5659 億美元,預計到 2031 年將達到 6.7663 億美元,而 2026 年為 4.8744 億美元,預測期(2026-2031 年)的複合年成長率為 6.7%。
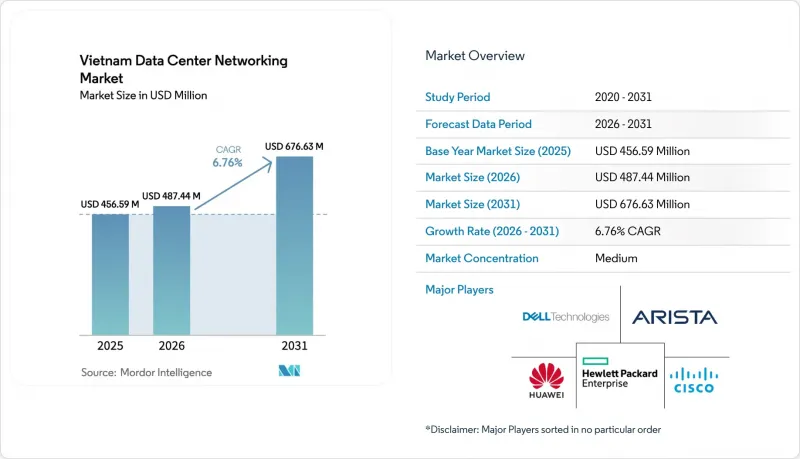
本報告按組件(產品和服務)、最終用戶(IT和電信、銀行、金融服務和保險 (BFSI)、政府和國防、其他)、資料中心類型(託管、超大規模資料中心業者雲端服務供應商、邊緣和微型資料中心)以及頻寬(10GbE 以下、25-40GbE、其他)進行細分。市場預測以美元計價。
越南資料中心網路市場趨勢與洞察
越南超大規模和雲端運算領域的資本支出(CAPEX)正在擴大
隨著電信業者競相遵守資料本地化法規並實現其作為區域樞紐的雄心壯志,超大規模資料中心的建設如今已成為高價資訊通訊技術(ICT)支出中的重要組成部分。 Viettel斥資2.61億美元建設的140兆瓦資料中心,配備了針對人工智慧工作負載最佳化的10千瓦機架,樹立了越南資料中心的新標竿。 VNPT在河內建造的2.3萬平方公尺資料中心(2000個機架)每個機架支援2Gbps的傳輸速率,為從1GbE到25GbE和100GbE交換骨幹網路的快速過渡奠定了基礎。政府提出的2030年實現全國總容量870兆瓦的目標,支撐了對高頻寬路由、光纖傳輸和軟體定義架構的多年需求。阿里雲等外國雲端服務供應商已宣布開設本地資料中心區域以符合儲存法規,這為越南資料中心網路市場創造了新的採購需求。
智慧城市和製造項目對邊緣運算的需求激增。
三星正在營運叢集將生產9.25億部行動電話,並為數千個即時品管感測器運作,這些感測器需要本地運算節點和低延遲乙太網路架構。富士康在六家工廠部署了2500個虛擬桌面基礎架構(VDI)單元,凸顯了工廠車間向微型資料中心和軟體定義網路(SDN)控制器的轉變。平陽省和峴港市的項目正在推動公共部門對邊緣運算的需求成長,從而帶動交換機和防火牆的出貨量。隨著電信業者提高5G無線基地台的密度,塔式微型資料中心正進一步擴大越南資料中心網路市場的規模。
出口限制導致ASIC晶片前置作業時間風險
美國擴大兩用物項監管範圍後,高性能開關半導體的前置作業時間延長至40-60週,是先前標準的兩倍,導致資本支出(CAPEX)上升。越南每年仍需進口價值500億美元的電子元件,而本地資料中心建設面臨運輸延誤和價格上漲的風險。一項全球調查顯示,44%的電信業者曾因元件短缺而遭遇服務中斷,凸顯了越南資料中心網路市場面臨的營運風險。
細分市場分析
預計到2025年,產品細分市場將佔越南資料中心網路市場收入的71.95%,這反映了該國數位基礎設施發展正處於以硬體為中心的階段。其中,交換器從核心到邊緣的升級(從1GbE升級到25GbE和100GbE)將佔據大部分佔有率,而路由器升級則與5G回程傳輸網路的擴展密切相關。儲存區域網路(SAN)、應用程式交付控制器和新一代防火牆的銷售正逐步成長,這主要得益於資料本地化法規帶來的國內儲存和安全需求的增加。在越南資料中心網路市場中,產品細分市場預計將實現絕對成長,但其成長速度將低於服務細分市場。至2025年,服務領域僅佔總支出的28.05%,但預計到2031年將以6.88%的複合年成長率成長。由於技能人才短缺,專業服務在設計、遷移和生命週期支援方面至關重要。對於尋求基本契約結果為導向、降低資本支出和營運風險的中型製造商和銀行而言,託管網路服務尤其具有吸引力。隨著軟體定義網路(SDN)和意圖驅動型平台的日益普及,供應商正透過控制器授權、網路分析訂閱和自動化安全措施獲得持續收入,從而推動越南資料中心網路產業服務業務的成長。
預計到2025年,電信和IT營運商將佔總收入的35.30%,這反映了Viettel、VNPT和FPT等公司積極部署5G和雲端技術的趨勢。 Techcombank的LinuxONE協議堆疊使交易吞吐量翻了四倍,顯示金融機構也正在推動對企業級路由和交換的需求。與國家數位身分相關的政府計畫正在擴大用戶群體,而媒體、醫療保健和教育領域則新增了超高清串流媒體和遠端醫療服務等新的工作負載。受「中國+1」策略下生產基地遷移的推動,製造業和工業領域預計將以7.05%的複合年成長率成長。三星位於太原省和北寧省的工廠需要人工智慧驅動的缺陷檢測和物聯網遙測技術,這推動了微型資料中心和高頻寬交換器的應用。類似的模式也在工業園區得到應用,這無疑將使越南的資料中心網路市場超越傳統的城域網路樞紐。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 越南超大規模和雲端運算領域的資本支出(CAPEX)正在擴大
- 智慧城市和製造項目對邊緣運算的需求激增。
- 政府支持措施(「2025年國家發展策略」)
- 向軟體定義網路 (SDN) 和意圖式網路)遷移
- 因5G部署而升級資料中心路由器
- 企業ESG政策支持節能矽
- 市場限制因素
- 出口限制導致ASIC晶片前置作業時間風險
- 高階網路架構專家短缺
- 不斷上漲的電費給總擁有成本 (TCO) 帶來了壓力。
- 企業中仍存在網路安全漏洞。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 按組件
- 產品
- 乙太網路切換器
- 路由器
- 儲存區域網路(SAN)
- 應用傳遞控制器(ADC)
- 網路安全設備
- 軟體定義網路 (SDN) 控制器
- 光連接模組
- 服務
- 安裝與整合
- 培訓和諮詢
- 支援與維護
- 主機服務
- 產品
- 最終用戶
- 資訊科技/通訊
- 銀行、金融服務和保險(BFSI)
- 政府/國防
- 媒體與娛樂
- 醫療保健和生命科學
- 製造業和工業
- 其他最終用戶
- 依資料中心類型
- 搭配
- 超大規模資料中心業者雲端服務供應商
- 邊緣微資料中心
- 頻寬
- 10GbE 或更低
- 25~40GbE
- 50~100GbE
- 超過 100GbE
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cisco Systems Inc.
- Arista Networks Inc.
- Dell Technologies Inc.
- Hewlett Packard Enterprise
- Huawei Technologies Co. Ltd.
- Juniper Networks Inc.
- VMware Inc.
- Broadcom Inc.
- Intel Corporation
- NVIDIA Corporation
- NEC Corporation
- IBM Corporation
- Schneider Electric SE
- Siemens AG
- FPT Telecom International
- Viettel IDC
- VNPT Technology
- CMC Telecom
- Netnam Corporation
- Supermicro Computer Inc.
- Edgecore Networks Corp.
- Extreme Networks Inc.
- Palo Alto Networks
- Fortinet Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Vietnam data center networking market size was valued at USD 456.59 million in 2025 and estimated to grow from USD 487.44 million in 2026 to reach USD 676.63 million by 2031, at a CAGR of 6.76% during the forecast period (2026-2031).
This report is Segmented by Component (Product and Services), End User( IT and Telecommunications, Banking, Financial Services and Insurance (BFSI), Government and Defense and More), Data Center Type (Colocation, Hyperscalers/Cloud Service Providers, Edge/Micro Data Centers), by Bandwidth (<=10 GbE, 25-40 GbE and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Data Center Networking Market Trends and Insights
Growing hyperscale and cloud CAPEX in Vietnam
Hyperscale builds now dominate large-ticket ICT spending as operators race to satisfy data-localization rules and regional hub ambitions. Viettel's USD 261 million, 140 MW campus sets a new domestic benchmark, offering 10 kW racks that are optimised for AI workloads. VNPT's 23,000 m2 Hanoi facility with 2,000 racks supports 2 Gbps per rack, underscoring the rapid transition from 1 GbE to 25 GbE and 100 GbE switching backbones. Government targets calling for 870 MW of national capacity by 2030 underpin multi-year demand for high-bandwidth routing, optical-transport, and software-defined fabrics. Foreign cloud providers such as Alibaba Cloud have announced local zones to comply with storage rules, bringing new procurement volume to the Vietnam data center networking market.
Surge in edge-computing needs for smart-city and manufacturing projects
Samsung's USD 20 billion cluster-producing 925 million handsets-operates thousands of real-time quality-control sensors that require local compute nodes and low-latency Ethernet fabrics. Foxconn's deployment of 2,500 VDIs across six plants demonstrates the shift toward micro data centers and SDN controllers at factory floors. Binh Duong and Da Nang city programs add public-sector edge demand, driving incremental switch and firewall shipments. As operators densify 5G radios, tower-based micro data centers further enlarge the Vietnam data center networking market footprint.
Export-control-driven ASIC lead-time risk
Advanced switching silicon now requires 40-60 week lead times because of expanded U.S. dual-use controls, doubling historical norms and inflating capex.Vietnam still imports USD 50 billion in electronic parts annually, exposing local data-center builds to shipment slips and price spikes. Global surveys show 44% of operators suffered outages tied to parts shortages, underscoring operational risk within the Vietnam data center networking market.
Other drivers and restraints analyzed in the detailed report include:
- Government incentives (National DC Strategy 2025)
- Shift toward SDN and intent-based networking
- Shortage of advanced network-architecture talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Products generated 71.95% of Vietnam data center networking market revenue in 2025, reflecting the hardware-intensive stage of the country's digital build-out. Core-to-edge switch refreshes from 1 GbE to 25 GbE and 100 GbE contribute the bulk, while router upgrades align with 5G backhaul expansion. Storage-area networking, application delivery controllers, and next-generation firewalls add incremental volume as data-localization laws amplify in-country storage and security needs. The Vietnam data center networking market size for Products is expected to widen in absolute terms even as growth decelerates relative to Services.Services, though only 28.05% of the 2025 spend, will advance at a 6.88% CAGR through 2031. Skill shortages make professional services indispensable for design, migration, and lifecycle support. Managed network services are especially attractive to mid-sized manufacturers and banks seeking outcome-based contracts that trim capex and de-risk operations. As SDN and intent-based platforms proliferate, vendors earn recurring revenue from controller licensing, network-analytics subscriptions, and security-policy automation, reinforcing the services uptrend across the Vietnam data center networking industry.
Telecom and IT operators commanded 35.30% of 2025 revenue, mirroring Viettel, VNPT, and FPT's aggressive 5G and cloud rollouts. Techcombank's LinuxONE stack that quadrupled transaction throughput demonstrates how financial institutions also drive enterprise-grade routing and switching demand. Government projects tied to national digital identity broaden the user base, while media, healthcare, and education add new workloads such as UHD streaming and telehealth services.Manufacturing and Industrial verticals, buoyed by China-plus-one relocations, are poised for a 7.05% CAGR. Samsung's factories in Thai Nguyen and Bac Ninh require AI-enabled defect inspection and IoT telemetry, prompting micro data center and high-bandwidth switch installations. Industrial parks replicate this template, ensuring that the Vietnam data center networking market expands beyond the traditional metro hubs.
Complete Report Scope:
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- less than or equal to10 GbE
- 25-40 GbE
- 50-100 GbE
- Greater than 100 GbE
List of Companies Covered in this Report:
- Cisco Systems Inc.
- Arista Networks Inc.
- Dell Technologies Inc.
- Hewlett Packard Enterprise
- Huawei Technologies Co. Ltd.
- Juniper Networks Inc.
- VMware Inc.
- Broadcom Inc.
- Intel Corporation
- NVIDIA Corporation
- NEC Corporation
- IBM Corporation
- Schneider Electric SE
- Siemens AG
- FPT Telecom International
- Viettel IDC
- VNPT Technology
- CMC Telecom
- Netnam Corporation
- Supermicro Computer Inc.
- Edgecore Networks Corp.
- Extreme Networks Inc.
- Palo Alto Networks
- Fortinet Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing hyperscale and cloud CAPEX in Vietnam
- 4.2.2 Surge in edge-computing needs for smart-city and manufacturing projects
- 4.2.3 Government incentives (National DC Strategy 2025)
- 4.2.4 Shift toward SDN and intent-based networking
- 4.2.5 5G rollout driving DC router refresh
- 4.2.6 Corporate ESG mandates favoring energy-efficient silicon
- 4.3 Market Restraints
- 4.3.1 Export-control-driven ASIC lead-time risk
- 4.3.2 Shortage of advanced network-architecture talent
- 4.3.3 Rising electricity tariffs eroding TCO
- 4.3.4 Persistent cybersecurity gaps in enterprises
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Products
- 5.1.1.1 Ethernet Switches
- 5.1.1.2 Routers
- 5.1.1.3 Storage Area Network (SAN)
- 5.1.1.4 Application Delivery Controllers (ADC)
- 5.1.1.5 Network Security Appliances
- 5.1.1.6 Software-Defined Networking (SDN) Controllers
- 5.1.1.7 Optical Interconnects
- 5.1.2 Services
- 5.1.2.1 Installation and Integration
- 5.1.2.2 Training and Consulting
- 5.1.2.3 Support and Maintenance
- 5.1.2.4 Managed Network Services
- 5.1.1 Products
- 5.2 By End-User
- 5.2.1 IT and Telecommunications
- 5.2.2 Banking, Financial Services and Insurance (BFSI)
- 5.2.3 Government and Defense
- 5.2.4 Media and Entertainment
- 5.2.5 Healthcare and Life Sciences
- 5.2.6 Manufacturing and Industrial
- 5.2.7 Other End-Users
- 5.3 By Data-Center Type
- 5.3.1 Colocation
- 5.3.2 Hyperscalers/Cloud Service Providers
- 5.3.3 Edge/Micro Data Centers
- 5.4 By Bandwidth
- 5.4.1 less than or equal to10 GbE
- 5.4.2 25-40 GbE
- 5.4.3 50-100 GbE
- 5.4.4 Greater than 100 GbE
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems Inc.
- 6.4.2 Arista Networks Inc.
- 6.4.3 Dell Technologies Inc.
- 6.4.4 Hewlett Packard Enterprise
- 6.4.5 Huawei Technologies Co. Ltd.
- 6.4.6 Juniper Networks Inc.
- 6.4.7 VMware Inc.
- 6.4.8 Broadcom Inc.
- 6.4.9 Intel Corporation
- 6.4.10 NVIDIA Corporation
- 6.4.11 NEC Corporation
- 6.4.12 IBM Corporation
- 6.4.13 Schneider Electric SE
- 6.4.14 Siemens AG
- 6.4.15 FPT Telecom International
- 6.4.16 Viettel IDC
- 6.4.17 VNPT Technology
- 6.4.18 CMC Telecom
- 6.4.19 Netnam Corporation
- 6.4.20 Supermicro Computer Inc.
- 6.4.21 Edgecore Networks Corp.
- 6.4.22 Extreme Networks Inc.
- 6.4.23 Palo Alto Networks
- 6.4.24 Fortinet Inc.
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 全球資料中心網路市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 北美資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)南美洲資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)印度資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)義大利資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)英國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)