


 |
市場調查報告書
商品編碼
2119225
合成媒體行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Synthetic Media Marketing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
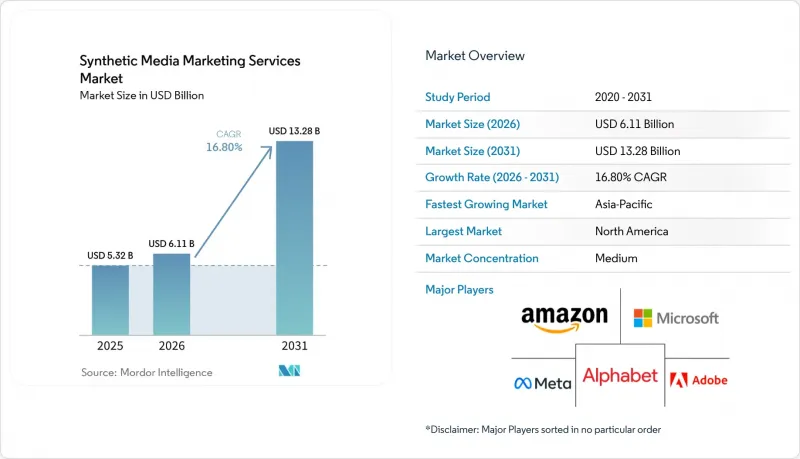
據 Mordor Intelligence 稱,2025 年合成媒體行銷服務市值為 53.2 億美元,預計到 2031 年將達到 132.8 億美元,而 2026 年為 61.1 億美元,2026 年至 2031 年預測期內的複合年成長率為 16.80%。
本報告按服務類型(例如,合成創新策略和諮詢、虛擬網紅和頭像宣傳活動服務)、部署模式(例如,整合式和API支援型服務)、客戶類型(例如,大型企業)、最終用戶產業(例如,醫療保健和生命科學)以及地區進行細分。市場預測以美元計價。
全球合成媒體行銷服務市場趨勢與洞察
對可擴展和個人化行銷內容的需求日益成長。
擁有龐大產品目錄的品牌所需的內容版本遠遠超越傳統製作方式的處理能力。零售宣傳活動可能需要針對不同的目標受眾、產品、地區、設備和零售管道製作不同的素材。這促使合成媒體行銷服務市場的工作重點從製作固定的廣告群組轉向管理持續的內容管線。 2025年,Adobe推出了商業媒體網路的GenStudio,旨在支援在個人化廣告工作流程中使用產品清單和第一方資料。該方案還整合了LiveRamp,用於受眾定向和效果衡量。Meta分析表明,虛擬網紅在消費者互動方面與真人網紅不相上下,同時還能帶來更強的新穎性效果。因此,當品牌需要在不增加相應製作預算的情況下頻繁修改內容時,合成媒體行銷服務市場將從中受益。
降低推理成本並與創新套件整合。
整個技術堆疊中,產生人工智慧媒體資產的成本都在下降。根據英偉達引用的史丹佛大學《2025年人工智慧指數》顯示,在2022年11月至2024年10月期間,達到與GPT-3.5性能相當的推理成本已降至1/280。報告也指出,硬體效率每年提升40%。 Adobe於2026年發布了適用於Photoshop、Premiere、Illustrator、InDesign和Frame.io的「Firefly AI Assistant」公開測試版。該助手還整合到使用ChatGPT、Claude、Microsoft 365 Copilot和Slack的工作流程中。這些整合減少了合成媒體行銷服務使用者在創新、批准和生成過程中在不同系統之間切換的需求。
版權、肖像權以及與訓練資料相關的法律風險
即使底層技術可用,版權、肖像權和訓練資料問題也會延緩行銷部署。廣告主需要明確了解聲音、臉孔、影像和訓練資料是否已獲得合法授權。因此,在市場上採購合成媒體行銷服務時,合約保障和供應商文件至關重要。歐盟人工智慧法對某些人工智慧產生的內容提出了透明度要求,這增加了跨境宣傳活動活動合規性的考慮。買家越來越關注模型文件、內容記錄和賠償條款。在合成媒體行銷服務市場,能夠展現清晰的授權流程並明確界定法律風險責任的供應商更受青睞。
細分市場分析
到2025年,「創新製作和後製自動化服務」將佔服務類收入的32.83%。這為合成媒體行銷服務市場的買家提供了一種切實可行的方法,可以根據已批准的宣傳活動方案增加素材的製作數量。代理商無需重新設計整個創新流程,即可自動完成調整大小、編輯、在地化和格式設定等操作。與完全取代現有代理商或內部製作團隊相比,這項服務的實施難度較低。預計到2031年,虛擬網紅和虛擬形象宣傳活動服務將以17.38%的複合年成長率成長。
這種快速成長反映了虛擬形象使用方式的轉變,即從一次性使用轉向在產品發布和區域宣傳活動中持續使用數位人格。 HeyGen公司報告稱,其年度經常性收入(ARR)在2026年6月達到2億美元,顯示市場對其虛擬形象影片服務有著巨大的需求。該公司還報告稱,其現金流在2026年實現了損益平衡。研究表明,新的虛擬形象能夠在消費者互動方面保持新鮮感優勢。合成語音和在地化服務、諮詢、即時廣告投放和受眾模擬等服務正在拓展合成媒體行銷服務市場中服務提供者的服務範圍。
至2025年,以部署模式分類,託管服務將佔銷售額的48.60%。合成媒體行銷服務市場的企業客戶通常選擇託管服務,因為他們可以將部分管治、品質保證和品牌安全營運工作委託給服務提供者。當團隊沒有內部專家來評估模型、微調和確保合規性時,這種機制就非常有用。此外,對於那些更注重宣傳活動效果而非單一軟體進入許可權權限的買家來說,託管服務也提供了清晰的合約條款。預計到2031年,私有模式和企業客製化服務的複合年成長率將達到17.63%。
這一成長率表明,大規模用戶在累積了託管專案經驗後,開始建立自身的內容開發能力。 2026年1月,Synthesia在E輪融資中籌集了2億美元,估值達40億美元。截至2025年4月,該公司年度經常性收入(ARR)已超過1億美元。自助式SaaS服務降低了小規模買家的進入門檻,而整合式API服務則將內容產生能力與宣傳活動和客戶關係管理系統連接起來。 2025年,Adobe擴展了GenStudio與Amazon Ads、Google Marketing Platform、LinkedIn和TikTok的整合功能。
區域分析
2025年,北美佔全球銷售額的48.26%,佔合成媒體行銷服務市場最大佔有率。該地區受益於合成媒體行銷服務和廣告技術的集中、企業早期採用以及資金雄厚的專業供應商的存在。美國擁有大規模的廣告主群體和充滿活力的平台開發環境。 ElevenLabs在2025年底的年度經常性收入超過3.3億美元,並在2026年2月的D輪融資中籌集了5億美元。 Synthesia在2025年4月的年度經常性收入超過1億美元,並在2026年1月進行了新一輪資金籌措。
預計到2031年,亞太地區的複合年成長率將達到17.59%,是所有地區中成長最快的。中國正將其面向企業的AI廣告工具推廣至日本和東南亞,加劇了區域內價格和產品功能的競爭。在日本,在地化的虛擬形象系統正在開發中,以滿足全球平台無法充分滿足的語言和文化需求。資生堂已在其官方電商網站上推出了基於AI虛擬形象的即時電商服務,目標客戶為年輕消費者。
在印度,Shriram Life Insurance 的多語言宣傳活動是高度監管產業成功實施的典範。在韓國,娛樂產業和全球虛擬內容受眾的需求正在湧現。南美洲尚處於起步階段,巴西和阿根廷是主要的需求中心。在中東,沙烏地阿拉伯和阿拉伯聯合大公國的數位轉型 (DX) 專案正在推動市場成長。非洲仍在發展中,但南非、奈及利亞和埃及正在透過行動優先廣告和國際品牌在地化來推動市場需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素對市場的影響
- 市場促進因素
- 對高度擴充性和個人化的行銷內容的需求日益成長。
- 降低推理成本並與創新套件整合。
- 短影片和多語言社交電商的成長
- 品牌採用虛擬網紅與人工智慧化身
- 零售媒體網路需要合成創新變體進行閉合迴路測試。
- 基於用戶同意的數位人才市場為使用授權聲音和肖像的宣傳活動開闢了可能性。
- 市場限制因素
- 涉及版權、肖像權和培訓資料方面的法律責任風險。
- 深度造假導致信任度下降和品牌安全風險
- 廣告平台間源資訊浮水印的碎片化
- 藝人協會和創作者合約對合成複製的限制
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 綜合策略與諮詢
- 利用虛擬網紅和虛擬形象的宣傳活動服務
- 合成語音和在地化服務
- 自動化創新製作與後製服務
- 其他服務類型
- 按部署模式
- 託管服務
- 自助式SaaS相容服務
- 整合和 API 實作支援服務
- 企業專屬模式與客製化服務
- 依客戶類型
- 大公司
- 小型企業
- 按最終用途行業分類
- 零售與電子商務
- 媒體與娛樂
- 資訊科技/通訊
- BFSI
- 醫療保健和生命科學
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Adobe Inc.
- Alphabet Inc.
- Microsoft Corporation
- Meta Platforms, Inc.
- Amazon.com, Inc.
- Canva Pty Ltd.
- OpenAI, LLC
- Synthesia Limited
- HeyGen Technology Inc.
- Runway AI, Inc.
- D-ID Ltd.
- ElevenLabs Inc.
- Stability AI Ltd.
- Descript, Inc.
- Lightricks Ltd.
- Midjourney, Inc.
- Sprinklr, Inc.
- Salesforce, Inc.
- Persado Inc.
- DeepBrain AI Inc.
- Soul Machines Limited
- UneeQ Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the synthetic media marketing services market size was valued at USD 5.32 billion in 2025 and is estimated to grow from USD 6.11 billion in 2026 to reach USD 13.28 billion by 2031, at a CAGR of 16.80% during the forecast period 2026-2031.
This report is Segmented by Service Type (Synthetic Creative Strategy and Consulting, Virtual Influencer and Avatar Campaign Services, and More), Deployment Model (Integration and API Enablement Services, and More), Customer Type (Large Enterprises, and More), End-Use Industry (Healthcare and Life Sciences, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Synthetic Media Marketing Services Market Trends and Insights
Rising Demand for Scalable, Personalized Marketing Content
Brands with large product catalogs need more content versions than traditional production methods can deliver. A retail campaign may require different assets by audience, product, geography, device, and retail format. This changes work in the synthetic media marketing services market from producing a fixed set of advertisements to managing a continuing content pipeline. Adobe introduced GenStudio for Commerce Media Networks in 2025 to enable product listings and first-party data to be used in personalized advertising workflows, with LiveRamp integration for audience targeting and measurement. A meta-analysis of 210 experimental studies and 91,058 consumers found that virtual influencers can match human influencers in consumer engagement while delivering a stronger novelty effect. The synthetic media marketing services market, therefore, benefits where brands need frequent revisions without adding comparable production budgets.
Falling Inference Costs and Creative-Suite Integration
The cost of generating AI media assets has fallen across the technology stack. Stanford University's 2025 AI Index, as cited by NVIDIA, reported a 280-fold reduction in inference costs for GPT-3.5-equivalent performance from November 2022 to October 2024. The same source reported that hardware efficiency improved by 40% annually. Adobe released Firefly AI Assistant in public beta across Photoshop, Premiere, Illustrator, InDesign, and Frame.io in 2026. The assistant also entered workflows that use ChatGPT, Claude, Microsoft 365 Copilot, and Slack. These integrations reduce the need for users of synthetic media marketing services to move between separate creative, approval, and generation systems.
Copyright, Likeness, and Training-Data Liability Exposure
Copyright, likeness, and training-data questions can delay marketing deployment even when the underlying technology is available. Advertisers need clarity on whether voices, faces, images, and training material were obtained with valid permissions. This makes contractual protection and supplier documentation important in synthetic media marketing services market procurement. The EU AI Act includes transparency obligations for certain AI-generated content, adding a compliance consideration for cross-border campaign operations. Buyers are paying closer attention to model documentation, content records, and indemnification terms. The synthetic media marketing services market favors providers that can show a clear consent process and assign responsibilities for legal risk.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Short-Form Video and Multilingual Social Commerce
- Brand Adoption of Virtual Influencers and AI Avatars
- Deepfake-Driven Trust Erosion and Brand Safety Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Creative Production and Post-Production Automation Services held 32.83% of service-type revenue in 2025. It gives buyers in the synthetic media marketing services market a practical way to increase the number of assets produced from an approved campaign brief. Agencies can automate resizing, editing, localization, and format adaptation without redesigning their full creative process. This makes the service easier to adopt than a complete replacement of established agency and in-house production teams. Virtual Influencer and Avatar Campaign Services are projected to expand at a 17.38% CAGR through 2031.
The faster growth reflects a move from isolated avatar activations toward recurring digital personalities used across product launches and regional campaigns. HeyGen reported USD 200 million in annual recurring revenue in June 2026, indicating material demand for avatar video services. The company also reported that it remained cash-flow break-even in 2026. Research indicates that newer virtual personas can retain a novelty advantage in consumer engagement. Synthetic Voice and Localization Services, consulting, real-time ad serving, and audience simulation extend the range of work available to providers in the synthetic media marketing services market.
Managed Services accounted for 48.60% of deployment-model revenue in 2025. Enterprise buyers in the synthetic media marketing services market often choose managed delivery because it assigns parts of governance, quality assurance, and brand safety work to the provider. This structure is useful when teams lack specialist staff to assess models, manage fine-tuning, and review compliance. It also creates a defined contract for buyers who need a campaign result rather than separate software access. Private Model and Enterprise Customization Services are projected to record a 17.63% CAGR through 2031.
The growth rate shows that large users are beginning to develop proprietary content capabilities after gaining experience with managed programs. Synthesia raised USD 200 million in a Series E round at a USD 4 billion valuation in January 2026. The company had surpassed USD 100 million in annual recurring revenue in April 2025. Self-Service SaaS-Enabled Services give smaller buyers an entry point, while Integration and API Enablement Services connect generation to campaign and customer systems. Adobe expanded GenStudio integrations with Amazon Ads, Google Marketing Platform, LinkedIn, and TikTok in 2025.
Complete Report Scope:
- By Service Type
- Synthetic Strategy and Consulting
- Virtual Influencer and Avatar Campaign Services
- Synthetic Voice and Localization Services
- Creative Production and Post-Production Automation Services
- Other Service Types
- By Deployment Model
- Managed Services
- Self-Service SaaS-Enabled Services
- Integration and API Enablement Services
- Private Model and Enterprise Customization Services
- By Customer Type
- Large Enterprises
- Small and Medium-Sized Enterprises
- By End-use Industry
- Retail and E-commerce
- Media and Entertainment
- IT and Telecom
- BFSI
- Healthcare and Life Sciences
- Other End-use industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounted for 48.26% of global revenue in 2025, the largest share of the synthetic media marketing services market. The region benefits from a concentration of synthetic media marketing services and advertising technology, early enterprise adoption, and well-funded specialist suppliers. The United States combines a large advertiser base with an active environment for platform development. ElevenLabs completed 2025 with more than USD 330 million in annual recurring revenue and raised USD 500 million in a Series D round during February 2026.Synthesia exceeded USD 100 million in annual recurring revenue in April 2025 before its January 2026 funding round.
Asia-Pacific is projected to register a 17.59% CAGR through 2031, the highest regional growth rate. China is expanding enterprise AI advertising tools into Japan and Southeast Asia, intensifying regional competition on price and product capabilities. Japan is developing local-language avatar systems that address linguistic and cultural requirements not fully served by global platforms. Shiseido introduced AI avatar live commerce on its official e-commerce site for younger consumers.
India provides an example of adoption in a regulated sector through Shriram Life Insurance's multilingual campaign. South Korea adds demand from its entertainment sector and global virtual-content audience. South America is at an earlier stage, with Brazil and Argentina acting as key demand centers. The Middle East is supported by digital transformation programs in Saudi Arabia and the United Arab Emirates. Africa remains nascent, with South Africa, Nigeria, and Egypt leading demand from mobile-first advertising and international brand localization.
- Adobe Inc.
- Alphabet Inc.
- Microsoft Corporation
- Meta Platforms, Inc.
- Amazon.com, Inc.
- Canva Pty Ltd.
- OpenAI, L.L.C.
- Synthesia Limited
- HeyGen Technology Inc.
- Runway AI, Inc.
- D-ID Ltd.
- ElevenLabs Inc.
- Stability AI Ltd.
- Descript, Inc.
- Lightricks Ltd.
- Midjourney, Inc.
- Sprinklr, Inc.
- Salesforce, Inc.
- Persado Inc.
- DeepBrain AI Inc.
- Soul Machines Limited
- UneeQ Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Rising Demand for Scalable, Personalized Marketing Content
- 4.3.2 Falling Inference Costs and Creative-Suite Integration
- 4.3.3 Growth of Short-Form Video and Multilingual Social Commerce
- 4.3.4 Brand Adoption of Virtual Influencers and AI Avatars
- 4.3.5 Retail Media Networks Needing Synthetic Creative Variants for Closed-Loop Testing
- 4.3.6 Consent-Based Digital-Talent Marketplaces Unlocking Licensed Voice and Likeness Campaigns
- 4.4 Market Restraints
- 4.4.1 Copyright, Likeness, and Training-Data Liability Exposure
- 4.4.2 Deepfake-Driven Trust Erosion and Brand Safety Risk
- 4.4.3 Provenance Watermark Fragmentation Across Advertising Platforms
- 4.4.4 Talent Union and Creator Contract Restrictions on Synthetic Replication
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Synthetic Strategy and Consulting
- 5.1.2 Virtual Influencer and Avatar Campaign Services
- 5.1.3 Synthetic Voice and Localization Services
- 5.1.4 Creative Production and Post-Production Automation Services
- 5.1.5 Other Service Types
- 5.2 By Deployment Model
- 5.2.1 Managed Services
- 5.2.2 Self-Service SaaS-Enabled Services
- 5.2.3 Integration and API Enablement Services
- 5.2.4 Private Model and Enterprise Customization Services
- 5.3 By Customer Type
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-Sized Enterprises
- 5.4 By End-use Industry
- 5.4.1 Retail and E-commerce
- 5.4.2 Media and Entertainment
- 5.4.3 IT and Telecom
- 5.4.4 BFSI
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Other End-use industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Qatar
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Alphabet Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 Meta Platforms, Inc.
- 6.4.5 Amazon.com, Inc.
- 6.4.6 Canva Pty Ltd.
- 6.4.7 OpenAI, L.L.C.
- 6.4.8 Synthesia Limited
- 6.4.9 HeyGen Technology Inc.
- 6.4.10 Runway AI, Inc.
- 6.4.11 D-ID Ltd.
- 6.4.12 ElevenLabs Inc.
- 6.4.13 Stability AI Ltd.
- 6.4.14 Descript, Inc.
- 6.4.15 Lightricks Ltd.
- 6.4.16 Midjourney, Inc.
- 6.4.17 Sprinklr, Inc.
- 6.4.18 Salesforce, Inc.
- 6.4.19 Persado Inc.
- 6.4.20 DeepBrain AI Inc.
- 6.4.21 Soul Machines Limited
- 6.4.22 UneeQ Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 生成式人工智慧引擎最佳化(GEO)平台市場:按產品類型、部署類型、平台功能、技術類型、應用、最終用戶和地區分類
 創新通路情報:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)人工智慧搜尋可見性服務:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)AI創新最佳化服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 生成式引擎最佳化(GEO)平台市場:依產品類型、應用、部署類型、技術、平台功能、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測人工智慧搜尋最佳化軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 內容自動化人工智慧工具市場規模、佔有率和成長分析:按工具功能、部署模式、應用領域、企業規模、銷售管道和地區分類-2026-2033年產業預測
 2026年全球銷售說明摘要工具市場報告2026年Web3.0人工智慧生成內容(AIGC)引擎全球市場報告
 設計領域的人工智慧 (AI) 市場:策略洞察與預測 (2026–2031)