


 |
市場調查報告書
商品編碼
2119221
遊戲網紅行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Gaming Influencer Marketing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,遊戲網紅行銷服務的市場規模預計將在 2025 年達到 20.9 億美元,在 2026 年達到 23.6 億美元,在 2031 年達到 43.4 億美元,從 2026 年到 2031 年的複合成長率為 12.96%。
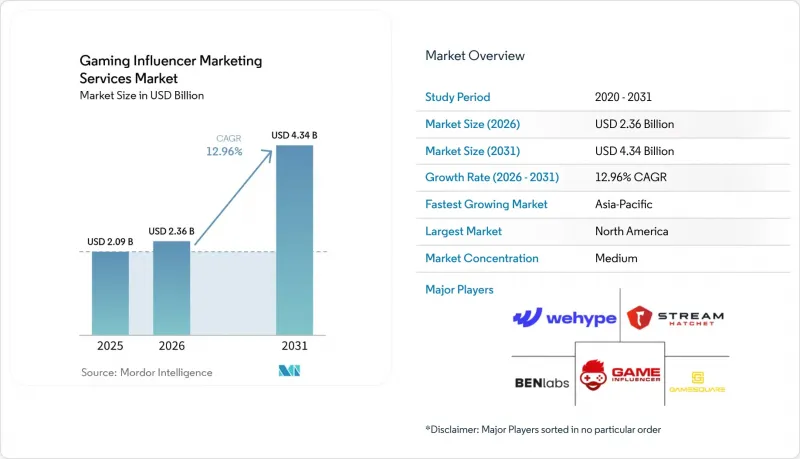
本報告依服務類型(宣傳活動策略及規劃服務、網紅甄選及簽約服務、宣傳活動執行及管理服務、內容創作及創新服務等)、平台(YouTube、Twitch等)、最終用戶(遊戲發行商及開發人員等)及地區進行分類。市場預測以美元計價。
全球遊戲網紅行銷服務市場趨勢與洞察
核心遊戲用戶中廣告規避行為日益增加。
當廣告打斷遊戲或觀看時,玩家通常會產生負面反應。 2025年發表在學術期刊上的一項研究表明,玩家對遊戲內廣告的態度會強烈影響其在任何遊戲情境下的廣告規避行為。這種行為透過讓贊助內容與遊戲玩法、評測和直播互動相結合,提高了創作者內容的相關性。這種形式確保品牌訊息與觀眾選擇觀看的內容一同呈現。隨著發行商將重點從干擾性廣告轉向以主導的溝通,遊戲網紅行銷服務市場將從中受益。代理商可以透過將創作者與適合宣傳活動的遊戲和受眾進行配對來支持這一轉變。
直播和創作者主導的遊戲發現的成長
直播仍然是觀眾發現遊戲、了解最新動態並對新遊戲發表意見的重要途徑。 YouTube Gaming 在 2025 年第三季的遊戲內容觀看時長達了 25 億小時。同一份報告顯示,TikTok Live 在同一季度的觀看時長達了 91 億小時。發行商可以利用 Twitch 和 YouTube 進行長期推廣活動,而 TikTok Live 和短視訊格式則更適合頻繁更新。這導致需要持續進行一些工作,例如向創作者提供簡報、管理內容排程、跨平台協調以及宣傳活動報告。遊戲網紅行銷服務市場正受益於這種對跨多種觀看格式協調活動日益成長的需求。
針對贊助遊戲內容,制定更嚴格的資訊揭露和青少年保護法規
資訊揭露義務可能會收緊贊助遊戲內容的營運要求。美國聯邦貿易委員會 (FTC) 指出,網紅應明確揭露其與品牌的重要關係,包括涉及報酬、免費產品、遊戲啟動碼或提前體驗等。代理商必須建立相應的流程,確保在其廣播、影片和社交媒體貼文中清晰揭露相關資訊。尤其需要關注青少年受眾,因為廣告和數據處理行為將受到更多限制。儘管遊戲網紅行銷服務市場在宣傳活動執行方面面臨新的挑戰,但擁有可靠合規流程的服務提供者可以降低客戶風險。
細分市場分析
2025年,宣傳活動執行與管理服務將佔遊戲網紅行銷服務市佔率的31.80%。此細分市場涵蓋了為新遊戲發布、更新和可下載內容(DLC)開展創作者宣傳活動所需的各項實際操作。發行商在大型遊戲發佈時往往時間有限,難以快速提升知名度。因此,他們需要為創作者提供統一的簡報、關鍵分發管道、平台支援、內容傳送以及宣傳活動後評估。當品牌使用Twitch Drops或其他類似活動,將觀看行為與遊戲內獎勵掛鉤時,這項服務也至關重要。由於成功的宣傳活動執行需要創作者、發行商、平台和玩家社群之間的緊密合作,因此該細分市場將繼續佔據舉足輕重的地位。
影響者甄選和簽約服務的目標客戶是那些本身缺乏大規模創作者網路的客戶。內容創作和創新服務則有助於客戶將宣傳活動計畫轉化為針對創作者受眾和遊戲本身量身打造的素材。社區大使計畫服務支援與創作者在持續運作遊戲的整個生命週期內保持合作。根據 Lurkit 數據顯示,Bohemia Interactive 的 Frostline DLC 計畫透過其平台吸引了超過 1,100 位創作者參與。分析、歸因和報告服務預計將在 2026 年至 2031 年間以 13.71% 的複合年成長率成長。遊戲影響者行銷服務市場的這一部分主要由那些希望更清晰地了解創作者活動與商業性成果之間關聯的客戶所驅動。此外,當非遊戲品牌需要關於創作者排名、受眾匹配度和宣傳活動時間表的指南時,宣傳活動策略和規劃服務預計也將繼續發揮至關重要的作用。
區域分析
到2025年,北美將佔據遊戲網紅行銷服務市場39.40%的佔有率。該地區聚集了許多發行商、藝人經紀公司、效果行銷公司和創作者網路。此外,其法規環境也提升了能夠管理贊助內容揭露的機構的價值。美國聯邦貿易委員會(FTC)的指導意見要求明確披露品牌與網紅之間的“關鍵關係”,這凸顯了針對年輕受眾的遊戲活動需要正式的宣傳活動流程。
歐洲是PC和主機遊戲、電競贊助以及周邊設備產品行銷的另一個重要中心。德國、英國、法國和西班牙是這些領域宣傳活動活動的整體動力。 2025年電競世界盃合作夥伴俱樂部計畫涵蓋了106個來自歐洲各參賽隊伍的不同品牌。歐洲也擁有更廣泛的內容創作平台,這是廣告代理商必須關注的領域。預計亞太地區在2026年至2031年間將以13.93%的複合年成長率成長。東南亞高度依賴行動遊戲和短影片,而日本和韓國則擁有各自獨特的內容創作生態系統和平台偏好。這種情況要求廣告代理商擁有本地網路和平台專屬的營運知識。
儘管南美洲的市場佔有率較小,但它仍然是一個重要的市場,尤其是在巴西。在地化對於國際發行商的宣傳活動至關重要,因為如果不利用當地創作者或使用葡萄牙語進行溝通,他們的行銷活動可能會失去相關性。中東地區因沙烏地阿拉伯對電競世界盃的支持而備受關注,預計到2025年,觀看時長將達到1.68億小時。在非洲,系統化的網紅行銷服務仍處於起步階段。南非、奈及利亞和肯亞是潛在的切入點,但衡量工具和創作者變現基礎設施仍然有限。在遊戲網紅行銷服務市場,由於不同地區遊戲社群的發展程度有差異,在地化的宣傳活動設計不可或缺。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素對市場的影響
- 市場促進因素
- 核心遊戲用戶中廣告規避行為日益增加。
- 直播和創作者主導的遊戲發現的成長
- 非遊戲品牌在遊戲社群的廣告支出不斷成長
- 對基於效果的用戶獲取的需求已經超越了付費社交廣告。
- 透過即時服務內容日曆延長創作者活躍期
- 一款自助式贊助工具,可減輕宣傳活動設定的負擔。
- 市場限制因素
- 針對贊助遊戲內容,制定更嚴格的資訊揭露和青少年保護法規
- 遊戲產業的創作者不當行為與品牌安全風險
- 由於第二螢幕觀看而導致的跨平台歸因遺漏。
- 由於重要作品上映和舉辦活動,價格上漲。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 宣傳活動策略和規劃服務
- 影響者甄選和簽約服務
- 宣傳活動執行與管理服務
- 內容創作與創新服務
- 社區大使計畫服務
- 分析、歸因和報告服務
- 按平台
- YouTube
- Twitch
- TikTok
- 其他平台
- 最終用戶
- 遊戲發行商和開發商
- 電子競技組織和團隊
- 遊戲平台與市場
- 遊戲硬體和周邊設備製造商
- 遊戲用戶的非遊戲品牌
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 澳洲
- 印尼
- 泰國
- 越南
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 肯亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- GameSquare Holdings, Inc.
- Stream Hatchet, SLU
- BEN Group, Inc.
- Wehype Global AB
- GameInfluencer GmbH
- Viral Nation Inc.
- Derfit Enterprises Limited
- Kairos Media Ltd
- Socially Powerful Ltd
- Audiencly GmbH
- Mediabodies Limited
- Connect Management Ltd
- Valen Agency
- Disrupt Limited
- Madeviral Pte. Ltd.
- NeoReach Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the gaming influencer marketing services market size is projected to be USD 2.09 billion in 2025, USD 2.36 billion in 2026, and reach USD 4.34 billion by 2031, growing at a CAGR of 12.96% from 2026 to 2031.
This report is Segmented by Service Type (Campaign Strategy and Planning Services, Influencer Sourcing and Contracting Services, Campaign Activation and Management Services, Content Production and Creative Services, and More), Platform (YouTube, Twitch, and More), End User (Game Publishers and Developers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Gaming Influencer Marketing Services Market Trends and Insights
Rising Ad Avoidance in Core Gaming Audiences
Gaming audiences often react negatively when advertising interrupts play or viewing. A 2025 journal study found that attitudes toward in-game advertising strongly shaped ad-avoidance behavior across gaming contexts. This behavior makes creator content more relevant because sponsored activity can be integrated with gameplay, reviews, and live conversations. The format allows a brand message to appear alongside content that viewers have already chosen to watch. The gaming influencer marketing services market benefits when publishers shift their attention from interruptive exposure to creator-led communication. Agencies can support this shift by matching creators with games and audiences that fit the campaign.
Growth of Live Streaming and Creator-Led Game Discovery
Live streaming remains an important way for viewers to discover games, follow updates, and form opinions about new releases. YouTube Gaming recorded 2.5 billion hours of gaming content watched during the third quarter of 2025. The same report stated that TikTok Live reached 9.1 billion hours watched during that quarter. Publishers can use Twitch and YouTube for longer launch activity, while TikTok Live and short video formats can support frequent updates. This creates recurring work in creator briefing, content scheduling, platform coordination, and campaign reporting. The gaming influencer marketing services market gains from this broader need for coordinated activity across several viewing formats.
Tightening Disclosure and Youth-Safety Rules for Sponsored Gaming Content
Disclosure obligations can raise the operating requirements for sponsored gaming content. The Federal Trade Commission states that influencers should clearly disclose material relationships with brands. This includes relationships involving payment, free products, game keys, or early access. Agencies need processes that make disclosures clear in streams, videos, and social posts. Youth audiences require particular care because advertising and data practices are subject to additional restrictions. The gaming influencer marketing services market faces added campaign friction, but providers with reliable compliance workflows can reduce risk for clients.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Non-Endemic Brand Spend into Gaming Communities
- Demand for Performance-Based User Acquisition Beyond Paid Social
- Creator Fraud and Brand-Safety Risk in Gaming Niches
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Campaign Activation and Management Services held 31.80% of the Gaming Influencer Marketing Services Market share in 2025. The segment covers the practical work required to run creator campaigns around launches, updates, and downloadable content. Publishers often have a limited period to create awareness when a major title is released. They need coordinated creator briefing, key distribution, platform support, content delivery, and post-campaign review. This service is also relevant when brands use Twitch Drops or similar initiatives that link viewing activity with in-game rewards. The segment remains important because campaign execution requires close coordination across creators, publishers, platforms, and player communities.
Influencer Sourcing and Contracting Services serve clients that do not maintain large internal creator networks. Content Production and Creative Services help convert a campaign plan into material that fits a creator's audience and the game itself. Community and Ambassador Program Services support ongoing contact with creators throughout a live-service game's lifecycle. Lurkit stated that Bohemia Interactive's Frostline DLC program onboarded more than 1,100 creators through its platform. Analytics, Attribution and Reporting Services is projected to grow at a 13.71% CAGR from 2026 to 2031. This part of the Gaming Influencer Marketing Services Market size is supported by clients that want clearer links between creator activity and commercial results. Campaign Strategy and Planning Services can also remain relevant where non-gaming brands need guidance on creator tiers, audience fit, and campaign timing.
Complete Report Scope:
- By Service Type
- Campaign Strategy and Planning Services
- Influencer Sourcing and Contracting Services
- Campaign Activation and Management Services
- Content Production and Creative Services
- Community and Ambassador Program
- Analytics, Attribution and Reporting Services
- By Platform
- YouTube
- Twitch
- TikTok
- Other Platforms
- By End User
- Game Publishers and Developers
- Esports Organizations and Teams
- Gaming Platforms and Marketplaces
- Gaming Hardware and Peripheral Manufacturers
- Non-Gaming Brands Targeting Gaming Audiences
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Indonesia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America held 39.40% of the Gaming Influencer Marketing Services Market share in 2025. The region has a large concentration of publishers, talent managers, performance marketing firms, and creator networks. Its regulatory environment also raises the value of agencies that can manage sponsored-content disclosures. The Federal Trade Commission's guidance requires clear disclosure of a material connection between a brand and an influencer. This helps explain the need for formal campaign processes in youth-oriented gaming activity.
Europe is another important cluster for PC and console gaming, esports sponsorship, and peripheral marketing. Germany, the United Kingdom, France, and Spain contribute to campaign demand across these activities. The 2025 Esports World Cup partner-club program recorded 106 unique brands across European teams. Europe also has a wider range of creator platforms that agencies must support. Asia-Pacific is projected to grow at a 13.93% CAGR from 2026 to 2031. Southeast Asia relies heavily on mobile gaming and short-form video, while Japan and South Korea have distinct creator ecosystems and platform preferences. These conditions require local relationships and platform-specific operating knowledge.
South America has a smaller share but remains relevant, especially in Brazil. Localization is important because campaigns from foreign publishers can lose relevance when they do not use local creators or Portuguese-language communication. The Middle East gained visibility through Saudi Arabia's support for the Esports World Cup, which recorded 168 million hours watched in 2025. Africa remains at an earlier stage in structured influencer marketing services. South Africa, Nigeria, and Kenya represent potential entry points, although measurement tools and creator monetization infrastructure remain limited. The gaming influencer marketing services market will need localized campaign design as gaming communities develop differently across these regions.
- GameSquare Holdings, Inc.
- Stream Hatchet, S.L.U.
- BEN Group, Inc.
- Wehype Global AB
- GameInfluencer GmbH
- Viral Nation Inc.
- Derfit Enterprises Limited
- Kairos Media Ltd
- Socially Powerful Ltd
- Audiencly GmbH
- Mediabodies Limited
- Connect Management Ltd
- Valen Agency
- Disrupt Limited
- Madeviral Pte. Ltd.
- NeoReach Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Rising Ad Avoidance In Core Gaming Audiences
- 4.3.2 Growth of Live Streaming and Creator-Led Game Discovery
- 4.3.3 Expansion of Non-Endemic Brand Spend Into Gaming Communities
- 4.3.4 Demand for Performance-Based User Acquisition Beyond Paid Social
- 4.3.5 Live-Service Content Calendars Expanding Creator Activation Windows
- 4.3.6 Self-Serve Sponsorship Tools Reducing Campaign Setup Friction
- 4.4 Market Restraints
- 4.4.1 Tightening Disclosure and Youth-Safety Rules For Sponsored Gaming Content
- 4.4.2 Creator Fraud and Brand-Safety Risk In Gaming Niches
- 4.4.3 Cross-Platform Attribution Leakage From Second-Screen Viewing
- 4.4.4 Rate Inflation Around Tentpole Launches and Event Spikes
- 4.5 Industry Value-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat Of New Entrants
- 4.8.2 Bargaining Power Of Buyers
- 4.8.3 Bargaining Power Of Suppliers
- 4.8.4 Threat Of Substitutes
- 4.8.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Campaign Strategy and Planning Services
- 5.1.2 Influencer Sourcing and Contracting Services
- 5.1.3 Campaign Activation and Management Services
- 5.1.4 Content Production and Creative Services
- 5.1.5 Community and Ambassador Program
- 5.1.6 Analytics, Attribution and Reporting Services
- 5.2 By Platform
- 5.2.1 YouTube
- 5.2.2 Twitch
- 5.2.3 TikTok
- 5.2.4 Instagram
- 5.2.5 Other Platforms
- 5.3 By End User
- 5.3.1 Game Publishers and Developers
- 5.3.2 Esports Organizations and Teams
- 5.3.3 Gaming Platforms and Marketplaces
- 5.3.4 Gaming Hardware and Peripheral Manufacturers
- 5.3.5 Non-Gaming Brands Targeting Gaming Audiences
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Colombia
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 South Korea
- 5.4.4.4 India
- 5.4.4.5 Australia
- 5.4.4.6 Indonesia
- 5.4.4.7 Thailand
- 5.4.4.8 Vietnam
- 5.4.4.9 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Kenya
- 5.4.6.5 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 GameSquare Holdings, Inc.
- 6.4.2 Stream Hatchet, S.L.U.
- 6.4.3 BEN Group, Inc.
- 6.4.4 Wehype Global AB
- 6.4.5 GameInfluencer GmbH
- 6.4.6 Viral Nation Inc.
- 6.4.7 Derfit Enterprises Limited
- 6.4.8 Kairos Media Ltd
- 6.4.9 Socially Powerful Ltd
- 6.4.10 Audiencly GmbH
- 6.4.11 Mediabodies Limited
- 6.4.12 Connect Management Ltd
- 6.4.13 Valen Agency
- 6.4.14 Disrupt Limited
- 6.4.15 Madeviral Pte. Ltd.
- 6.4.16 NeoReach Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 思想領袖行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)整合行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)創收型行銷服務市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 內容行銷市場:依內容類型、格式、通路、買家類型和產業分類-2026-2032年全球市場預測內容行銷軟體市場:按解決方案類型、應用、產業、部署模式和組織規模分類 - 全球預測(2026-2032 年)
 2026年全球內容行銷軟體市場報告2026年全球人工智慧內容行銷市場報告
 內容市場規模、佔有率和成長分析(按內容類型、內容格式、主要讀者、分發管道、最終用戶和地區分類)-2026-2033年產業預測
 內容行銷市場分析及預測(至2035年):按類型、產品類型、服務、技術、應用、部署類型、最終用戶、解決方案和模式分類內容行銷推廣服務市場:按服務類型、內容類型、組織規模和最終用戶分類 - 2026-2032 年全球預測