


 |
市場調查報告書
商品編碼
2119041
思想領袖行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)Thought Leadership Marketing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,思想領袖行銷服務市場規模將從 2025 年的 17.1 億美元和 2026 年的 18.5 億美元成長到 2031 年的 26.8 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 7.69%。
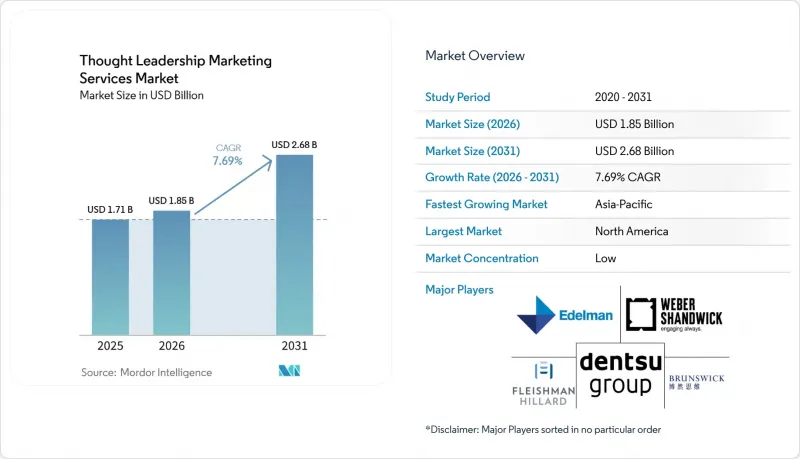
本報告按終端用戶產業(零售和電子商務、媒體和娛樂、醫療保健和生命科學、旅遊和酒店、消費品以及其他行業[銀行、金融服務和保險、教育、汽車、IT和電信等])和地區(北美、歐洲、亞太、南美以及中東和非洲)進行細分。市場預測以美元計價。
全球思想領袖行銷服務市場趨勢與洞察
基於信任的B2B差異化需求日益成長
思想領袖行銷服務市場正受益於企業在複雜的採購決策中對信任日益成長的需求。到2025年,73%的決策者認為,在評估企業能力時,思想領袖比行銷或產品資料更可靠。引人入勝的內容促使75%的決策者開始研究他們從未考慮過的供應商。調查也顯示,60%的決策者願意支付溢價,與展現出強大思想領袖的供應商合作。這點意義重大,因為採購團隊包含一些不直接與銷售團隊互動,但仍能影響最終決策的人員。能夠將專業知識轉化為清晰、基於事實的內容的供應商,無需完全依賴直接行銷方式,就能觸達這些「隱形負責人」。
LinkedIn主導的高階主管曝光計畫擴大
LinkedIn 已成為提升高階主管在思想領袖行銷服務市場知名度的有效管道。 B2B 行銷領導者在 2024 年第三季至 2025 年第三季期間,LinkedIn 廣告預算成長了 31.7%,而 Google 廣告支出僅成長了 6%。 LinkedIn 報告顯示,高階主管(C 級主管)發布的內容瀏覽量和互動量是其他會員類別內容的五倍。這種轉變推動了對代寫、訊息開發、研究設計和通路特定傳播支援的需求成長。高階主管溝通也正從偶爾的公關活動轉變為持續的商業性定位要素。最有效的方案會利用高階主管觀點來闡釋複雜的商業挑戰,而不是簡單地重複產品訊息。
在較長的購買週期中,證明收入歸屬的難度很高。
由於企業對企業 (B2B) 銷售週期通常長達 6 至 18 個月,思想領袖行銷服務市場始終面臨衡量方面的挑戰。標準的報告週期可以捕捉到銷售後期的行為,但往往忽略早期階段建立品牌認知度和信譽度的內容。這使得將白皮書、研究報告或經營團隊報導與最終成交的銷售業績連結起來變得困難。預算經理在評估季度表現的壓力下,如果無法驗證可審計的投資報酬率 (ROI),可能會削減長期專案的預算。雖然留存測試和行銷組合建模可以提供更清晰的視角,但這需要數據分析技能和投資,而許多中型客戶恰恰缺乏這些。因此,即使某個項目提高了買家的興趣,也可能導致初始合約金額較小或合約續約困難。
細分市場分析
2025年,思想領袖行銷服務市場中,零售和電子商務將佔全球整體銷售額的28.12%。數位通路競爭日益激烈,促使零售商超越價格比較和產品促銷,建立自身權威。零售商和平台正利用客戶情緒分析、品類報告和永續性審計,為受眾提供再次參與其內容互動的理由。這些項目幫助企業以能夠引起客戶、合作夥伴和投資者共鳴的語言闡述品類變化。這一點也至關重要,因為人工智慧驅動的產品發現可能會降低日常產品頁面的可見度,這對思想領袖行銷服務產業來說是一個嚴峻的挑戰。
預計2026年至2031年間,醫療保健和生命科學產業的複合年成長率將達到11.41%,使得面向這些終端用戶的思想領袖行銷服務市場成為成長最快的終端用戶市場之一。科學可信度、監管複雜性和冗長的採購流程使得證據品質在該行業的溝通中至關重要。製藥、生物技術和醫療技術公司正在從通用數位訊息轉向以專業知識為支撐的內容。美國食品藥物管理局(FDA)的《數位健康傳播框架》和歐洲藥品管理局(EMA)關於科學傳播的指南進一步強調了對受控、準確且可引用內容的需求。媒體和娛樂公司正在利用這些服務來定位技術和創作經濟的轉變,而旅遊、酒店、消費品、金融服務、教育、汽車、IT和電信行業則正在利用整個思想領袖行銷服務行業進行聲譽管理、投資者故事講述並提高行業媒體曝光度。
區域分析
到2025年,北美將佔據思想領袖行銷服務市場46.48%的佔有率。該地區擁有龐大的B2B買家群體、成熟的傳播機構,以及LinkedIn作為專業討論平台的廣泛應用。美國仍然是該市場的核心,因為全球金融服務、科技和醫療保健等行業的主要商業中心都集中在美國。到2026年,89%的北美行銷領導者表示,他們的預算能夠支持收入和成長目標,其中69%的人預計預算將會增加。加拿大和墨西哥則透過對受監管行業經營團隊定位所需的專業服務以及跨境供應鏈,推動了市場需求。
歐洲在思想領袖行銷服務市場中仍然佔據重要地位,這得益於英國和德國成熟的企業事務和戰略傳播實踐。宏盟集團於2025年11月收購IPG,重組了旗下代理商的業務組合,並在2026年繼續重建客戶關係。 2026年6月,高林公關和凱徹姆公關合併,採用統一的代理模式;同時,福萊希曼希拉德公關公司也整合了波特諾維利公關公司。除了德國的專業服務公司外,法國的奢侈品牌和金融服務公司也在拓展其在大型跨國公司以外的市場需求。亞太地區,在印度、澳洲、中國和韓國的推動下,也因B2B技術活動的增加和跨國業務的拓展而不斷擴大市場。
預計2026年至2031年間,中東思想領袖行銷服務市場將以11.51%的複合年成長率成長。沙烏地阿拉伯的「2030願景」和阿拉伯聯合大公國的數位經濟議程正在推動相關傳播項目,旨在將機構和企業定位為知識主導組織。到2026年,該地區68%的傳播機構預計收入將實現成長,高於2025年的56%。以阿拉伯語為主要語言的內容仍然是一個明顯的本地服務機遇,因為全球內容項目通常需要根據本地受眾進行調整。雖然南美洲和非洲的收入規模仍然小規模,但巴西的專業服務服務業和南非的企業溝通基礎設施正在為永續發展故事講述和麵向國際投資者的經營團隊形象提升等專業服務提供支持。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 基於信任的B2B差異化需求日益成長
- LinkedIn主導的高階主管意識提升計畫擴大
- 利用獨家調查和數據製作內容,提高投資報酬率。
- 整合公關、需求創造和經營團隊品牌預算。
- 在複雜的B2B採購中,「隱形採購負責人」的影響力日益增強
- GenAI驅動的發現和引用可見性的重要性日益增加。
- 市場限制因素
- 難以證明整個長期購買週期內的收入歸屬。
- 內容飽和和自然觸達率下降
- 高階主管缺乏時間,內容處理能力不足
- 與法律事務、合規和人工智慧管治。
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 科技趨勢
- 監理情勢
- 波特五力分析
第5章:預測市場規模與成長率
- 按最終用戶行業分類
- 零售與電子商務
- 媒體與娛樂
- 醫學與生命科學
- 旅遊與飯店
- 消費品
- 其他終端用戶產業(銀行、金融服務與保險、教育、汽車、IT/電信等)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Edelman Holdings Inc.
- Brunswick Group LLP
- Weber Shandwick Inc.
- FleishmanHillard Inc.
- Golin Inc
- APCO Worldwide, LLC
- Finn Partners, LLC
- Bully Pulpit International, LLC
- Dentsu Inc.
- FT Longitude Limited
- Burson LLC
- Ruder Finn, Inc.
- Walker Sands Communications, LLC
- Ogilvy Public Relations Worldwide LLC
- PAN Communications, Inc.
- Manifest, Inc.
- Teneo Holdings, LLC
- 2X Marketing, LLC
- Thinkers360, LLC
- Stagwell Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the thought leadership marketing services market size is projected to expand from USD 1.71 billion in 2025 and USD 1.85 billion in 2026 to USD 2.68 billion by 2031, registering a CAGR of 7.69% between 2026 and 2031.
This report is Segmented by End User Industry (Retail and E-Commerce, Media and Entertainment, Healthcare and Life Sciences, Travel and Hospitality, Consumer Goods, and More [BFSI, Education, Automotive, and IT and Telecom and More]), and Geography (North America, Europe, Asia-Pacific, South America, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Thought Leadership Marketing Services Market Trends and Insights
Rising Demand for Trust-Based B2B Differentiation
The Thought Leadership Marketing Services Market benefits from a stronger need for trust in complex B2B buying decisions. In 2025, 73% of decision-makers thought leadership was more trustworthy than marketing materials or product sheets when assessing organizational capabilities. Compelling content prompted 75% of decision-makers to research a provider they had not considered before. The same research found that 60% were willing to pay a premium to work with a provider that produced strong thought leadership. This matters as buying groups include people who may not directly engage with sales teams but can influence the final choice. Providers who turn expert knowledge into clear, evidence-based content can reach these hidden buyers without relying solely on direct outreach.
Expansion of LinkedIn-Led Executive Visibility Programs
LinkedIn has become a practical channel for executive visibility within the Thought Leadership Marketing Services Market. B2B marketing leaders increased LinkedIn advertising budgets by 31.7% between Q3 2024 and Q3 2025, compared with 6% growth in Google spending. LinkedIn reports that C-suite content attracts 5 times more views and engagement than content from other member categories. This shift expands demand for ghostwriting, message development, research design, and channel-specific distribution support. It also moves executive communication from an occasional public relations activity toward a sustained part of commercial positioning. The strongest programs use executive perspectives to explain difficult business issues rather than repeat product messages.
Difficulty Proving Revenue Attribution Across Long Buying Cycles
The Thought Leadership Marketing Services Market faces a persistent measurement challenge because enterprise B2B sales cycles often run for 6 to 18 months. Standard reporting windows may capture late-stage actions but miss the early content that establishes awareness and credibility. This makes it difficult to connect a white paper, research report, or executive article to closed revenue with confidence. Budget owners under quarterly review pressure may reduce long-term programs when they cannot see an auditable return on investment. Holdout testing and marketing mix modeling can improve the picture, but they require data skills and investment that many mid-sized clients do not have. The result can be smaller initial contracts and more difficult renewals, even when the program strengthens buyer consideration.
Other drivers and restraints analyzed in the detailed report include:
- Stronger ROI From Original Research and Data-Led Content
- Convergence of PR, Demand Generation, and Executive Branding Budgets
- Content Saturation and Declining Organic Reach
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Retail and e-commerce represented 28.12% of global revenue in the Thought Leadership Marketing Services Market in 2025. Competition in digital channels encourages retailers to build authority beyond price comparison and product promotion. Retailers and platforms use customer sentiment studies, category reports, and sustainability audits to give audiences a reason to return to their content. These programs help companies explain category change in language that is useful to customers, partners, and investors. They are also relevant when AI-mediated discovery can reduce the visibility of routine product pages, a central issue for the Thought Leadership Marketing Services Industry.
Healthcare and life sciences are forecast to grow at an 11.41% CAGR between 2026 and 2031, making the Thought Leadership Marketing Services Market for these end users one of the fastest-growing end-user opportunities. Scientific credibility, regulatory complexity, and long procurement processes make evidence quality central to communication in this segment. Pharmaceutical, biotech, and medtech organizations are moving away from generic digital messages toward content supported by subject matter expertise. FDA digital health communication frameworks and the European Medicines Agency's guidance on scientific dissemination reinforce the need for controlled, accurately attributed content. Media and entertainment firms use services to frame technology and creator-economy change, while travel, hospitality, consumer goods, financial services, education, automotive, IT, and telecom use them for reputation, investor narratives, and trade-media visibility across the Thought Leadership Marketing Services Industry.
Complete Report Scope:
- By End User Industry
- Retail and E-commerce
- Media and Entertainment
- Healthcare and Life Sciences
- Travel and Hospitality
- Consumer Goods
- Other End User Industries (BFSI, Education, Automotive, and IT and Telecom amongst Others)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounted for 46.48% of the Thought Leadership Marketing Services Market share in 2025. The region has a large base of B2B enterprise buyers, established communications agencies, and widespread use of LinkedIn for professional discussion. The United States remains central because global firms in financial services, technology, and healthcare are concentrated in major business centers. In 2026, 89% of North American marketing leaders said their budgets supported revenue and growth goals, while 69% expected budget increases. Canada and Mexico add demand through professional services and cross-border supply chains that need executive positioning in regulated industries.
Europe remains an important part of the Thought Leadership Marketing Services Market, supported by established corporate affairs and strategic communications practices in the United Kingdom and Germany. The November 2025 Omnicom acquisition of IPG led to agency portfolio changes that continue to reshape client relationships in 2026. Golin and Ketchum combined under a unified agency model in June 2026, while FleishmanHillard integrated Porter Novelli during the same period. Germany's professional services companies, together with French luxury and financial services firms, broaden demand beyond large multinationals. Asia-Pacific, led by India, Australia, China, and South Korea, is also expanding as B2B technology activity and cross-border business development increase.
The Middle East is forecast to grow at an 11.51% CAGR from 2026 to 2031 in the Thought Leadership Marketing Services Market. Saudi Vision 2030 and the UAE's digital economy agenda support communications programs that position institutions and companies as knowledge-led organizations. In 2026, 68% of communications agencies in the region expected revenue growth, up from 56% in 2025. Arabic-first content remains a clear local service opportunity because global content programs often require adaptation for regional audiences. South America and Africa remain smaller in terms of revenue, but Brazil's professional services sector and South Africa's corporate communications base support specialized work in sustainability narratives and executive visibility for international investors.
- Edelman Holdings Inc.
- Brunswick Group LLP
- Weber Shandwick Inc.
- FleishmanHillard Inc.
- Golin Inc
- APCO Worldwide, LLC
- Finn Partners, LLC
- Bully Pulpit International, LLC
- Dentsu Inc.
- FT Longitude Limited
- Burson LLC
- Ruder Finn, Inc.
- Walker Sands Communications, LLC
- Ogilvy Public Relations Worldwide LLC
- PAN Communications, Inc.
- Manifest, Inc.
- Teneo Holdings, LLC
- 2X Marketing, LLC
- Thinkers360, LLC
- Stagwell Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Trust-Based B2B Differentiation
- 4.2.2 Expansion of LinkedIn-Led Executive Visibility Programs
- 4.2.3 Stronger ROI From Original Research and Data-Led Content
- 4.2.4 Convergence of PR, Demand Generation, and Executive Branding Budgets
- 4.2.5 Rising Influence of Hidden Buyers in Complex B2B Purchases
- 4.2.6 Growing Importance of GenAI Discovery and Citation Visibility
- 4.3 Market Restraints
- 4.3.1 Difficulty Proving Revenue Attribution Across Long Buying Cycles
- 4.3.2 Content Saturation and Declining Organic Reach
- 4.3.3 Executive Time Scarcity and Low Content Throughput
- 4.3.4 Higher Legal, Compliance, and AI Governance Burdens
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End User Industry
- 5.1.1 Retail and E-commerce
- 5.1.2 Media and Entertainment
- 5.1.3 Healthcare and Life Sciences
- 5.1.4 Travel and Hospitality
- 5.1.5 Consumer Goods
- 5.1.6 Other End User Industries (BFSI, Education, Automotive, and IT and Telecom amongst Others)
- 5.2 By Geography
- 5.2.1 North America
- 5.2.1.1 United States
- 5.2.1.2 Canada
- 5.2.1.3 Mexico
- 5.2.2 South America
- 5.2.2.1 Brazil
- 5.2.2.2 Argentina
- 5.2.2.3 Chile
- 5.2.2.4 Rest of South America
- 5.2.3 Europe
- 5.2.3.1 Germany
- 5.2.3.2 United Kingdom
- 5.2.3.3 France
- 5.2.3.4 Italy
- 5.2.3.5 Spain
- 5.2.3.6 Rest of Europe
- 5.2.4 Asia-Pacific
- 5.2.4.1 China
- 5.2.4.2 Japan
- 5.2.4.3 India
- 5.2.4.4 South Korea
- 5.2.4.5 Australia
- 5.2.4.6 Rest of Asia-Pacific
- 5.2.5 Middle East
- 5.2.5.1 United Arab Emirates
- 5.2.5.2 Saudi Arabia
- 5.2.5.3 Qatar
- 5.2.5.4 Rest of Middle East
- 5.2.6 Africa
- 5.2.6.1 South Africa
- 5.2.6.2 Egypt
- 5.2.6.3 Nigeria
- 5.2.6.4 Rest of Africa
- 5.2.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Edelman Holdings Inc.
- 6.4.2 Brunswick Group LLP
- 6.4.3 Weber Shandwick Inc.
- 6.4.4 FleishmanHillard Inc.
- 6.4.5 Golin Inc
- 6.4.6 APCO Worldwide, LLC
- 6.4.7 Finn Partners, LLC
- 6.4.8 Bully Pulpit International, LLC
- 6.4.9 Dentsu Inc.
- 6.4.10 FT Longitude Limited
- 6.4.11 Burson LLC
- 6.4.12 Ruder Finn, Inc.
- 6.4.13 Walker Sands Communications, LLC
- 6.4.14 Ogilvy Public Relations Worldwide LLC
- 6.4.15 PAN Communications, Inc.
- 6.4.16 Manifest, Inc.
- 6.4.17 Teneo Holdings, LLC
- 6.4.18 2X Marketing, LLC
- 6.4.19 Thinkers360, LLC
- 6.4.20 Stagwell Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 遊戲網紅行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)整合行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)創收型行銷服務市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 內容行銷市場:依內容類型、格式、通路、買家類型和產業分類-2026-2032年全球市場預測內容行銷軟體市場:按解決方案類型、應用、產業、部署模式和組織規模分類 - 全球預測(2026-2032 年)
 2026年全球內容行銷軟體市場報告2026年全球人工智慧內容行銷市場報告
 內容市場規模、佔有率和成長分析(按內容類型、內容格式、主要讀者、分發管道、最終用戶和地區分類)-2026-2033年產業預測
 內容行銷市場分析及預測(至2035年):按類型、產品類型、服務、技術、應用、部署類型、最終用戶、解決方案和模式分類內容行銷推廣服務市場:按服務類型、內容類型、組織規模和最終用戶分類 - 2026-2032 年全球預測