


 |
市場調查報告書
商品編碼
2118244
縮合試劑:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Condensation Reagents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年縮合試劑市值為 11.9 億美元,預計到 2031 年將達到 17.1 億美元,而 2026 年為 12.7 億美元,預測期(2026-2031 年)的複合年成長率為 6.13%。
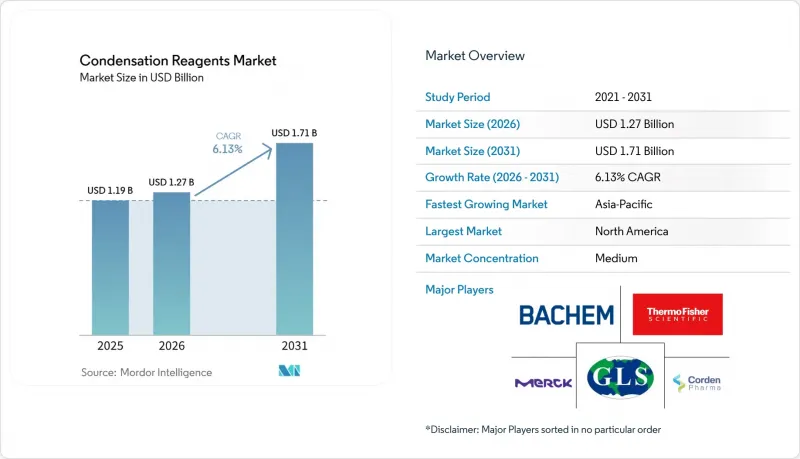
本報告按產品類型(碳二亞胺試劑、脲基試劑等)、形態(粉末、溶液、其他形態)、應用(胜肽合成、藥物原料藥(API)合成等)和地區(亞太地區、北美地區、歐洲地區及世界其他地區)進行細分。市場預測以美元(USD)為單位。
全球縮合試劑市場趨勢及洞察
對肽類藥物的需求日益成長
Glucagon-Like Peptide-1(GLP-1) 受體促效劑的核准和商業化規模擴張為縮合試劑市場奠定了堅實的基礎。 Bachem 公司於 2025 年投資 3.326 億瑞士法郎(約 4.1167 億美元),並於 2026 年 4 月在布本多夫啟用“K 號樓”,開始大規模生產胜肽類和寡核苷酸原料藥。該公司還計劃在 2026 年投入超過 4 億瑞士法郎(約 4.951 億美元)的資本支出,這表明其將持續擴大肽類產能,而非進行一次性投資。隨著胜肽鍊長度的增加,由於每增加一個結合循環,單位產量所需的試劑量也會增加,因此對試劑的需求激增。這一趨勢使得 GLP-1 的生產成為縮合試劑市場短期需求的主要驅動力。
擴大藥物原料藥合成與藥物發現活動
此外,原料藥生產外包給合約研發生產力機構(CDMO)的趨勢日益明顯,這些機構採購的標準化試劑數量也大幅增加,進而推動了縮合試劑市場的發展。 CordenPharma承諾到2027年,將在其胜肽平台投資超過10億歐元(約11.4億美元)。這其中包括位於待開發區工廠,該工廠的固相肽合成(SPPS)反應器產能超過5000公升;以及在科羅拉多的擴建計劃,旨在到2028年將該工廠的產能提升至超過42000公升。隨著供應商從品牌藥廠轉向採用標準化商業流程的專業生產商,這種轉變正在擴大終端用戶群。此外,基於ICH Q11和Q7的原料藥品質要求提高了試劑供應商的文件標準,增強了認證供應商的地位,並降低了低規格產品的市場競爭力。因此,與以往研發主導的採購模式相比,市場需求更大、更具可重複性,且對品質的要求也更高。
先進縮合試劑高成本
先進的偶聯劑價格仍然昂貴,限制了縮合試劑市場的發展,使其僅限於對價格敏感的應用領域。 Springer 在 2025 年發表的一篇關於Liraglutide合成的論文指出,TBEC 是一種比 DIC 更安全、更環保的替代品,但同時也指出,這種新的合成路線的單位成本高於傳統的 DIC-oxima 組合。對於大規模生產的 GLP-1 生產商而言,這種成本差異並非主要問題,因為他們可以將昂貴試劑的成本分攤到大規模批量商業生產中。然而,對於預算緊張的中小型生物技術公司、學術研究機構以及學名藥活性成分 (API) 的用戶來說,這卻是一個更大的限制因素。儘管高階藥物的需求依然強勁,但這種成本差異正在抑制中階市場的需求。
細分市場分析
預計到2025年,碳二亞胺類試劑將佔據縮合試劑市場32.48%的佔有率,憑藉其成本效益和廣泛的合成應用,繼續保持最大產品系列的地位。 DIC、DCC和EDC已廣泛應用於科學研究、臨床和商業領域的標準固相胜肽合成(SPPS)和液相合成製程。這些試劑的使用者群體依然龐大,因為許多用戶看重其操作簡單、基材相容性廣以及相比新型系統更低的成本。此外,基於脲鎓的試劑在需要快速偶聯和控制外消旋的複雜合成序列中也持續發揮關鍵作用。
磷酸酐類試劑預計到2031年將以7.23%的複合年成長率成長,成為縮合試劑市場中成長最快的產品類別。丙基膦酸酐(T3P)因其能夠生成水溶性副產物、簡化後後處理以及支援大規模環保製程設計,正在不斷擴大市場佔有率。 2026年發表於《有機化學快報》(Organic Letters)的一篇報告展示了使用T3P的環三葉草輔助液相肽合成(LPPS)的商業性效用,結果顯示在溫和條件下即可獲得高分離產率。手性消旋抑制劑和羰基活化劑雖然仍是小規模產品,但它們在立體選擇性藥物合成、寡核苷酸組裝和生物結合等工作流程中正滿足日益成長的需求。
區域分析
2025年,北美佔據縮合試劑市場41.27%的佔有率,成為最大的區域市場。該地區受惠於叢集創新製藥公司、大規模的合約研發產量機構(CDMO)以及從早期研發到商業化生產都需要試劑的研究機構。美國仍然是主要的需求中心,而加拿大則透過其生物技術活動和研究能力為市場做出貢獻。 2026年3月,CordenPharma和BioMed Realty在博爾德擴建了其胜肽開發實驗室,該實驗室毗鄰其現有的大型胜肽製造地。這顯示北美胜肽相關基礎設施正在持續擴張。
預計到2031年,亞太地區將以7.35%的複合年成長率成長,成為縮合試劑市場成長最快的地區。印度在這一成長中佔了很大佔有率,這得益於政府的原料藥生產連結獎勵計畫計劃(PLI)。該計劃已於2025年12月前使28種關鍵產品的38個項目投入運作。該計劃已建立了每年56,800噸的國內產能,並為原料藥(原料藥)的合成原料提供了更廣泛的本地基礎。中國、日本和韓國製造業的持續擴張進一步推動了該地區的成長勢頭,亞太地區在需求成長和供應鏈能力方面繼續佔據重要地位。日本仍然是一個技術要求高、合規性要求高的市場,這支撐了對高品質試劑的需求。
歐洲在縮合試劑市場中仍是一個規模龐大且技術要求極高的地區,其中德國、法國和英國佔據該地區最大的國內市場。德國憑藉在精細化學品和特種化學品領域的雄厚實力,支撐著國內產能和特種試劑的供應。瑞士也是一個值得關注的市場。 Bakem公司正在瑞士擴建其工業胜肽和寡核苷酸的基礎設施,計劃在2026年投資超過4億瑞士法郎(約4.951億美元)。 「世界其他地區」的絕對規模仍然較小,但南美和中東部分地區的早期藥物研發正在為未來的需求奠定一定的基礎。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對胜肽和寡核苷酸合成的需求日益成長
- 擴大藥品原料藥(API)的生產活動
- 高效縮合化學的廣泛應用
- 合約研發生產機構(CDMO)的擴張
- 對特種化學品和精細化學品的需求不斷成長
- 市場限制因素
- 先進縮合試劑高成本
- 危險試劑的安全與操作注意事項
- 存在其他催化和酶促合成途徑。
- 價值和供應鏈分析
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 碳二亞胺試劑
- 鈾基試劑
- 基於鏻的試劑
- 磷酸酐試劑
- 羰基活化試劑
- 手性消旋抑制劑
- 其他縮合試劑
- 按形式
- 粉末
- 液體
- 其他形式
- 透過使用
- 胜肽合成
- 原料藥(API)的合成
- 有機合成
- 寡核苷酸合成
- 生物結合
- 農藥合成
- 特種化學品和精細化學品的合成
- 聚合物/材料化學
- 其他用途
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 世界其他地區
- 南美洲
- 中東和非洲
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- AAPPTec
- AnaSpec, Inc.
- Bachem Inc.
- Biosolve Chimie
- BLD Pharmatech Ltd.
- Canpeptide Inc.
- Carl Roth GmbH+Co. KG
- Chem-Impex International
- CordenPharma
- CS Bio Co.
- Enamine Ltd.
- Fluorochem Ltd.
- FUJIFILM Wako Pure Chemical Corporation
- GL Biochem(Shanghai)Ltd.
- IRIS Biotech GmbH
- Luxembourg Bio Technologies Ltd.
- Merck KGaA
- Suzhou Highfine Biotech Co., Ltd.
- Thermo Fisher Scientific Inc.
- Tokyo Chemical Industry Co., Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the condensation reagents market size was valued at USD 1.19 billion in 2025 and is estimated to grow from USD 1.27 billion in 2026 to reach USD 1.71 billion by 2031, at a CAGR of 6.13% during the forecast period (2026-2031).
This report is Segmented by Product Type (Carbodiimide Reagents, Uronium-Based Reagents, and More), Physical Form (Powder, Solution, and Other Forms), Application (Peptide Synthesis, Pharmaceutical API Synthesis, and More), and Geography (Asia-Pacific, North America, Europe, and Rest of the World). The Market Forecasts are Provided in Terms of Value (USD).
Global Condensation Reagents Market Trends and Insights
Rising Demand for Peptide-Based Therapeutics
The approval and commercial scale-up of Glucagon-like peptide-1 (GLP-1) receptor agonists has created a strong base for the condensation reagents market. Bachem invested CHF 332.6 million (~USD 411.67 million) in 2025 and opened Building K in Bubendorf in April 2026 for industrial-scale peptide and oligonucleotide API manufacturing. The company also planned capital expenditure (CAPEX) of more than CHF 400 million (~USD 495.10 million) for 2026, indicating continued expansion of peptide capacity rather than a one-time investment. Reagent demand rises sharply as peptide chains become longer, because each additional coupling cycle increases consumption per unit of output. This dynamic makes GLP-1 manufacturing a key near-term demand driver in the condensation reagents market.
Increasing Pharmaceutical API Synthesis and Drug Development Activity
The condensation reagents market is also benefiting from the broader outsourcing of API manufacturing to CDMOs, which are purchasing larger, more standardized reagent volumes. CordenPharma committed more than EUR 1 billion (~USD 1.14 billion) to its peptide platform through 2027, including a greenfield facility in Muttenz with more than 5,000 L of SPPS reactor capacity and a Colorado expansion planned to push the site beyond 42,000 L by 2028. This shift broadens the end-user base, as procurement moves away from branded drug developers and toward specialist manufacturers running standardized commercial workflows. API quality requirements under ICH Q11 and Q7 also raise documentation standards for reagent suppliers, strengthening certified suppliers and reducing the viability of lower-specification offerings. The result is a demand profile that is larger, more repeatable, and more quality-sensitive than earlier research-driven purchasing patterns.
High Cost of Advanced Condensation Reagents
Advanced coupling agents remain costly, limiting the expansion of the condensation reagents market into price-sensitive applications. A 2025 Springer paper on liraglutide synthesis described TBEC as a safer and greener substitute for DIC, while noting that the newer route carried a higher unit cost than conventional DIC and Oxyma combinations. That cost gap is less significant for high-volume GLP-1 producers, as they can spread premium reagent costs across large commercial batches. However, it is a more significant constraint for smaller biotechs, academic groups, and generic Active Pharmaceutical Ingredient (API) users operating under tighter budget constraints. This divide suppresses mid-market demand even as premium pharmaceutical demand remains strong.
Other drivers and restraints analyzed in the detailed report include:
- Growing Adoption of High-Throughput and Automated Synthesis
- Expansion of CDMOs and Specialty Chemical Manufacturing
- Safety and Handling Challenges
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Carbodiimide reagents held 32.48% of the condensation reagents market share in 2025, maintaining their position as the largest product group due to cost efficiency and broad synthetic utility. DIC, DCC, and EDC remain deeply embedded in standard solid-phase peptide synthesis (SPPS) and solution-phase workflows across research, clinical, and commercial settings. Their installed base remains large because many users value familiar handling, broad substrate compatibility, and lower cost compared to newer systems. Uronium-based reagents also retain a meaningful role in demanding sequences where fast coupling and racemization control are important.
Phosphonic anhydride reagents are forecast to grow at a 7.23% CAGR through 2031, making them the fastest-growing product group in the condensation reagents market. Propylphosphonic anhydride (T3P) has gained ground because it generates water-soluble byproducts, simplifies workup, and supports greener process design at scale. Organic Letters reported in 2026 that Cyclover-assisted liquid-phase peptide synthesis (LPPS) using T3P demonstrated commercial relevance under mild conditions with strong isolated yields. Chiral racemization inhibitors and carbonyl activation reagents remain smaller categories, but they serve growing needs in stereoselective pharmaceutical synthesis, oligonucleotide assembly, and bioconjugation workflows.
Complete Report Scope:
- By Product Type
- Carbodiimide Reagents
- Uronium-Based Reagents
- Phosphonium-Based Reagents
- Phosphonic Anhydride Reagents
- Carbonyl Activation Reagents
- Chiral Racemization Inhibitors
- Other Condensation Reagents
- By Physical Form
- Powder
- Solution
- Other Forms
- By Application
- Peptide Synthesis
- Pharmaceutical API Synthesis
- Organic Synthesis
- Oligonucleotide Synthesis
- Bioconjugation
- Agrochemical Synthesis
- Specialty and Fine Chemical Synthesis
- Polymer and Materials Chemistry
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Rest of the World
- South America
- Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America held 41.27% of the condensation reagents market share in 2025, making it the largest regional contributor. The region benefits from a dense cluster of innovator drug companies, a large base of contract development and manufacturing organizations (CDMOs), and research institutions that consume reagents from early development through commercial production. The United States remains the core demand center, while Canada contributes through its biotech activity and research capacity. In March 2026, CordenPharma and BioMed Realty expanded a peptide development laboratory in Boulder, adjacent to an existing large-scale peptide manufacturing site, indicating that North American peptide infrastructure continues to expand.
Asia-Pacific is projected to grow at a 7.35% CAGR through 2031, making it the fastest-growing geography in the condensation reagents market. India represents a significant part of that growth, supported by the government's bulk drug production-linked incentive (PLI) scheme, which commissioned 38 projects across 28 critical products by December 2025. The same program established 56,800 t per annum of domestic capacity, supporting a broader local base for API-oriented synthesis inputs. Regional momentum is further driven by ongoing manufacturing expansion across China, Japan, and South Korea, keeping Asia-Pacific relevant for both demand growth and supply positioning. Japan remains a technically demanding market where high compliance expectations support demand for premium reagent grades.
Europe remains a sizeable and technically demanding part of the condensation reagents market, with Germany, France, and the United Kingdom representing the largest national markets in the region. Germany benefits from a strong base in fine and specialty chemicals, which supports domestic production capabilities and specialist reagent supply. Switzerland is also notable, as Bachem is expanding its industrial peptide and oligonucleotide infrastructure there, with planned capital expenditure of more than CHF 400 million (~USD 495.10 million) for 2026. The Rest of the World remains smaller in absolute size, but early pharmaceutical development in parts of South America and the Middle-East is creating a modest base for future demand.
- AAPPTec
- AnaSpec, Inc.
- Bachem Inc.
- Biosolve Chimie
- BLD Pharmatech Ltd.
- Canpeptide Inc.
- Carl Roth GmbH + Co. KG
- Chem-Impex International
- CordenPharma
- CS Bio Co.
- Enamine Ltd.
- Fluorochem Ltd.
- FUJIFILM Wako Pure Chemical Corporation
- GL Biochem (Shanghai) Ltd.
- IRIS Biotech GmbH
- Luxembourg Bio Technologies Ltd.
- Merck KGaA
- Suzhou Highfine Biotech Co., Ltd.
- Thermo Fisher Scientific Inc.
- Tokyo Chemical Industry Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Peptide and Oligonucleotide Synthesis
- 4.2.2 Increasing Pharmaceutical API Manufacturing Activities
- 4.2.3 Growing Adoption of High-Efficiency Condensation Chemistry
- 4.2.4 Expansion of Contract Development and Manufacturing Organizations
- 4.2.5 Rising Demand for Specialty and Fine Chemicals
- 4.3 Market Restraints
- 4.3.1 High Cost of Advanced Condensation Reagents
- 4.3.2 Safety and Handling Concerns for Hazardous Reagents
- 4.3.3 Availability of Alternative Catalytic and Enzymatic Synthesis Routes
- 4.4 Value and Supply Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Carbodiimide Reagents
- 5.1.2 Uronium-Based Reagents
- 5.1.3 Phosphonium-Based Reagents
- 5.1.4 Phosphonic Anhydride Reagents
- 5.1.5 Carbonyl Activation Reagents
- 5.1.6 Chiral Racemization Inhibitors
- 5.1.7 Other Condensation Reagents
- 5.2 By Physical Form
- 5.2.1 Powder
- 5.2.2 Solution
- 5.2.3 Other Forms
- 5.3 By Application
- 5.3.1 Peptide Synthesis
- 5.3.2 Pharmaceutical API Synthesis
- 5.3.3 Organic Synthesis
- 5.3.4 Oligonucleotide Synthesis
- 5.3.5 Bioconjugation
- 5.3.6 Agrochemical Synthesis
- 5.3.7 Specialty and Fine Chemical Synthesis
- 5.3.8 Polymer and Materials Chemistry
- 5.3.9 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 Rest of the World
- 5.4.4.1 South America
- 5.4.4.2 Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 AAPPTec
- 6.4.2 AnaSpec, Inc.
- 6.4.3 Bachem Inc.
- 6.4.4 Biosolve Chimie
- 6.4.5 BLD Pharmatech Ltd.
- 6.4.6 Canpeptide Inc.
- 6.4.7 Carl Roth GmbH + Co. KG
- 6.4.8 Chem-Impex International
- 6.4.9 CordenPharma
- 6.4.10 CS Bio Co.
- 6.4.11 Enamine Ltd.
- 6.4.12 Fluorochem Ltd.
- 6.4.13 FUJIFILM Wako Pure Chemical Corporation
- 6.4.14 GL Biochem (Shanghai) Ltd.
- 6.4.15 IRIS Biotech GmbH
- 6.4.16 Luxembourg Bio Technologies Ltd.
- 6.4.17 Merck KGaA
- 6.4.18 Suzhou Highfine Biotech Co., Ltd.
- 6.4.19 Thermo Fisher Scientific Inc.
- 6.4.20 Tokyo Chemical Industry Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

 2026-2034年全球農業化學合成用苯胺和對硝基苯酚市場規模、佔有率、趨勢和成長分析報告
 手性消旋化抑制劑:市佔率分析、產業趨勢與統計及成長預測(2026-2031)T3P:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026年N-(正丙基)硫代磷醯三醯胺(NTTP)尿素酶抑制劑全球市場報告
 苯胺及對硝基苯酚在農藥合成的應用:市場機會、成長要素、產業趨勢分析及2026-2035年預測
 2026年全球4-(2-丙炔-1-基)嗎啉市場研究報告
 高利潤醫藥中間體市場預測——按產品類型、治療應用、合成流程、最終用戶和地區分類的全球分析——2034年
 疊氮乙酯市場規模、佔有率和成長分析:按純度、合成方法、包裝、應用、分銷通路、終端用戶產業和地區分類-2026-2033年產業預測
 陶瓷助劑市場規模、佔有率和成長分析:按產品類型、應用、最終用戶、配方類型、地區和產業預測,2026-2033年
 肥料添加劑市場規模、佔有率和成長分析:按肥料類型、配方、應用、通路和地區分類-2026-2033年產業預測