


 |
市場調查報告書
商品編碼
2116778
中東和非洲離心式幫浦:市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)Middle East And Africa Centrifugal Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
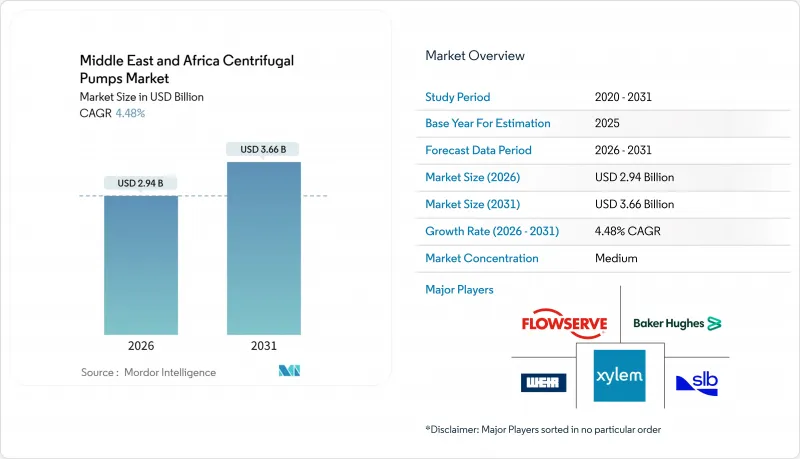
根據 Mordor Intelligence 預測,中東和非洲的離心式幫浦市場規模預計將在 2026 年達到 29.4 億美元,到 2031 年達到 36.6 億美元,預測期內的複合年成長率為 4.48%。
本報告按流動類型(軸流式、徑流式、混流式)、級數(單級、多級)、終端用戶行業(石油天然氣、電力等)、流量範圍(微型(小於 500 Gpm)、小型(500–1,000 Gpm)、材質(1,000–5,000 Gpm)、其他地區性鑄鐵市場預測以美元(USD)計價。
中東及非洲離心式幫浦市場趨勢及洞察
工業化和都市化的快速發展
海灣合作理事會(GCC)89%的人口已居住在都市區,如此高的人口密度迫使市政當局每年安裝約12,000至15,000套新的飲用水、污水處理和消防系統。沙烏地阿拉伯的NEOM和埃及的「新行政首都」等大型企劃正在採用額定流量超過3,000加侖/分鐘的高效離心式幫浦,用於海水淡化和供水迴路。區域冷卻、深層地下室排水和符合NFPA-20標準的消防系統也進一步刺激了對離心泵的需求。設計人員擴大指定使用變速驅動裝置和耐腐蝕合金,以控制能耗並應對高氯化物濃度。總而言之,這些城市建設項目構成了持續訂單的長期儲備,支撐著中東和非洲離心式幫浦市場在基本負載基礎設施和輔助服務方面的需求。
加大對都市污水處理的投資
沙烏地阿拉伯國家水務局正投資210億美元,計畫在2030年將其污水處理能力提升至每日820萬立方公尺。科威特耗資24億美元的斯利比亞水質淨化廠維修計畫和南非耗資32億美元的豪登省水質淨化廠維修項目,都體現了全部區域對更高污水處理標準的持續追求。目前的項目傾向於採用膜生物反應器(MBR)和逆滲透(RO)終處理流程,這兩種工藝都需要低脈動、耐磨損的離心式幫浦,且泵的濕部件採用不銹鋼或雙相不銹鋼材質。變頻驅動裝置已成為標準配置,可在滿足ISO 50001要求的同時,降低20-30%的能耗。隨著供水事業加快70%水資源再利用率的目標,中東和非洲離心式幫浦市場的長期營運維護合約需求不斷成長,從而提高了單台離心泵的終身收益。
深井安裝中的空化與啟動問題
在沙烏地阿拉伯的化石含水層地區,當靜水頭超過300公尺時,吸入壓力會下降,導致氣泡形成並侵蝕葉輪,六個月內效率降低高達25%。阿拉伯聯合大公國艾因的油井也出現了類似問題,需要進行維修,例如安裝變頻驅動裝置和真空引水系統,每個井場額外花費8000至12000美元。在臥式消防水泵中,吸入管內的殘留空氣會阻礙水泵達到啟動目標,進而影響其是否符合美國國家消防協會(NFPA)標準。雖然自吸式設計和狀態監測可以將故障率降低一半,但額外的資本投入需求正在減緩預算有限的營運商採用這些技術的速度,並削弱中東和非洲的離心式幫浦市場。
細分市場分析
到2025年,輻流泵將在中東和非洲的離心式幫浦市場佔據54.67%的佔有率。這主要得益於城市供水管網和暖通空調冷卻迴路的強勁需求,這些應用場景的揚程很少超過150英尺。徑流泵水力特性簡單、供應商眾多且與變速驅動裝置相容,這些因素增強了採購信心。同時,混流泵浦預計到2031年將以5.07%的複合年成長率成長,因為礦業公司正在對含固態為20%至30%的礦漿迴路維修,採用混合式葉輪,且不影響效率。剛果民主共和國卡莫阿卡庫拉礦的擴建計畫便是這項轉變的例證,該計畫採用了數十台混流泵進行尾礦排放。
這種設計由於其較低的前吸揚程要求,使得新建泵站的鑽井深度可以更淺,這在地下水位較淺的非洲地區尤其重要。福斯公司於2024年推出的半開式葉輪進一步將維修週期延長至六個月。在高壓海水淡化領域,徑流泵仍佔主導地位,在1000 psi的壓力下效率可超過80%。同時,軸流泵浦繼續應用於埃及尼羅河Delta的防洪工程(流量超過50000 gpm)以及沙烏地阿拉伯的椰棗灌溉工程。這些趨勢共同造就了中東和非洲地區平衡且不斷發展的離心式幫浦市場,其中混流技術正在開闢一個快速成長且利潤豐厚的細分市場。
至2025年,單級離心泵將佔離心式幫浦市場62.31%的佔有率。這是因為其結構簡單,適用於建築設備和供水事業的大多數應用。然而,多級離心幫浦市場正以4.86%的複合年成長率持續成長,這主要得益於沙烏地阿拉伯傑夫拉油田的推動。該油田使用18級筒式泵浦以8000 psi的壓力交替注入水和氣體。另一個成長領域是6至8級海水淡化泵,它們以1200 psi的壓力向膜分離器供水。
蘇爾壽的「HiFlux」擴散器可將級間損失降低12%,使連續運轉裝置的投資回報期縮短至兩年以內。然而,當泵浦的級數超過10級時,轉子的動態特性變得更加複雜,迫使原始設備製造商(OEM)進行有限元素檢驗和現場動平衡。單級泵浦在符合NFPA-20標準的消防系統中仍佔據主導地位,但高層建築高度的不斷增加可能會導致對能夠將揚程維持在額定流量150%的兩級分離式泵浦的需求增加。目前,中東和非洲的離心式幫浦市場在成熟的單級幫浦銷售量和高價值多級幫浦的價值成長之間保持平衡。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 工業化和都市化的快速發展
- 加大對都市污水處理的投資
- 海灣國家海水淡化工程擴建
- 加速非洲銅帶採礦計畫建設
- 政府主導的石油和天然氣產能擴張
- 泵浦部件的區域製造激勵措施
- 市場限制因素
- 深井安裝中的空化與啟動問題
- 與酸性原油的化學相容性有限
- 不銹鋼和合金原料價格波動
- 仿冒零件的持續供應鏈
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按流量類型
- 軸流式
- 徑向
- 混合物
- 依階段數
- 單級
- 多階段
- 按最終用戶行業分類
- 石油和天然氣
- 食品/飲料
- 水和污水處理
- 製藥
- 電力
- 建造
- 金屬和採礦
- 其他終端用戶產業
- 按生產能力範圍分類
- 微型(小於 500 加侖/分鐘)
- 小型(500-1,000 加侖/分鐘)
- 中等流量(1,000-5,000 加侖/分鐘)
- 大型(超過 5,000 加侖/分鐘)
- 材料
- 鑄鐵
- 不銹鋼
- 青銅
- 其他材料
- 按地區
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 中東
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Baker Hughes Company
- Ebara Pumps Middle East FZE
- Flowserve Corporation
- KSB Middle East FZE
- Ruhrpumpen Group
- Schlumberger Limited
- Parker Hannifin Corp
- The Weir Group plc
- Dover Corporation
- Xylem Inc
- Sulzer Ltd
- Grundfos Gulf Distribution
- Kirloskar Brothers Ltd
- Torishima Pump Mfg Co Ltd
- Pentair plc
- Wilo Middle East FZE
- Atlas Copco AB
- SPX FLOW Inc
- Tsurumi Manufacturing Co Ltd
- Franklin Electric Co Inc
第7章 市場機會與未來展望
According to Mordor Intelligence, the centrifugal pumps market size in the Middle East and Africa is USD 2.94 billion in 2026 and is projected to reach USD 3.66 billion by 2031, translating into a 4.48% CAGR through the forecast period.
This report is Segmented by Flow Type (Axial, Radial, Mixed), Number of Stages (Single Stage, and Multi Stage), End-User Industry (Oil and Gas, Power, and More), Capacity Range (Micro (Below 500 Gpm), Small (500-1, 000 Gpm), Medium (1, 000-5, 000 Gpm), and More), Material (Cast Iron, Stainless Steel, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Centrifugal Pumps Market Trends and Insights
Rapid Industrialization and Urbanization Uptick
Urban residents already make up 89% of the Gulf Cooperation Council population, a density that forces municipalities to commission new potable-water, sewage-treatment, and fire-protection assets at an estimated 12,000-15,000 units annually. Mega-projects such as NEOM in Saudi Arabia and Egypt's New Administrative Capital embed high-efficiency centrifugal pumps rated above 3,000 gpm in desalination and transmission loops. District cooling, deep-basement dewatering, and NFPA-20-compliant fire systems add further layers of demand. Designers are increasingly specifying variable-speed drives and corrosion-resistant alloys to manage energy use and chloride-rich conditions. Collectively, these city-building programs anchor a long pipeline of recurring orders that reinforce the Middle East And Africa centrifugal pumps market across both base-load infrastructure and auxiliary services.
Rising Investments in Urban Wastewater Treatment
Saudi Arabia's National Water Company is channeling USD 21 billion toward lifting wastewater throughput to 8.2 million m3/day by 2030. Kuwait's USD 2.4 billion Sulaibiya upgrade and South Africa's ZAR 3.2 billion Gauteng refurbishments underscore a region-wide shift toward higher treatment standards. Projects now favor membrane bioreactor or reverse-osmosis polishing, both of which demand low-pulsation, abrasion-resistant centrifugal pumps with stainless or duplex wetted parts. Variable-frequency drives are standard, cutting energy use 20%-30% while meeting ISO 50001 requirements. As utilities press to achieve 70% water reuse targets, the Middle East And Africa centrifugal pumps market gains exposure to long-term operations and maintenance contracts, enlarging lifetime revenue per installation.
Cavitation and Priming Failures in Deep-Well Installations
Static lifts above 300 m in Saudi fossil-aquifer zones produce low suction pressure, triggering vapor bubbles that erode impellers and trim efficiency by up to 25% within half a year. Similar issues in the UAE's Al Ain wells required retrofits involving variable-frequency drives and vacuum-priming systems, at an additional USD 8,000-12,000 per site. Horizontal fire-water pumps also miss start-up targets when air pockets linger in suction lines, compromising NFPA compliance. Although self-priming designs and condition monitoring can halve failure rates, the added capital outlay slows adoption among budget-strained operators and dilutes the momentum of the Middle East And Africa centrifugal pumps market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Desalination Projects in Gulf Countries
- Accelerated Mining Projects in Africa's Copper Belt
- Chemical Compatibility Limitations with Sour Crudes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Radial-flow pumps commanded 54.67% of the Middle East And Africa centrifugal pumps market in 2025, thanks to solid traction in municipal grids and HVAC cooling loops where heads rarely exceed 150 ft. Their straightforward hydraulics, broad supplier base, and compatibility with variable-speed drives reinforce procurement comfort. Mixed-flow configurations, however, are registering a 5.07% CAGR through 2031 as mining companies retrofit slurry circuits with hybrid impellers that tolerate 20%-30% solids without sacrificing efficiency. The Kamoa-Kakula expansion in the Democratic Republic of Congo typifies this pivot, specifying dozens of mixed-flow units for tailings discharge.
The design's lower net-positive suction head requirement reduces excavation depth in new pump-station builds, a critical advantage in Africa's shallow water tables. Flowserve's 2024 release of a semi-open impeller further lengthens maintenance intervals to six months. Radial pumps retain dominance in high-pressure desalination, achieving efficiencies above 80% at 1,000 psi, while axial-flow units continue to serve flood-control projects in Egypt's Nile Delta and Saudi date-palm irrigation where flows exceed 50,000 gpm. Collectively, these patterns sustain a balanced yet evolving Middle East And Africa centrifugal pumps market, in which mixed-flow technology is carving out a growing, high-margin niche.
Single-stage designs accounted for 62.31% of the centrifugal pump market in 2025 because their simplicity meets the majority of building-services and municipal-water applications. However, multi-stage models are advancing at a 4.86% CAGR, fueled by Saudi Arabia's Jafurah field, where 18-stage barrel pumps deliver 8,000 psi water-alternating-gas injection. Desalination's six- to eight-stage pumps feeding membranes at 1,200 psi represent another growth vein.
Sulzer's HiFlux diffuser reduced inter-stage losses by 12%, offering payback in less than two years for continuous-duty installations. Yet the rotor-dynamic complexity of more than 10 stages pushes OEMs to provide finite-element validation and field balancing. Single-stage pumps still dominate NFPA-20 fire systems, but rising skyscraper heights may tilt preferences toward twin-stage split-case units that maintain head at 150% rated capacity. For now, the Middle East And Africa centrifugal pumps market balances mature single-stage volumes with premium multi-stage value growth.
Complete Report Scope:
- By Flow Type
- Axial
- Radial
- Mixed
- By Number of Stages
- Single Stage
- Multi Stage
- By End-User Industry
- Oil and Gas
- Food and Beverages
- Water and Wastewater
- Pharmaceutical
- Power
- Construction
- Metal and Mining
- Other End-User Industries
- By Capacity Range
- Micro (Below 500 gpm)
- Small (500-1,000 gpm)
- Medium (1,000-5,000 gpm)
- Large (Above 5,000 gpm)
- By Material
- Cast Iron
- Stainless Steel
- Bronze
- Other Materials
- By Geography
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Baker Hughes Company
- Ebara Pumps Middle East FZE
- Flowserve Corporation
- KSB Middle East FZE
- Ruhrpumpen Group
- Schlumberger Limited
- Parker Hannifin Corp
- The Weir Group plc
- Dover Corporation
- Xylem Inc
- Sulzer Ltd
- Grundfos Gulf Distribution
- Kirloskar Brothers Ltd
- Torishima Pump Mfg Co Ltd
- Pentair plc
- Wilo Middle East FZE
- Atlas Copco AB
- SPX FLOW Inc
- Tsurumi Manufacturing Co Ltd
- Franklin Electric Co Inc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Industrialization and Urbanization Uptick
- 4.2.2 Rising Investments in Urban Wastewater Treatment
- 4.2.3 Expansion of Desalination Projects in Gulf Countries
- 4.2.4 Accelerated Mining Projects in Africa's Copper Belt
- 4.2.5 Government-Led Oil and Gas Capacity Upgrades
- 4.2.6 Local Manufacturing Incentives for Pump Components
- 4.3 Market Restraints
- 4.3.1 Cavitation and Priming Failures in Deep-Well Installations
- 4.3.2 Chemical Compatibility Limitations with Sour Crudes
- 4.3.3 Price Volatility of Stainless-Steel and Alloy Inputs
- 4.3.4 Persistent Counterfeit Spare-Parts Supply Chain
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Flow Type
- 5.1.1 Axial
- 5.1.2 Radial
- 5.1.3 Mixed
- 5.2 By Number of Stages
- 5.2.1 Single Stage
- 5.2.2 Multi Stage
- 5.3 By End-User Industry
- 5.3.1 Oil and Gas
- 5.3.2 Food and Beverages
- 5.3.3 Water and Wastewater
- 5.3.4 Pharmaceutical
- 5.3.5 Power
- 5.3.6 Construction
- 5.3.7 Metal and Mining
- 5.3.8 Other End-User Industries
- 5.4 By Capacity Range
- 5.4.1 Micro (Below 500 gpm)
- 5.4.2 Small (500-1,000 gpm)
- 5.4.3 Medium (1,000-5,000 gpm)
- 5.4.4 Large (Above 5,000 gpm)
- 5.5 By Material
- 5.5.1 Cast Iron
- 5.5.2 Stainless Steel
- 5.5.3 Bronze
- 5.5.4 Other Materials
- 5.6 By Geography
- 5.6.1 Middle East
- 5.6.1.1 Saudi Arabia
- 5.6.1.2 United Arab Emirates
- 5.6.1.3 Rest of Middle East
- 5.6.2 Africa
- 5.6.2.1 South Africa
- 5.6.2.2 Rest of Africa
- 5.6.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Baker Hughes Company
- 6.4.2 Ebara Pumps Middle East FZE
- 6.4.3 Flowserve Corporation
- 6.4.4 KSB Middle East FZE
- 6.4.5 Ruhrpumpen Group
- 6.4.6 Schlumberger Limited
- 6.4.7 Parker Hannifin Corp
- 6.4.8 The Weir Group plc
- 6.4.9 Dover Corporation
- 6.4.10 Xylem Inc
- 6.4.11 Sulzer Ltd
- 6.4.12 Grundfos Gulf Distribution
- 6.4.13 Kirloskar Brothers Ltd
- 6.4.14 Torishima Pump Mfg Co Ltd
- 6.4.15 Pentair plc
- 6.4.16 Wilo Middle East FZE
- 6.4.17 Atlas Copco AB
- 6.4.18 SPX FLOW Inc
- 6.4.19 Tsurumi Manufacturing Co Ltd
- 6.4.20 Franklin Electric Co Inc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 多級離心式幫浦:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 離心式幫浦市場預測至2034年—按類型、設計、材料、流量、最終用戶和地區分類的全球分析
 高溫離心式幫浦市場規模:按類型、應用、地區和預測。
 離心式幫浦市場:按泵浦類型、材質、流量、壓力範圍和最終用途產業分類-全球預測,2026-2032年離心式幫浦:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 離心式幫浦市場規模、佔有率、趨勢和預測:按葉輪類型、級數、流量類型、流量、最終用戶和地區分類,2026-2034年雙吸泵市場報告:按類型、材質、應用和地區分類(2026-2034 年)雙吸泵市場:2026-2032年全球市場預測(按泵浦設計、級數、葉輪材料、泵浦尺寸、驅動系統、軸承類型、安裝方向、銷售管道和最終用途產業分類)
 離心式幫浦市場:按產品類型、容量和地區分類長聯軸器離心式幫浦市場:按級數、流量、額定輸出、墊片類型、材質、應用、最終用途分類,全球預測(2026-2032年)