


 |
市場調查報告書
商品編碼
2116003
歐洲風機市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Europe Fans And Blowers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
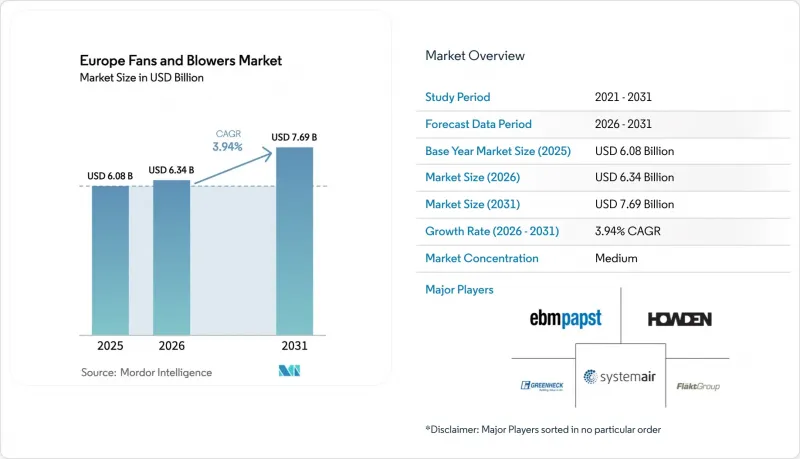
預計到 2026 年,歐洲風扇和鼓風機市場價值將達到 63.4 億美元,預計到 2031 年將達到 76.9 億美元,在預測期(2026-2031 年)內,複合年成長率將達到 3.94%。
本報告按技術(離心式、軸流式及其他)、壓力範圍(低壓、中壓和高壓)、最終用途行業(工業和商業)以及地區(德國、英國、法國、義大利、西班牙、北歐國家、荷蘭和其他歐洲國家)進行細分。市場規模和預測均以美元計價。
歐洲風扇和鼓風機市場的趨勢和洞察
歐盟關於風扇系統的生態設計能源效率法規
歐盟委員會第2024/1834號條例將於2026年7月起實施具有法律約束力的最低能源效率標準,取代現有的自願性措施。該條例適用於功率範圍為125瓦至500千瓦的風機,並將立即禁止在大多數商業暖通空調和輕工業領域使用單速交流感應電動機。德國聯邦經濟事務部預測,到2030年,歐盟的電力消耗量將減少8太瓦時,大致相當於中型燃煤發電廠的發電量。製造商將獲得分階段過渡期,第一階段於2026年實施,第二階段於2029年實施。這將有助於緩解模具成本的急劇上升,同時縮短已安裝設備的更換週期。承包商已開始建立符合監管要求的庫存,Systemair在2025/26會計年度第二季度西歐地區的有機銷售額成長11.1%便印證了這一點。因此,這些法規加快了維修預算的製定,導致對配備 EC 馬達且能夠輕鬆滿足新性能標準的軸流風扇的需求增加。
歐洲資料中心容量快速擴張
到2024年,超大規模資料中心和託管營運商將擁有742兆瓦的運作裝置容量,另有1.7吉瓦正在建設中,還有2.5吉瓦處於規劃階段。隨著亞馬遜網路服務(AWS)決定投資157億歐元建造其阿拉貢園區,西班牙正崛起為重要的資料中心樞紐。法蘭克福和倫敦兩地合計擁有超過1.7吉瓦的運作中裝置容量,且這兩個市場均擁有超過500兆瓦的在建項目。機架密度已從2020年的8千瓦上升到人工智慧工作負載的15千瓦以上,這迫使營運商採用能夠即時調節氣流並滿足嚴格噪音法規的低壓軸流風機陣列。德國《建築能源法》第71a條規定,超過290千瓦的暖通空調系統必須進行數位監控,進一步推動了買家轉向支援物聯網的風扇平台。
鋼鐵和鋁價的波動推高了物料清單成本。
2024年,受能源成本和反傾銷措施的影響,西北歐熱軋鋼卷在每噸550歐元至720歐元之間波動,較上一季波動幅度達15%。由於冶煉廠為應對飆升的電價而減產,鋁坯價格在每噸2,400美元至2,800美元之間波動。離心風機的風機殼體、葉輪和馬達框架佔單價的45%之多,固定價格合約和不斷上漲的原物料價格疊加,使供應商面臨巨大風險。由於傳統定價方式無法消化不斷上漲的投入成本,EBM-Papst公司2024/25會計年度的銷售額下降了13.1%。儘管預計隨著建設業的逐步復甦,鋼鐵需求將在2026年趨於穩定,但在碳邊境調節機制全面實施之前,鋁價可能仍將保持波動。
細分市場分析
到2025年,離心風機的銷售額將佔總銷售額的60.1%,主要得益於製程工業對物料輸送和熱控制等高靜壓(超過70 kPa)的需求。同時,軸流風機的年複合成長率(CAGR)為4.9%。這主要歸功於EC馬達與單速感應馬達相比,能耗降低高達70%,並符合2026年生效的生態設計標準。在歐洲風機和鼓風機市場,軸流風機產品在資料中心冷卻和商業暖通空調維修領域的市場規模成長最為迅速,在這些領域,面積、噪音和變速性能比峰值壓力要求更為重要。
離心式通風技術預計將在中高壓領域保持強勁地位,因為其後彎式徑向葉片能夠處理含有顆粒物和腐蝕性氣體的氣流。然而,在目前佔總需求55.5%的低壓通風領域,由建築管理軟體控制的軸流式通風系統正逐漸佔據主導地位,離心式通風技術在15 kPa以下壓力範圍內的佔有率正逐步下降。這一趨勢與資料中心和辦公大樓維修中廣泛採用分散式通風系統的趨勢相吻合,傳統的集中式高靜壓通風系統被可逐機架擴展的模組化風扇牆所取代。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟基於生態設計的風扇系統能源效率需求
- 商業不動產暖通空調系統的綠建築維修
- 食品飲料和製藥業對衛生空調的需求日益成長。
- 歐洲資料中心容量快速擴張
- 採用積層製造流程設計葉輪有助於縮短更換週期。
- 整合物聯網感測器以實現預測性維護
- 市場限制因素
- 由於鋼鐵和鋁價波動,物料清單成本正在上升。
- 來自亞洲的低價進口商品帶來的價格壓力
- 都市區的噪音排放法規限制了大型風扇的安裝。
- 高效率馬達用稀土元素磁鐵的供應風險
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 透過技術
- 離心式
- 軸
- 其他
- 按壓力範圍
- 低壓(低於 15 kPa)
- 中壓(15-70 kPa)
- 高(70 kPa 或更高)
- 按最終用途類別
- 產業
- 發電
- 石油和天然氣
- 鋼
- 化工/石油化工
- 採礦和金屬
- 建築與水泥
- 暖通空調及無塵室
- 其他
- 商業
- 產業
- 按地區
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 北歐國家
- 荷蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- ebm-papst Group
- Howden Group Ltd
- FlaktGroup Holding GmbH
- Systemair AB
- Greenheck Fan Corp.
- Trane Technologies plc
- Halifax Fan Ltd
- Rosenberg Ventilatoren GmbH
- Ventilatorenfabrik Oelde GmbH
- Continental Blower LLC
- CG Power & Industrial Solutions Ltd
- Loren Cook Company
- Pollrich DLK Fan Factories GmbH
- Aerzener Maschinenfabrik GmbH
- CBI Europe SpA
- Comefri Group
- VTS Group
- Soler & Palau Ventilation Group
- Nadi Airtechnics Pvt Ltd
- Zhejiang Shangfeng Fan Co., Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe fans and blowers market size is estimated at USD 6.34 billion in 2026, and is expected to reach USD 7.69 billion by 2031, at a CAGR of 3.94% during the forecast period (2026-2031).
This report is Segmented by Technology (Centrifugal, Axial, and Others), Pressure Range (Low, Medium, and High), End-Use Sector (Industrial and Commercial), and Geography (Germany, United Kingdom, France, Italy, Spain, NORDIC Countries, Netherlands, and Rest of Europe). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Europe Fans And Blowers Market Trends and Insights
EU Ecodesign Energy-Efficiency Mandates for Fan Systems
Commission Regulation 2024/1834 replaces voluntary schemes with binding minimum energy-efficiency indexes from July 2026. The rule covers fans between 125 W and 500 kW, instantly outlawing single-speed AC induction motors in most commercial HVAC and light-industrial settings. Germany's economic ministry projects an 8 TWh cut in EU electricity use by 2030, roughly equal to the output of a mid-sized coal plant. Manufacturers gain a staggered path, Tier 1 in 2026 and Tier 2 in 2029, which softens tooling-cost shocks but shortens the replacement cycle for installed units. Contractors have begun stockpiling compliant inventory, as evidenced by Systemair's 11.1% organic sales jump in Western Europe during Q2 2025/26. The regulation, therefore, pulls forward retrofit budgets and lifts demand for EC-motor axial fans that comfortably meet the new index thresholds.
Rapid Capacity Build-Out of European Data Centers
Hyperscale and colocation operators commissioned 742 MW in 2024 and have 1.7 GW under construction, with a further 2.5 GW in planning. Spain has emerged as a hot spot after Amazon Web Services committed EUR 15.7 billion for its Aragon campus. Frankfurt and London jointly exceed 1.7 GW of live capacity, and both markets carry pipelines above 500 MW. Rack densities are climbing from 8 kW in 2020 to 15 kW and higher for AI workloads, forcing operators to specify low-pressure axial arrays that modulate airflow in real time and meet stringent acoustic rules. Germany's Section 71a of the Building Energy Act requires digital monitoring for HVAC systems above 290 kW, further steering buyers toward IoT-ready fan platforms.
Volatile Steel & Aluminum Prices Inflating BOM Costs
North-west European hot-rolled coil traded between EUR 550 and EUR 720 per t in 2024, with 15% quarter-on-quarter swings driven by energy costs and anti-dumping measures. Aluminum billet fluctuated between USD 2,400 and USD 2,800 per t as smelters curtailed output amid high electricity prices. Fan housings, impellers, and motor frames account for up to 45% of centrifugal unit cost, leaving suppliers exposed when fixed-price contracts collide with raw-material spikes. EBM-Papst's revenue fell 13.1% in fiscal 2024/25 as legacy quotes failed to absorb input-cost inflation. Steel demand is likely to stabilize alongside a mild construction rebound in 2026, yet aluminum volatility will linger until the Carbon Border Adjustment Mechanism reaches full force.
Other drivers and restraints analyzed in the detailed report include:
- HVAC Green-Building Retrofits in Commercial Real Estate
- Integration of IoT Sensors Enabling Predictive Maintenance
- Price Pressure from Low-Cost Asian Imports
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Centrifugal fans held 60.1% of 2025 revenue, underpinned by process industries that need high static pressures beyond 70 kPa for material handling and thermal control. Axial designs, however, are advancing at 4.9% CAGR because EC motors cut energy use by as much as 70% compared with single-speed induction units and meet Ecodesign thresholds coming into force in 2026. The Europe fans and blowers market size attached to axial products is expanding fastest within data-center cooling and commercial-HVAC retrofits, where footprint, noise, and variable-speed capability outweigh peak-pressure requirements.
Centrifugal technology will keep its foothold in medium- and high-pressure slots because backward-curved and radial wheels handle particulate-laden flows and corrosive gases. Yet low-pressure ventilation, currently 55.5% of total demand, now gravitates toward axial arrays controlled through building-management software, chipping away at centrifugal share below 15 kPa. The trend parallels a broader shift toward distributed air paths in data halls and office retrofits, replacing legacy high-static central plants with modular fan walls that scale rack by rack.
Complete Report Scope:
- By Technology
- Centrifugal
- Axial
- Others
- By Pressure Range
- Low (Below 15 kPa)
- Medium (15 to 70 kPa)
- High (Above 70 kPa)
- By End-use Sector
- Industrial
- Power Generation
- Oil and Gas
- Iron and Steel
- Chemical and Petrochemical
- Mining and Metals
- Construction and Cement
- HVAC and Cleanrooms
- Others
- Commercial
- Industrial
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- ebm-papst Group
- Howden Group Ltd
- FlaktGroup Holding GmbH
- Systemair AB
- Greenheck Fan Corp.
- Trane Technologies plc
- Halifax Fan Ltd
- Rosenberg Ventilatoren GmbH
- Ventilatorenfabrik Oelde GmbH
- Continental Blower LLC
- CG Power & Industrial Solutions Ltd
- Loren Cook Company
- Pollrich DLK Fan Factories GmbH
- Aerzener Maschinenfabrik GmbH
- CBI Europe S.p.A.
- Comefri Group
- VTS Group
- Soler & Palau Ventilation Group
- Nadi Airtechnics Pvt Ltd
- Zhejiang Shangfeng Fan Co., Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Ecodesign energy-efficiency mandates for fan systems
- 4.2.2 HVAC green-building retrofits in commercial real estate
- 4.2.3 Expansion of hygienic air-handling demand in F&B and pharma
- 4.2.4 Rapid capacity build-out of European data centers
- 4.2.5 Additive-manufactured impeller designs boosting replacement cycle
- 4.2.6 Integration of IoT sensors enabling predictive maintenance
- 4.3 Market Restraints
- 4.3.1 Volatile steel & aluminum prices inflating BOM costs
- 4.3.2 Price pressure from low-cost Asian imports
- 4.3.3 Urban noise-emission limits curbing large-fan installations
- 4.3.4 Supply risks for rare-earth magnets in high-efficiency motors
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products & Services
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Centrifugal
- 5.1.2 Axial
- 5.1.3 Others
- 5.2 By Pressure Range
- 5.2.1 Low (Below 15 kPa)
- 5.2.2 Medium (15 to 70 kPa)
- 5.2.3 High (Above 70 kPa)
- 5.3 By End-use Sector
- 5.3.1 Industrial
- 5.3.1.1 Power Generation
- 5.3.1.2 Oil and Gas
- 5.3.1.3 Iron and Steel
- 5.3.1.4 Chemical and Petrochemical
- 5.3.1.5 Mining and Metals
- 5.3.1.6 Construction and Cement
- 5.3.1.7 HVAC and Cleanrooms
- 5.3.1.8 Others
- 5.3.2 Commercial
- 5.3.1 Industrial
- 5.4 By Geography
- 5.4.1 Germany
- 5.4.2 United Kingdom
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 NORDIC Countries
- 5.4.7 Netherlands
- 5.4.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 ebm-papst Group
- 6.4.2 Howden Group Ltd
- 6.4.3 FlaktGroup Holding GmbH
- 6.4.4 Systemair AB
- 6.4.5 Greenheck Fan Corp.
- 6.4.6 Trane Technologies plc
- 6.4.7 Halifax Fan Ltd
- 6.4.8 Rosenberg Ventilatoren GmbH
- 6.4.9 Ventilatorenfabrik Oelde GmbH
- 6.4.10 Continental Blower LLC
- 6.4.11 CG Power & Industrial Solutions Ltd
- 6.4.12 Loren Cook Company
- 6.4.13 Pollrich DLK Fan Factories GmbH
- 6.4.14 Aerzener Maschinenfabrik GmbH
- 6.4.15 CBI Europe S.p.A.
- 6.4.16 Comefri Group
- 6.4.17 VTS Group
- 6.4.18 Soler & Palau Ventilation Group
- 6.4.19 Nadi Airtechnics Pvt Ltd
- 6.4.20 Zhejiang Shangfeng Fan Co., Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 工業和商業暖通空調應用風機:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)工業風扇:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 風扇和鼓風機市場規模、佔有率和成長分析:按產品類型、應用、最終用戶產業、額定功率、安裝類型、技術和地區分類-2026-2033年產業預測
 工業風機及鼓風機市場機會、成長促進因素、產業趨勢分析及2026-2035年預測
 2026-2034年全球風扇和鼓風機市場規模、佔有率、趨勢和成長分析報告
 個人風扇市場規模、佔有率和成長分析:按產品類型、電源、葉片配置、價格範圍、銷售管道和地區分類-2026-2033年產業預測
 工業及商業風機及鼓風機市場:依風機類型、壓力類型、技術、終端用戶產業及通路分類-2026-2032年全球市場預測靜電放電風扇市場:依產品類型、技術、電源、應用和最終用戶分類,全球預測,2026-2032年工業交流風扇市場:按產品類型、風量、安裝方式、馬達類型、最終用途產業和應用分類-全球預測,2026-2032年靜電消除風扇市場:按類型、應用、最終用戶和分銷管道分類,全球預測,2026-2032年