


 |
市場調查報告書
商品編碼
2115222
非洲柴油發電機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Africa Diesel Generator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
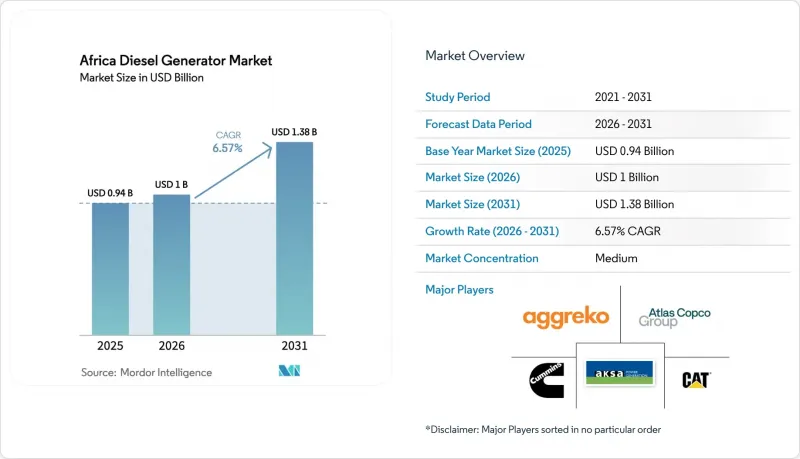
據 Mordor Intelligence 稱,非洲柴油發電機市場預計到 2026 年價值將達到 10 億美元,高於 2025 年的 9.4 億美元,預計到 2031 年將達到 13.8 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 6.57%。
本報告按容量(75kVA 以下、75-375kVA、375-750kVA、750-2,000kVA、2,000kVA 以上)、應用(備用/後備電源、主用/連續電源、尖峰用電調節/負載管理)、最終用戶(住宅、商業、工業)及
非洲柴油發電機市場趨勢與洞察
撒哈拉以南非洲地區停電頻率增加
電力系統持續低迷的可靠性正在推動非洲各地對柴油發電機的需求,預計2024年,34個國家平均每月將停電56小時。在奈及利亞,今年上半年電網就停電了12次,迫使工業用戶將發電機作為主電源運作,加速了發電機的磨損,縮短了更換週期。在肯亞,電氣化進程已使120萬戶家庭接入電網,但電壓波動仍普遍存在,促使郊區居民安裝小型柴油發電機。在南非,六級限電措施持續了118天,迫使醫院、資料中心和工廠部署可提供8至12小時自主運作的永久性備用電源系統。資金短缺的電力公司正在推遲電網升級,預計這種惡性循環將確保在未來十年內,柴油發電機仍將是應對供電風險的主要保障。
奈及利亞、肯亞和南非的資料中心容量迅速擴張
超大規模資料中心和託管業者在2024年運作了12個Tier III和Tier IV等級的設施。每個設施需要2-10兆瓦的N+1或2N柴油冗餘備援。Caterpillar於2024年加入非洲資料中心協會,顯示原始設備製造商(OEM)對雲端服務供應商充滿信心,認為在缺乏天然氣基礎設施的地區,柴油是最可靠的備用電源選擇。微軟和Equinix宣佈在南非和肯亞建造新的園區,理由是需要低延遲和有利的電力採購結構,將電網供電與現場柴油發電結合。 Uptime Institute的法規要求同時維護,這實際上要求配備能夠在10秒內黑啟動的高規格柴油發電機組。儘管營運商正在探索電池供電的緊急方案,但在兆瓦級備用電源方面,柴油仍保持著5-7年的優勢,鞏固了其在非洲柴油發電機市場的核心地位。
太陽能+電池混合動力系統價格平價加速實現
在陽光充足的非洲,配備四小時鋰離子電池儲能系統的公用事業規模太陽能發電系統,目前供電成本為每千瓦時0.15至0.18美元,低於柴油發電機連續運行期間每千瓦時0.22至0.28美元的營運成本。馬拉威計畫於2024年以電網級電池儲能系統取代Aggreco公司的柴油發電機租賃業務,這項決定凸顯了經濟模式的轉變,也為非洲柴油發電機市場的租賃業者敲響了警鐘。對於年運作時間不超過500小時的備用電源應用,能夠自主運作六小時的太陽能和電池系統的總擁有成本(TCO)已經高於柴油發電機,這可能會威脅到未來的替換需求。
細分市場分析
2025年,75kVA以下的發電機銷售佔總銷售量的44.02%。這反映了都市區家庭、街頭商店和電信基地台等場所的大規模部署需求,這些場所需要在大規模停電期間配備10-50kW的備用電源。該市場高度分散,主要由中國和印度品牌主導,它們在初始價格上競爭。 2025年,75-375kVA範圍內的發電機約佔非洲柴油發電機市場佔有率的29.72%,主要供應給醫院、購物中心、飯店和其他偏好靜音、封閉式和節能型發電機的場所。
預計375-750 kVA功率範圍將以8.45%的複合年成長率成長,這是所有頻寬內最高的成長率,主要受資料中心、礦業和大規模通訊樞紐等行業對可擴展且兼容並行運行的封裝的需求驅動。阿特拉斯·科普柯於2024年6月推出的QES系列產品,憑藉其提升同步性能和穩健性的特性,直接瞄準了這一細分市場。 750 kVA至2 MW的高功率範圍則面向電力公司、冶煉廠和石化聯合企業,這些企業更注重全生命週期成本和排放法規合規性,而非採購價格。珀金斯即將推出的2606系列引擎將憑藉其對氫化植物油(HVO)的兼容性和更長的維護週期,滿足這一中高階市場的需求。在2 MW以上的功率範圍內,燃氣渦輪機開始逐步蠶食柴油發電機的市場佔有率,但在活塞式引擎在燃料物流和瞬態負載方面具有優勢的領域,柴油發電機仍然備受青睞,並且該領域在非洲柴油發電機市場中繼續佔據重要地位。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 撒哈拉以南非洲地區停電頻率增加
- 奈及利亞、肯亞和南非(三級/四級)資料中心容量快速擴張
- 由於4G和5G部署,通訊塔密度更高。
- 中南部非洲礦業部門從併網供電向現場發電的過渡
- 企業對符合ESG標準的「HVO合規」柴油發電機組的需求日益成長。
- 非洲自由貿易區(AfCFTA)對跨境租賃設備發展的支持
- 市場限制因素
- 太陽能+鋰離子電池混合發電的價格平價正在加速實現,低於0.18美元/kWh。
- 自 2022 年起,由於國際海事組織 (IMO) 船用燃料法規改革,柴油進口價格將出現波動。
- 南非(NEM:AQA)和奈及利亞(NESREA)實施更嚴格的排放上限
- 一種新型燃氣緊湊型模組化渦輪機,用於取代功率超過 2MW 的備用發電機。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按容量(千伏安)
- 75千伏安或以下
- 75~375kVA
- 375~750kVA
- 750~2,000kVA
- 2000千伏安或以上
- 透過使用
- 備用電源
- 主電源/持續電源
- 尖峰用電調節/負載管理
- 最終用戶
- 住宅
- 商業
- 產業
- 按地區
- 奈及利亞
- 南非
- 埃及
- 肯亞
- 阿爾及利亞
- 摩洛哥
- 其他非洲地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Caterpillar Inc.
- Cummins Inc.
- Aggreko PLC
- Atlas Copco AB
- AKSA Power Generation
- Kirloskar Oil Engines Ltd
- Mitsubishi Heavy Industries Ltd
- Perkins Engines Company Ltd
- Yanmar Holdings Co. Ltd
- Briggs & Stratton Corp
- Generac Holdings Inc.
- Wartsila Corp
- FG Wilson(CAT)
- Doosan Portable Power
- HIMOINSA(Sumitomo)
- Rolls-Royce Power Systems/MTU
- Kohler-SDMO
- APR Energy PLC
- Siemens Energy AG
- JCB Power Systems
第7章 市場機會與未來展望
According to Mordor Intelligence, Africa diesel generator market size in 2026 is estimated at USD 1 billion, growing from 2025 value of USD 0.94 billion with 2031 projections showing USD 1.38 billion, growing at 6.57% CAGR over 2026-2031.
This report is Segmented by Capacity (below 75 KVA, 75 To 375 KVA, 375 To 750 KVA, 750 To 2, 000 KVA, and Above 2, 000 KVA), Application (Stand-by/Backup Power, Prime/Continuous Power, and Peak-shaving/Load Management), End User (Residential, Commercial, and Industrial), and Geography (Nigeria, South Africa, Egypt, Kenya, Algeria, Morocco, and Rest of Africa).
Africa Diesel Generator Market Trends and Insights
Rising Frequency of Grid Outages in Sub-Saharan Africa
Persistent grid unreliability anchors demand across the Africa diesel generator market, with 34 countries averaging 56 hours of monthly outages in 2024. Nigeria's grid collapsed 12 times during the first half of the year, forcing industrial users to run gensets in prime-power mode, which accelerates wear and shortens replacement cycles. Kenya's electrification drive connected 1.2 million households, yet voltage fluctuations remain endemic, motivating peri-urban buyers to install small diesel units. South Africa endured Stage 6 load-shedding for 118 days, prompting hospitals, data centers, and factories to deploy permanent backup arrays sized for 8-12 hours of autonomous runtime. Under-funded utilities defer grid upgrades, creating a self-reinforcing loop that keeps diesel a default hedge against supply risk for the coming decade.
Rapid Build-Out of Data-Center Capacity Across Nigeria, Kenya & South Africa
Hyperscale and colocation operators commissioned 12 Tier III and Tier IV sites in 2024, each requiring 2-10 MW of N+1 or 2N diesel redundancy. Caterpillar joined the Africa Data Centres Association in 2024, signaling OEM confidence that cloud providers view diesel as the most bankable standby option where gas infrastructure is absent. Microsoft and Equinix announced new campuses in South Africa and Kenya, citing the need for low latency and favorable power purchase structures that bundle grid supply with on-site diesel. Uptime Institute rules mandate concurrent maintainability, practically locking in high-specification diesel arrays that can black-start within 10 seconds. While operators explore battery ride-through solutions, diesel retains a 5-7-year advantage for multi-megawatt backup, cementing its place at the heart of the Africa diesel generator market.
Accelerating Price Parity of Solar-Plus-Battery Hybrids
Utility-scale solar with four-hour lithium-ion storage now delivers power at USD 0.15-0.18 /kWh in high-insolation African regions, outcompeting diesel's USD 0.22-0.28 operating cost for continuous duty. Malawi's 2024 decision to replace Aggreko diesel rentals with a grid-scale battery underscores shifting economics and sends a cautionary signal to rental operators in the Africa diesel generator market. For standby uses with less than 500 runtime hours annually, solar-battery systems with six-hour autonomy already outperform diesel on total cost of ownership, potentially threatening future replacement sales.
Other drivers and restraints analyzed in the detailed report include:
- Telecom-Tower Densification for 4G & 5G Roll-Outs
- Mining Sector's Shift from Grid to Captive Power in Central & Southern Africa
- Stricter Emission Caps in South Africa and Nigeria
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Below 75 kVA gensets captured 44.02% of the 2025 revenue, reflecting mass adoption by urban households, corner stores, and telecom base stations that require 10-50 kW of backup power during persistent load shedding, this category is highly fragmented, served by Chinese and Indian brands competing on upfront price. Units in the 75-375 kVA bracket accounted for roughly 29.72% of the Africa diesel generator market share in 2025, supplying hospitals, malls, and hotels that favor quieter, enclosed sets with improved fuel efficiency.
The 375-750 kVA range is forecast to advance at an 8.45% CAGR, the fastest of any band, driven by data centers, mining, and large telecom hubs that require scalable, parallel-ready packages. Atlas Copco's June 2024 QES launch directly targets this segment with features that enhance synchronization and ruggedization. Higher ratings between 750 kVA and 2 MW serve utilities, smelters, and petrochemical complexes that prioritize total life-cycle cost and emission compliance over sticker price. Perkins' forthcoming 2606 Series engine addresses this upper-mid tier with HVO compatibility and extended maintenance intervals. Above 2 MW, gas-fired turbines begin to erode diesel demand; yet, diesel persists where fuel logistics or transient loads favor piston engines, keeping this slice pertinent to the broader African diesel generator market.
Complete Report Scope:
- By Capacity (kVA)
- Below 75 kVA
- 75 to 375 kVA
- 375 to 750 kVA
- 750 to 2,000 kVA
- Above 2,000 kVA
- By Application
- Stand-by/Backup Power
- Prime/Continuous Power
- Peak-shaving/Load Management
- By End User
- Residential
- Commercial
- Industrial
- By Geography
- Nigeria
- South Africa
- Egypt
- Kenya
- Algeria
- Morocco
- Rest of Africa
List of Companies Covered in this Report:
- Caterpillar Inc.
- Cummins Inc.
- Aggreko PLC
- Atlas Copco AB
- AKSA Power Generation
- Kirloskar Oil Engines Ltd
- Mitsubishi Heavy Industries Ltd
- Perkins Engines Company Ltd
- Yanmar Holdings Co. Ltd
- Briggs & Stratton Corp
- Generac Holdings Inc.
- Wartsila Corp
- FG Wilson (CAT)
- Doosan Portable Power
- HIMOINSA (Sumitomo)
- Rolls-Royce Power Systems / MTU
- Kohler-SDMO
- APR Energy PLC
- Siemens Energy AG
- JCB Power Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising frequency of grid outages in Sub-Saharan Africa
- 4.2.2 Rapid build-out of data-center capacity across Nigeria, Kenya & South Africa (Tier III / Tier IV)
- 4.2.3 Telecom tower densification for 4G & 5G roll-outs
- 4.2.4 Mining sector's shift from grid to captive power in Central & Southern Africa
- 4.2.5 Growing corporate demand for ESG-compliant "HVO-ready" diesel gensets
- 4.2.6 African Continental Free Trade Area (AfCFTA) catalyzing cross-border rental fleets
- 4.3 Market Restraints
- 4.3.1 Accelerating price parity of solar-plus-lithium-battery hybrids at < $0.18 /kWh
- 4.3.2 Diesel import-price volatility post-2022 IMO marine fuel reforms
- 4.3.3 Stricter emission caps in South Africa (NEM:AQA) & Nigeria (NESREA)
- 4.3.4 New gas-fired small-modular turbines displacing >2 MW standby gensets
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Capacity (kVA)
- 5.1.1 Below 75 kVA
- 5.1.2 75 to 375 kVA
- 5.1.3 375 to 750 kVA
- 5.1.4 750 to 2,000 kVA
- 5.1.5 Above 2,000 kVA
- 5.2 By Application
- 5.2.1 Stand-by/Backup Power
- 5.2.2 Prime/Continuous Power
- 5.2.3 Peak-shaving/Load Management
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.4 By Geography
- 5.4.1 Nigeria
- 5.4.2 South Africa
- 5.4.3 Egypt
- 5.4.4 Kenya
- 5.4.5 Algeria
- 5.4.6 Morocco
- 5.4.7 Rest of Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Cummins Inc.
- 6.4.3 Aggreko PLC
- 6.4.4 Atlas Copco AB
- 6.4.5 AKSA Power Generation
- 6.4.6 Kirloskar Oil Engines Ltd
- 6.4.7 Mitsubishi Heavy Industries Ltd
- 6.4.8 Perkins Engines Company Ltd
- 6.4.9 Yanmar Holdings Co. Ltd
- 6.4.10 Briggs & Stratton Corp
- 6.4.11 Generac Holdings Inc.
- 6.4.12 Wartsila Corp
- 6.4.13 FG Wilson (CAT)
- 6.4.14 Doosan Portable Power
- 6.4.15 HIMOINSA (Sumitomo)
- 6.4.16 Rolls-Royce Power Systems / MTU
- 6.4.17 Kohler-SDMO
- 6.4.18 APR Energy PLC
- 6.4.19 Siemens Energy AG
- 6.4.20 JCB Power Systems
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 印度柴油發電機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)歐洲柴油發電機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)柴油發電機:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 柴油發電機市場-2026-2032年全球市場預測
 柴油發電機市場預測至2034年—按便攜性、額定功率、應用、最終用戶和地區分類的全球分析亞太地區柴油發電機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 全球柴油發電機市場(至2031年):按設計(固定式和可攜式)、應用(備用、抑低尖峰負載、主用和連續用)、最終用戶(工業、商業和住宅)、額定功率和地區分類
 柴油發電機市場報告:按容量、應用、便攜性、最終用戶和地區分類(2026-2034 年)
 柴油發電機市場:按應用、功率輸出、最終用戶和地區分類
 全球柴油發電機市場規模、佔有率、趨勢和成長分析報告(2026-2034年)