


 |
市場調查報告書
商品編碼
2113770
越南有機肥料:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Vietnam Organic Fertilizer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
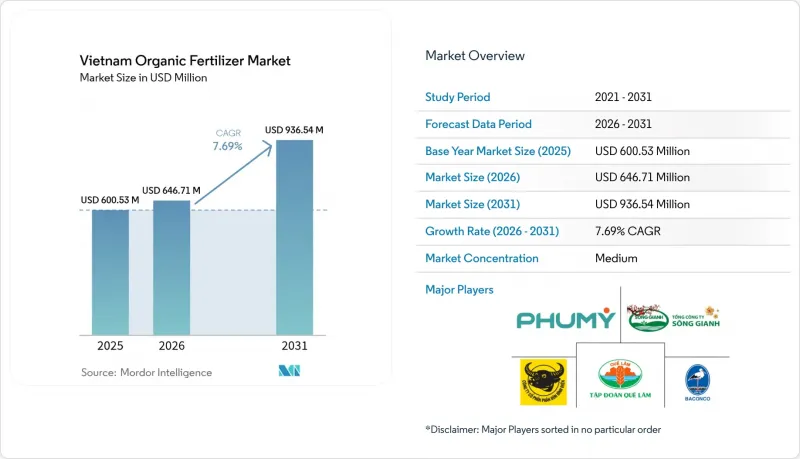
預計越南有機肥料市場將從 2025 年的 6.0053 億美元成長到 2026 年的 6.4671 億美元,然後從 2026 年到 2031 年以 7.69% 的複合年成長率成長,到 2031 年達到 9.3654 億美元。
本報告按產品(有機殘渣和生物肥料)、形態(乾燥顆粒和液體/懸浮濃縮液)以及應用(穀物、油籽和豆類、水果和蔬菜、草坪和觀賞植物以及其他作物)進行細分。市場預測以價值(美元)和數量(公噸)表示。
越南有機肥料市場趨勢及洞察
政府目標是提高有機肥料的利用率
越南力爭2050年將有機肥使用率提高到50%,這一目標對整個農業部門的物料籌資策略產生了重大影響。 2025年,政府第5190/QD-BNN-BVTV號決議制定了2030年有機肥料發展的具體目標,包括產能要求和品質認證標準。儘管各省的具體實施情況有所不同,但例如北江省提出的到2025年實現80%畜禽糞便回收利用的目標,就體現了地方政府如何落實國家指南。 2025年農業和環境監管職能的整合縮短了核准流程,使生產商能夠更有效率地將新產品推向市場。這些政策措施有助於維持不同作物對有機肥料的持續需求,並為越南有機肥料市場帶來穩定。
經認證的有機農產品出口需求激增
出口市場對認證有機農產品的高溢價正在推動越南果蔬產業採用有機肥料。預計到2025年,越南有機農產品出口收入將達到3.35億美元,由於歐洲、北美和亞洲等已開發市場對供應商審核力度加大,這一數字仍在持續成長。與傳統農產品相比,有機農產品20%至30%的溢價促使蔬果生產商轉向使用有機肥料。這一趨勢在胡志明市附近尤其明顯,因為那裡的低溫運輸設施完善,港口交通便利。越南南部地區的生產商也受益於其靠近胡志明市的出口基礎設施和分銷網路。這些溢價使生產商能夠在保持國際市場競爭力的同時,有效應對有機肥料成本上漲的問題。
品質參差不齊和假冒“有機”產品損害了農民的信譽。
劣質、貼錯標籤的有機肥料氾濫,正在削弱農民的信心,阻礙市場成長。這對無力承擔購買無效產品風險的小規模農戶影響尤其嚴重。在越南,市面上流通的1000多種生物肥料中,只有約50種獲得國家認證,這導致品管存在嚴重問題,並使假冒產品充斥市場。這種品質參差不齊的問題在越南北部的小規模農戶群體中尤為突出。由於該地區農業推廣服務有限,農民難以區分仿冒品,因此不願採用有機肥料。
細分市場分析
預計2025年,越南有機肥料市場中,有機殘渣將佔63.78%的市佔率。這主要得益於畜禽糞便、稻殼和咖啡果肉等經濟實惠的原料,它們與現有的堆肥系統相容。畜禽糞便是目前的主要原料,而平陽省水利環境公司營運的日處理量420噸的都市垃圾堆肥廠則為郊區蔬菜種植區提供原料。這些原料來源得益於完善的分銷網路,確保全年價格穩定,從而鞏固了有機殘渣在市場上的主導地位。
隨著越南國內實驗室研發出專門針對越南土壤條件的固氮菌、根瘤菌和菌根真菌菌株,預計到2031年,生物肥料市場將以10.05%的複合年成長率成長。這些產品在果園中應用最為廣泛,農民正投資購買高品質的肥料,以提高微量元素的吸收率並延長作物壽命。第36-NQ/TW號決議對生物技術發展的持續支持可望擴大田間試驗規模並加速商業化生產。這將使生物肥料成為越南有機肥料市場的關鍵成長領域。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府目標是提高有機肥料的利用率
- 經認證的有機產品出口需求激增
- 化肥價格飆升進一步提高了有機材料的成本競爭力。
- 劣化的土壤需要長期補充有機質。
- 技術進步與產品創新
- 原料和廢物流的可用性
- 市場限制因素
- 品質參差不齊和假冒“有機”產品正在損害生產商的聲譽。
- 小規模農戶的融資限制阻礙了他們早期向高品質生物肥料的過渡。
- 有機農產品低溫運輸有限,抑制了需求成長。
- 緩釋肥料的釋放與風險意識
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品
- 有機殘留物
- 牲畜糞便
- 作物殘茬
- 綠肥
- 其他殘渣(家禽糞便、魚類廢棄物、都市固態廢棄物等)
- 生物肥料
- 固氮菌
- 根瘤菌
- 固氮螺菌
- 藍藻
- 滿江紅
- 菌根
- 其他生物肥料(例如芽孢桿菌和弗蘭克氏菌)
- 有機殘留物
- 按形式
- 乾顆粒
- 液體和懸浮濃縮物
- 透過使用
- 穀物和穀類
- 油籽/豆類
- 水果和蔬菜
- 草坪和觀賞植物
- 其他作物(飼料作物、牧草作物、經濟作物等)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Binh Dien Fertilizer Joint Stock Company
- Que Lam Group Joint Stock Company
- Song Gianh Joint Stock Corporation
- Baconco Company Limited(PM Thoresen Asia Holdings Public Company Limited)
- Bioway Hitech Joint Stock Company
- Ha Lan Fertilizer Corporation
- Vedan Vietnam Enterprise Corporation Limited
- PetroVietnam Fertilizer and Chemicals Corporation
- Yara International ASA
- Bio Agrosa Fertilizer Co., Ltd
- Vietgro Export Import Company Limited
- Swaroop Agrochemical Industries Private Limited
- Kim Nghia Co. Ltd.
- Agrivari Co., Ltd.
- Thanh Thanh Cong-Bien Hoa Joint Stock Company(TTC AgriS)
第7章 市場機會與未來展望
According to Mordor Intelligence, the Vietnam organic fertilizer market size is expected to grow from USD 600.53 million in 2025 to USD 646.71 million in 2026 and is forecast to reach USD 936.54 million by 2031 at 7.69% CAGR over 2026-2031.
This report is Segmented by Product (Organic Residues and Biofertilizers), by Form (Dry Granules and Liquid and Suspension Concentrates), and by Application (Grains and Cereals, Oilseeds and Pulses, Fruits and Vegetables, Turf and Ornamentals, and Other Crops). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Metric Tons).
Vietnam Organic Fertilizer Market Trends and Insights
Government Target to Raise Organic Fertilizer Utilization
Vietnam's target of 50% organic fertilizer usage by 2050 significantly impacts input procurement strategies across the agricultural sector. In 2025, the government's Decision 5190/QD-BNN-BVTV outlines specific targets for organic fertilizer development through 2030, including production capacity requirements and quality certification standards. While implementation varies by province, initiatives such as Bac Giang's target to recycle 80% of livestock waste by 2025 demonstrate how regional authorities implement national directives. The 2025 consolidation of agricultural and environmental oversight reduced regulatory approval times, allowing producers to launch new products more efficiently. These policy measures support consistent demand across crop varieties, providing stability to Vietnam's organic fertilizer market.
Surging Demand for Certified Organic Exports
The price premiums for certified organic produce in export markets drive the adoption of organic fertilizers in Vietnam's fruit and vegetable sectors. Vietnam's organic export revenues reached USD 335 million in 2025, with continued growth driven by increased supplier audits from European, North American, and developed Asian markets. The 20-30% premium over conventional produce encourages fruit and vegetable growers to transition to organic inputs, particularly near Ho Chi Minh City, where cold-chain facilities provide efficient port access. Producers in Southern Vietnam benefit from their proximity to Ho Chi Minh City's export infrastructure and distribution networks. These price premiums enable producers to absorb higher organic fertilizer costs while maintaining competitiveness in international markets.
Quality Variability and Counterfeit "Organic" Products Erode Farmer Trust
The widespread presence of low-quality and incorrectly labeled organic fertilizers reduces farmer trust and limits market growth, especially affecting small-scale farmers who cannot risk purchasing ineffective products. In Vietnam, only about 50 out of 1,000 bio-preparations in circulation have received national certification, creating significant quality control issues that allow counterfeit products to enter the market. This quality inconsistency is particularly problematic in Northern Vietnam's small-scale farming sector, where limited agricultural extension services make it difficult for farmers to identify genuine products from counterfeits, resulting in reluctance to adopt organic fertilizers.
Other drivers and restraints analyzed in the detailed report include:
- High Chemical-Fertilizer Prices Widen the Cost-Competitiveness of Organic Inputs
- Degraded Soils Require Long-Term Organic-Matter Replenishment
- Limited Cold-chain for Organic Produce Tempers Demand Pull
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Organic residues account for 63.78% of the Vietnam organic fertilizer market share in 2025, driven by the availability of livestock manure, rice husks, and coffee pulp as cost-effective feedstock compatible with existing composting systems. Farmyard manure dominates the sub-segments, while the 420 metric tons per day municipal waste composting facility of Binh Duong Water - Environment Joint Stock Company supplies the peri-urban vegetable farming regions. These sources support an established distribution network that maintains consistent pricing throughout the year, securing the dominant position of residues in the market.
Biofertilizers are projected to grow at a 10.05% CAGR through 2031, as domestic laboratories develop Azotobacter, Rhizobium, and Mycorrhiza strains specific to Vietnam's soil conditions. These products see the highest adoption in fruit orchards, where farmers can invest in premium inputs to enhance micronutrient absorption and product longevity. The ongoing support through Resolution 36-NQ/TW for biotechnology development is anticipated to expand field testing and accelerate commercial production, establishing biofertilizers as a significant growth segment in the Vietnam organic fertilizer market.
Complete Report Scope:
- By Product
- Organic Residues
- Farm Yard Manure
- Crop Residues
- Green Manure
- Other Residues (Poultry Droppings, Fish Waste, Municipal Solid Waste, etc.)
- Biofertilizers
- Azotobacter
- Rhizobium
- Azospirillum
- Blue-Green Algae
- Azolla
- Mycorrhiza
- Other Biofertilizers (Bacillus, Frankia, etc.)
- Organic Residues
- By Form
- Dry Granules
- Liquid and Suspension Concentrates
- By Application
- Grains and Cereals
- Oilseeds and Pulses
- Fruits and Vegetables
- Turf and Ornamentals
- Other Crops (Fodder and Forage Crops, Commercial Crops, etc.)
List of Companies Covered in this Report:
- Binh Dien Fertilizer Joint Stock Company
- Que Lam Group Joint Stock Company
- Song Gianh Joint Stock Corporation
- Baconco Company Limited (PM Thoresen Asia Holdings Public Company Limited)
- Bioway Hitech Joint Stock Company
- Ha Lan Fertilizer Corporation
- Vedan Vietnam Enterprise Corporation Limited
- PetroVietnam Fertilizer and Chemicals Corporation
- Yara International ASA
- Bio Agrosa Fertilizer Co., Ltd
- Vietgro Export Import Company Limited
- Swaroop Agrochemical Industries Private Limited
- Kim Nghia Co. Ltd.
- Agrivari Co., Ltd.
- Thanh Thanh Cong - Bien Hoa Joint Stock Company (TTC AgriS)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Target to Raise Organic Fertilizer Utilization
- 4.2.2 Surging Demand for Certified Organic Exports
- 4.2.3 High Chemical-Fertilizer Prices Widen the Cost-Competitiveness of Organic Inputs
- 4.2.4 Degraded Soils Require Long-Term Organic-Matter Replenishment
- 4.2.5 Technological Advancement and Product Innovation
- 4.2.6 Availability of Raw Materials and Waste Streams
- 4.3 Market Restraints
- 4.3.1 Quality Variability and Counterfeit "Organic" Products Erode Farmer Trust
- 4.3.2 Smallholder cash-flow limits hinder upfront switch to premium biofertilizers
- 4.3.3 Limited Cold-chain for Organic Produce Tempers Demand Pull
- 4.3.4 Slow Nutrient Release and Risk Perception
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Product
- 5.1.1 Organic Residues
- 5.1.1.1 Farm Yard Manure
- 5.1.1.2 Crop Residues
- 5.1.1.3 Green Manure
- 5.1.1.4 Other Residues (Poultry Droppings, Fish Waste, Municipal Solid Waste, etc.)
- 5.1.2 Biofertilizers
- 5.1.2.1 Azotobacter
- 5.1.2.2 Rhizobium
- 5.1.2.3 Azospirillum
- 5.1.2.4 Blue-Green Algae
- 5.1.2.5 Azolla
- 5.1.2.6 Mycorrhiza
- 5.1.2.7 Other Biofertilizers (Bacillus, Frankia, etc.)
- 5.1.1 Organic Residues
- 5.2 By Form
- 5.2.1 Dry Granules
- 5.2.2 Liquid and Suspension Concentrates
- 5.3 By Application
- 5.3.1 Grains and Cereals
- 5.3.2 Oilseeds and Pulses
- 5.3.3 Fruits and Vegetables
- 5.3.4 Turf and Ornamentals
- 5.3.5 Other Crops (Fodder and Forage Crops, Commercial Crops, etc.)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Binh Dien Fertilizer Joint Stock Company
- 6.4.2 Que Lam Group Joint Stock Company
- 6.4.3 Song Gianh Joint Stock Corporation
- 6.4.4 Baconco Company Limited (PM Thoresen Asia Holdings Public Company Limited)
- 6.4.5 Bioway Hitech Joint Stock Company
- 6.4.6 Ha Lan Fertilizer Corporation
- 6.4.7 Vedan Vietnam Enterprise Corporation Limited
- 6.4.8 PetroVietnam Fertilizer and Chemicals Corporation
- 6.4.9 Yara International ASA
- 6.4.10 Bio Agrosa Fertilizer Co., Ltd
- 6.4.11 Vietgro Export Import Company Limited
- 6.4.12 Swaroop Agrochemical Industries Private Limited
- 6.4.13 Kim Nghia Co. Ltd.
- 6.4.14 Agrivari Co., Ltd.
- 6.4.15 Thanh Thanh Cong - Bien Hoa Joint Stock Company (TTC AgriS)
7 Market Opportunities and Future Outlook

 有機肥料市場報告:趨勢、預測與競爭分析(至2035年)
 有機農藥市場-2026-2032年全球市場預測
 磷強化有機肥料:市佔率分析、產業趨勢與統計及成長預測(2026-2031)有機肥料市場:2026-2032年全球市場預測(依原料、產品形態、混合、作物類型、應用、最終用戶和銷售管道分類)美國有機肥料:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 2026年全球綠肥市場報告
 全球有機肥料市場規模、佔有率、趨勢和成長分析報告(2026-2034年)北美有機肥料:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)富磷有機肥市場:依作物類型、形態、應用通路-2026-2032年全球預測
 全球有機肥料市場:市場規模、佔有率和趨勢分析(按產品、形態、應用和地區分類),細分市場預測(2026-2033 年)