


 |
市場調查報告書
商品編碼
2073286
人工智慧驅動的薪資核算分析:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)AI-Powered Payroll Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
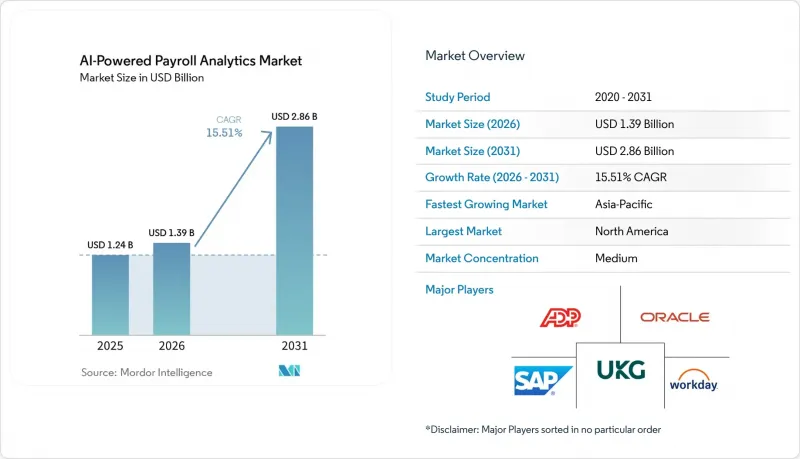
根據 Mordor Intelligence 預測,人工智慧驅動的薪資分析市場預計將從 2025 年的 12.4 億美元成長到 2026 年的 13.9 億美元,然後在 2031 年達到 28.6 億美元,2026 年至 2031 年的複合年成長率為 15.51%。
本報告按組件(軟體和服務)、分析類型(預測性薪資分析等)、部署模式(雲端和本地部署)、組織規模(中小企業和大型企業)、行業(IT和電信、零售和電子商務等)以及地區進行細分。市場預測以美元計價。
全球人工智慧薪資核算分析市場趨勢與洞察。
雲端薪資核算套件的快速普及
Workday 的彈性運算、API 優先架構和承包AI 模組正在加速企業從本地部署遷移到雲端。 Workday 推出僅兩年,就在澳洲獲得了 60 多家薪資核算客戶,其中至少一半將在 2025 年底前運作。 ADP 與三大雲端平台——AWS、Azure 和 GCP——的夥伴關係,實現了匿名化薪資資料集的商業化,從而打造出小規模的競爭對手難以複製的標竿工具。 Workday 的部署代理商計畫於 2026 年 2 月發布,預計將部署時間縮短 25%,對於沒有專屬 IT 資源的中型企業來說,這無疑是一個極具吸引力的提案。根據澳洲薪資協會 (Australian Payroll Association) 的數據顯示,23.6% 的薪資核算團隊認為系統整合不佳是瓶頸所在,而雲端原生平台正是為了解決這些效率低下的問題而設計的。所有這些趨勢共同推動雲端運算在 AI 驅動的薪資分析市場成長中扮演核心角色。
多邊薪資核算。
歐盟的《工資透明指令》(2026年6月6日生效)強制要求披露基於性別的工資差距,而加州的SB 464法案則要求企業每年提交工資數據報告,並對不準確的報告處以逐步提高的處罰。紐約市的《Int. 982-A》和安大略省的《工人權益法》也提出了類似的要求,要求雇主將合規管理功能整合到日常薪資核算流程中。在五個或更多司法管轄區運營的公司每年要應對超過50項法律變更,手動更新已變得不切實際。供應商正在透過提供人工智慧代理來應對這項挑戰,這些代理商可以掃描提案資訊並自動配置預扣稅報表,這項功能目前在北美和歐洲的招標書中排名前三。因此,持續不斷的監管變化是人工智慧驅動的薪資核算分析市場長期成長的基礎。
資料隱私和跨境資料傳輸限制
加州《消費者隱私保護法》(CPPA) 將於 2025 年 10 月生效,該法規強制要求對自動工資計算進行偏見預防測試、網路安全審計和選擇退出程序,這將顯著增加在多個州開展業務的雇主的合規預算。美國司法部的《批量資料傳輸條例》(2025 年 4 月) 限制了海外的管理存取權限,迫使全球供應商部署主權雲端區域。根據《一般資料保護規範》(GDPR),未獲得批准的安全保障措施的公司將面臨資料流中斷,這增加了對客戶管理的加密金鑰和機密運算區域的需求。每增加一項安全保障措施,都會增加延遲、成本和法律風險,進而減緩人工智慧驅動的工資分析產業的普及速度。
細分市場分析
在人工智慧驅動的薪資分析市場中,實施、諮詢和支援服務成長最為迅速,年複合成長率高達17.78%,主要得益於企業應對傳統ERP整合、自主雲端部署和薪資差距報告等挑戰。儘管預計到2025年軟體仍將佔據65.44%的收入佔有率,但買家越來越傾向於將代碼視為普通商品,而將最終成果視為溢價。能夠提供符合GDPR資料傳輸影響評估和加州CPPA審計要求的承包解決方案的供應商,其客戶成交率更高。
運作後調優的需求也正在加速成長。季度偏差審計、模型漂移校正以及基於法規的規則引擎更新都需要人工監督,而這往往是企業內部團隊所缺乏的。 Zalaris 建議每年至少進行四次合規性檢驗,以確保 AI 輸出始終處於合理狀態。因此,隨著各組織將持續最佳化視為維護其品牌和監管地位的關鍵,預計業務收益將在 AI 驅動的薪資分析市場中佔據更大的佔有率。
截至2025年,預測性薪資分析佔總收入的34.11%,但詐欺和異常偵測的成長速度超過了這一比例,這反映出網路安全威脅日益加劇和審計要求更加嚴格。在過去兩年中,70%的公司至少經歷過一次與薪資相關的資料洩露,因此董事會現在強制要求進行持續監控。 Workday的財務測試套件增加了自動控制支付暫停的功能,強調了從「偵測」到「預防」的轉變。
整合趨勢顯而易見。目前,套件產品將成本建模、薪資差距診斷和異常掃描整合到一個統一的平台中,簡化了基於角色的存取管治和證據記錄。能夠在幾分鐘內(而非幾天)識別差異根本原因的供應商正在獲得競爭優勢,這表明在預測期內,詐欺分析將在人工智慧驅動的薪資分析市場中繼續擴大其佔有率。
區域分析
到2025年,北美將佔全球整體收入的38.14%。加州SB 464法案、紐約市982-A號法令以及安大略省的《工人權益第四法案》均支持此目標,這些法案強制要求提交詳細的薪資數據報告。供應商整合,例如Paychex以41億美元收購Paycor,將使收購公司能夠利用覆蓋美國私部門十一分之一員工的平台,從而增強規模經濟效益,加速功能部署。
亞太地區是成長最快的地區,複合年成長率高達16.51%。印度薪資核算負責人缺口高達75%,澳洲的薪資覆蓋率也存在43%的缺口,這些都促使企業尋求自動化流程並偵測異常情況。 Workday在澳洲市場的快速普及表明,該地區對人工智慧驅動的合規警報有著巨大的需求。同時,像PaidHR這樣的非洲新創公司將企業發展拓展至49個貨幣區,凸顯了尚未開發的市場領域所蘊藏的巨大機會。
在歐洲,人工智慧薪資分析技術正穩步普及,這得益於歐盟工資透明度指令的推動,該指令將於2026年6月生效。 SD Worx於2026年2月收購了Paie和RH Solutions,使其法國中小企業基本客群增加了1,100家,顯示中型企業市場的競爭日益激烈。南美、中東和非洲仍處於起步階段,但一些雲端優先的新興參與企業正在進入外匯地區和稅收環境分散的市場,為人工智慧驅動的薪資核算分析市場注入了強勁的長期成長動力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 雲端薪資核算解決方案的快速普及
- 多邊薪資核算。
- 為了改善勞動力規劃,對即時薪資數據分析的需求日益成長。
- 人工智慧驅動的詐欺偵測和薪資核算合規性監控
- 創業投資增加,扶持人力資源科技新創公司
- 整合薪酬分析與財務健康計劃
- 市場限制因素
- 資料隱私和跨境資料傳輸法規
- 薪資水平高的資料科學人才短缺
- 大型企業的傳統薪資核算體系
- 中小企業初始整合成本高昂
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 軟體
- 服務
- 實施服務
- 諮詢服務
- 支援和維護服務
- 按分析類型
- 預測性薪資分析
- 自動化合規性和風險分析
- 工資詐欺和異常檢測
- 人工智慧驅動的人事費用最佳化模型
- 人工智慧驅動的薪資差距與薪酬分析
- 其他分析類型
- 部署模式
- 雲
- 現場
- 按組織規模
- 中小企業
- 大公司
- 按行業分類
- 資訊科技/通訊
- BFSI
- 衛生保健
- 零售與電子商務
- 製造業
- 政府/公共部門
- 其他工業部門
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Automatic Data Processing, Inc.
- Paychex, Inc.
- Paycom Software, Inc.
- Ceridian HCM Holding Inc.
- Paycor HCM, Inc.
- Intuit Inc.
- Workday, Inc.
- Gusto, Inc.
- Rippling People Center, Inc.
- Zenefits LLC
- BambooHR LLC
- UKG Inc.
- Oracle Corporation
- SAP SE
- Ramco Systems Limited
- Zoho Corporation Private Limited
- Deel, Inc.
- Papaya Global Ltd.
- Neeyamo Enterprise Solutions Private Limited
- Namely Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the AI-Powered payroll analytics market size is expected to grow from USD 1.24 billion in 2025 to USD 1.39 billion in 2026 and is forecast to reach USD 2.86 billion by 2031 at a 15.51% CAGR over 2026-2031.
This report is Segmented by Component (Software and Services), Analytics Type (Predictive Payroll Analytics, and More), Deployment Mode (Cloud and On-Premise), Organization Size (Small and Medium Enterprises and Large Enterprises), Industry Vertical (IT and Telecommunications, Retail and E-Commerce, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global AI-Powered Payroll Analytics Market Trends and Insights
Rapid Adoption of Cloud-Based Payroll Suites
Elastic compute, API-first architectures, and turnkey AI modules are pushing enterprises to abandon on-premise deployments. Workday added more than 60 Australian payroll customers within two years of launch, and at least half were already live by late 2025.ADP's three-cloud partnership with AWS, Azure, and GCP unlocked monetization of anonymized payroll datasets, powering benchmarking tools that smaller rivals cannot match. Workday's Deployment Agent, available February 2026, is projected to cut implementation timelines by 25%, a value proposition resonating with midsize companies that lack dedicated IT resources. The Australian Payroll Association reported that 23.6% of payroll teams cited poor systems integration as a bottleneck, an inefficiency cloud-native platforms are designed to remove. Collectively, these developments place cloud at the center of the AI-Powered Payroll Analytics market growth narrative.
Increasing Regulatory Complexity in Multi-Country Payroll
The EU Pay Transparency Directive (effective June 6 2026) mandates gender-segmented pay-gap disclosure, while California's SB 464 imposes annual pay-data reporting with escalating fines for inaccuracies. New York City's Int. 982-A and Ontario's Working for Workers Four Act extend similar obligations, compelling employers to embed compliance intelligence into everyday payroll workflows. Enterprises operating across five or more jurisdictions already manage 50-plus statutory changes annually, rendering manual updates untenable. Vendors are responding by shipping AI agents that scan legislative feeds and auto-configure withholding tables, a capability now cited as top-three in RFPs across North America and Europe. Persistent rule churn therefore underpins the long-run trajectory of the AI-Powered Payroll Analytics market.
Data Privacy and Cross-Border Data Transfer Restrictions
California's CPPA rules effective October 2025 require anti-bias testing, cybersecurity audits, and opt-out flows for automated pay decisions, materially increasing compliance budgets for multistate employers. The U.S. Department of Justice Bulk Data Transfer Rule (April 2025) limits offshore administrative access, compelling global vendors to introduce sovereign-cloud regions. Under GDPR, companies lacking approved safeguards face suspension of data flows, spurring demand for customer-managed encryption keys and confidential-computing enclaves. Each additional safeguard adds latency, cost, and legal exposure, tempering adoption velocity in the AI-Powered Payroll Analytics industry.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Real-Time Payroll Insights to Improve Workforce Planning
- AI-Driven Fraud Detection and Payroll Compliance Monitoring
- Shortage of Payroll Data Science Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Implementation, consulting, and support services accounted for the fastest growth inside the AI-Powered Payroll Analytics market, advancing at 17.78% CAGR as enterprises tackled legacy ERP integration, sovereign-cloud provisioning, and pay-equity reporting. Although software maintained a 65.44% revenue share in 2025, buyers increasingly view code as commodity and outcomes as premium. Vendors that wrap turnkey playbooks around GDPR transfer impact assessments and California CPPA audits capture higher attach rates.
Demand for post-go-live tuning is also accelerating. Quarterly bias audits, model-drift remediation, and legislative rule-engine updates require human oversight that internal teams often lack. Zalaris recommends at least four compliance validation cycles per year to keep AI outputs defensible. Consequently, services revenues are projected to lift their share of the AI-Powered Payroll Analytics market size as organizations treat continuous optimization as essential to safeguard brand and regulatory standing.
Predictive payroll analytics held a 34.11% revenue share in 2025, but fraud and anomaly detection is rising faster, reflecting heightened cyber-security threats and stricter audit obligations. With 70% of enterprises encountering at least one payroll breach in two years, boards now mandate continuous monitoring regimes. Workday's Financial Test Suite adds automated stop-payment controls, underscoring a pivot from identification to prevention.
Convergence is emerging. Suites now bundle cost modeling, pay-equity diagnostics, and anomaly scanning in a unified canvas, simplifying role-based access governance and evidentiary logging. Vendors that can surface variance root causes inside minutes, rather than days, are winning bake-offs, suggesting that fraud analytics will continue enlarging its slice of the AI-Powered Payroll Analytics market share over the forecast horizon.
Complete Report Scope:
- By Component
- Software
- Services
- Implementation Services
- Consulting Services
- Support and Maintenance Services
- By Analytics Type
- Predictive Payroll Analytics
- Automated Compliance and Risk Analytics
- Payroll Fraud and Anomaly Detection
- AI?Optimized Workforce Cost Modeling
- AI?Driven Pay Equity and Compensation Analytics
- Other Analytics Type
- By Deployment Mode
- Cloud
- On-Premise
- By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Industry Vertical
- IT and Telecommunications
- BFSI
- Healthcare
- Retail and E-Commerce
- Manufacturing
- Government and Public Sector
- Other Industry Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America generated 38.14% of global revenue in 2025, sustained by California SB 464, New York City Int. 982-A, and Ontario's Working for Workers Four Act that mandate granular pay-data reporting. Vendor consolidation, exemplified by Paychex's USD 4.1 billion acquisition of Paycor, gave buyers access to platforms serving one in eleven U.S. private-sector workers, reinforcing scale economies that accelerate feature rollout.
Asia-Pacific is the fastest-growing territory at 16.51% CAGR. India's 75% payroll-staff shortage and Australia's 43% coverage gap have driven companies toward automation and anomaly detection.Workday's rapid Australian uptake shows regional appetite for AI-infused compliance alerts, while African start-ups such as PaidHR expand footprints across 49 currencies, illustrating untapped frontier opportunities.
Europe records steady adoption propelled by the EU Pay Transparency Directive effective June 2026. SD Worx's acquisition of Paie and RH Solutions in February 2026 increased its French SME client base by 1,100 accounts, signaling intensified mid-market competition. South America and the Middle East and Africa remain early-stage but are seeing cloud-first entrants plug into volatile currency zones and fragmented tax landscapes, adding long-tail momentum to the AI-Powered Payroll Analytics market.
- Automatic Data Processing, Inc.
- Paychex, Inc.
- Paycom Software, Inc.
- Ceridian HCM Holding Inc.
- Paycor HCM, Inc.
- Intuit Inc.
- Workday, Inc.
- Gusto, Inc.
- Rippling People Center, Inc.
- Zenefits LLC
- BambooHR LLC
- UKG Inc.
- Oracle Corporation
- SAP SE
- Ramco Systems Limited
- Zoho Corporation Private Limited
- Deel, Inc.
- Papaya Global Ltd.
- Neeyamo Enterprise Solutions Private Limited
- Namely Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Cloud-Based Payroll Suites
- 4.2.2 Increasing Regulatory Complexity in Multi-Country Payroll
- 4.2.3 Growing Demand for Real-Time Payroll Insights to Improve Workforce Planning
- 4.2.4 AI-Driven Fraud Detection and Payroll Compliance Monitoring
- 4.2.5 Rising Venture Capital Funding Into HR Tech Start-Ups
- 4.2.6 Integration of Payroll Analytics With Financial Wellness Programs
- 4.3 Market Restraints
- 4.3.1 Data Privacy and Cross-Border Data Transfer Restrictions
- 4.3.2 Shortage of Payroll Data Science Talent
- 4.3.3 Legacy Payroll Infrastructure in Large Enterprises
- 4.3.4 High Initial Integration Costs for SMEs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.1.2.1 Implementation Services
- 5.1.2.2 Consulting Services
- 5.1.2.3 Support and Maintenance Services
- 5.2 By Analytics Type
- 5.2.1 Predictive Payroll Analytics
- 5.2.2 Automated Compliance and Risk Analytics
- 5.2.3 Payroll Fraud and Anomaly Detection
- 5.2.4 AI?Optimized Workforce Cost Modeling
- 5.2.5 AI?Driven Pay Equity and Compensation Analytics
- 5.2.6 Other Analytics Type
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-Premise
- 5.4 By Organization Size
- 5.4.1 Small and Medium Enterprises (SMEs)
- 5.4.2 Large Enterprises
- 5.5 By Industry Vertical
- 5.5.1 IT and Telecommunications
- 5.5.2 BFSI
- 5.5.3 Healthcare
- 5.5.4 Retail and E-Commerce
- 5.5.5 Manufacturing
- 5.5.6 Government and Public Sector
- 5.5.7 Other Industry Verticals
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 Australia
- 5.6.4.5 South Korea
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Automatic Data Processing, Inc.
- 6.4.2 Paychex, Inc.
- 6.4.3 Paycom Software, Inc.
- 6.4.4 Ceridian HCM Holding Inc.
- 6.4.5 Paycor HCM, Inc.
- 6.4.6 Intuit Inc.
- 6.4.7 Workday, Inc.
- 6.4.8 Gusto, Inc.
- 6.4.9 Rippling People Center, Inc.
- 6.4.10 Zenefits LLC
- 6.4.11 BambooHR LLC
- 6.4.12 UKG Inc.
- 6.4.13 Oracle Corporation
- 6.4.14 SAP SE
- 6.4.15 Ramco Systems Limited
- 6.4.16 Zoho Corporation Private Limited
- 6.4.17 Deel, Inc.
- 6.4.18 Papaya Global Ltd.
- 6.4.19 Neeyamo Enterprise Solutions Private Limited
- 6.4.20 Namely Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 情緒分析:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 情感市場規模、佔有率和成長分析:按解決方案類型、部署模式、應用、最終用戶和地區分類-2026-2033 年產業預測
 情緒分析市場:依技術、組件、部署模式和最終用戶分類-2026-2032年全球市場預測
 2026年全球情感人工智慧市場報告2026年全球情緒分析市場報告
 情感人工智慧市場:策略性洞察與預測(2026-2031)
 2025-2029年全球人工智慧情緒分析平台市場
 情感分析市場規模、佔有率和成長分析(按類型、部署類型、企業規模、應用、最終用戶和地區分類)-2026-2033年產業預測人工智慧情感分析平台市場規模、佔有率、成長及全球產業分析:依類型、應用和地區劃分的洞察,以及2024-2032年預測
 情緒分析:全球市場佔有率和排名、總收入和需求預測(2025-2031年)