


 |
市場調查報告書
商品編碼
2101604
農藥殘留檢測市場:商機、成長要素、產業趨勢分析及2026-2035年預測Pesticide Residue Testing Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球農藥殘留檢測市場預計到 2025 年將達到 40 億美元,年複合成長率為 5%,到 2035 年將達到 87 億美元。
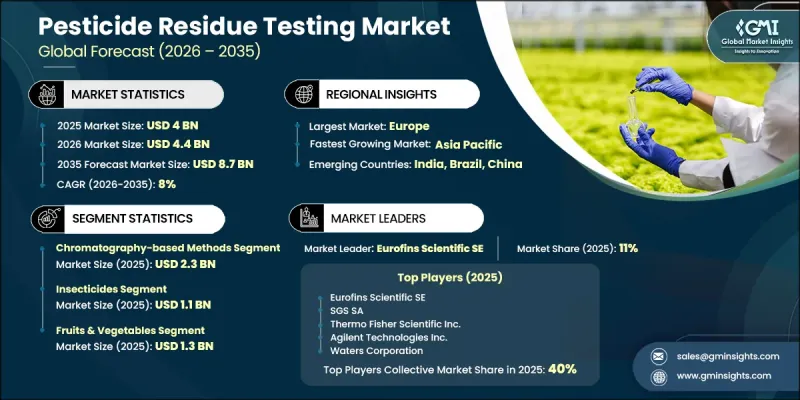
農藥殘留檢測市場的成長主要受日益嚴格的食品安全法規、全球食品貿易的擴張以及消費者對食品品質和安全意識的提高所驅動。監管機構不斷加強對食品中農藥殘留的監測要求,從而持續推動對先進檢測材料和分析解決方案的需求。對檢測設施基礎設施的持續投資、法律規範的加強以及農業貿易的擴張,持續支撐著多個地區的市場發展。同時,在成熟市場,檢測效率的提高、分析方法標準化的進步以及法規結構的改善也促進了市場的發展。技術進步透過提高殘留分析的速度、準確性和可及性,也為市場擴張做出了貢獻。檢測實驗室擴大採用快速篩檢技術、先進的分析平台和數位化檢查室管理系統來提高營運效率。隨著更廣泛的食品安全監測、品質保證和環境評估變得日益重要,農藥殘留檢測的範圍不斷擴大,超越了傳統的農業應用,為全球農藥殘留檢測市場創造了更多長期發展機會。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 40億美元 |
| 預測金額 | 87億美元 |
| 複合年成長率 | 5% |
預計到2025年,層析法市場規模將達23億美元。這些分析技術憑藉其卓越的靈敏度、高分析準確度和單次分析即可檢測多種農藥化合物的能力,持續引領市場。其久經考驗的可靠性和穩定的性能,使層析法成為食品安全檢測實驗室進行法規遵循測試和殘留物確證分析的首選方法。
預計到2025年,農藥市場規模將達11億美元。隨著監管機構持續重視整個食品供應鏈中農藥殘留的監測,該領域保持主導地位。殘留物法規的不斷更新、更嚴格的合規要求以及持續的監測項目,正推動著各類農產品對農藥殘留檢測需求的持續成長。
預計北美農藥殘留檢測市場規模將從2025年的12億美元成長到2035年的22億美元。該地區市場成長的驅動力包括完善的食品安全監測體系、全面的法律規範以及嚴格的進口合規要求。隨著整個食品供應鏈檢測活動的持續擴展,以及消費者對食品品質和安全監管期望的不斷提高,北美地區對農藥殘留檢測試劑和分析解決方案的需求持續強勁。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 加強全球最大殘留限量法規及全面實施食品安全措施
- 跨境食品貿易和出口認證要求的擴大
- 消費者對有機和無農藥食品的需求日益成長
- 產業潛在風險與挑戰
- 先進分析設備高成本
- 熟練的分析化學家短缺,以及認證實驗室能力不足
- 市場機遇
- 推廣在田間和入境點廣泛使用攜帶式快速殘留物檢測進行篩檢。
- 擴大環境中農藥殘留的檢測範圍
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 測試技術公司
- 未來市場趨勢
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依測試技術分類,2022-2035年
- 基於層析法的方法
- 基於免疫檢測的方法
- 光譜學方法
- 基於酵素抑制的方法
- 生物感測器和快速檢測套組基礎
- 其他(新興技術和混合技術)
第6章 市場估計與預測:依農藥類型分類,2022-2035年
- 除草劑
- 殺蟲劑
- 消毒劑
- 殺蟎劑
- 殺線蟲劑
- 植物生長調節劑(PGRs)
- 其他
第7章 市場估算與預測:依食品與樣品矩陣分類,2022-2035年
- 水果和蔬菜
- 穀物、豆類和豆科植物
- 肉類/家禽
- 乳製品
- 加工食品和飲料
- 香辛料、草藥和乾燥製品
- 水樣本和環境樣品
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第9章:公司簡介
- Eurofins Scientific SE
- SGS SA
- Thermo Fisher Scientific Inc.
- Agilent Technologies Inc.
- Waters Corporation
- Bureau Veritas SA
- Intertek Group plc
- Shimadzu Corporation
- LGC Group
- Fera Science Ltd
- Merieux NutriSciences
- Food Safety Net Services(FSNS)
- Neogen Corporation
- Romer Labs
- Charm Sciences Inc.
The Global Pesticide Residue Testing Market was valued at USD 4 billion in 2025 and is estimated to grow at a CAGR of 5% to reach USD 8.7 billion by 2035.
Growth in the pesticide residue testing market is driven by increasingly stringent food safety regulations, expanding global food trade, and rising consumer awareness regarding food quality and safety. Regulatory authorities continue strengthening monitoring requirements for pesticide residues in food products, creating sustained demand for advanced testing materials and analytical solutions. Ongoing investments in laboratory infrastructure, improved regulatory oversight, and expanding agricultural trade continue to support market development across several regions. Meanwhile, mature markets are advancing through improved testing efficiency, greater method standardization, and evolving regulatory frameworks. Technological advancements are also contributing to market expansion by improving the speed, accuracy, and accessibility of residue analysis. Laboratories are increasingly adopting rapid screening technologies, advanced analytical platforms, and digital laboratory management systems to enhance operational performance. The scope of pesticide residue testing continues to expand beyond traditional agricultural applications as greater emphasis is placed on broader food safety monitoring, quality assurance, and environmental assessment, creating additional long-term opportunities for the global pesticide residue testing market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $4 Billion |
| Forecast Value | $8.7 Billion |
| CAGR | 5% |
The chromatography-based methods segment generated USD 2.3 billion in 2025. These analytical technologies continue to lead the market because they provide exceptional sensitivity, high analytical accuracy, and the ability to detect multiple pesticide compounds within a single analysis. Their proven reliability and consistent performance have established chromatography-based methods as the preferred approach for regulatory compliance testing and confirmatory residue analysis across food safety laboratories.
The insecticides segment captured USD 1.1 billion in 2025. The segment maintains its leading position because regulatory agencies continue to prioritize monitoring of insecticide residues throughout the food supply chain. Ongoing updates to residue regulations, stricter compliance requirements, and continuous monitoring programs are driving sustained demand for insecticide residue testing across a wide range of agricultural products.
North America Pesticide Residue Testing Market is projected to grow from USD 1.2 billion in 2025 to USD 2.2 billion by 2035. Market growth across the region is supported by well-established food safety monitoring programs, comprehensive regulatory oversight, and stringent import compliance requirements. Continuous expansion of testing activities throughout the food supply chain, combined with increasing regulatory expectations for food quality and consumer safety, continues to strengthen demand for pesticide residue testing materials and analytical solutions across North America.
Major companies operating in the global pesticide residue testing market include Eurofins Scientific SE, SGS SA, Thermo Fisher Scientific Inc., Agilent Technologies Inc., Waters Corporation, Bureau Veritas SA, Intertek Group plc, Shimadzu Corporation, LGC Group, Fera Science Ltd, Merieux NutriSciences, Food Safety Net Services (FSNS), Neogen Corporation, Romer Labs, and Charm Sciences Inc. Companies operating in the pesticide residue testing market are strengthening their competitive position by expanding analytical capabilities and investing in advanced testing technologies that improve accuracy, efficiency, and regulatory compliance. Many organizations continue to increase research and development activities to enhance testing performance and support evolving food safety requirements. Manufacturers and service providers are also improving laboratory infrastructure, adopting digital laboratory management systems, and optimizing operational workflows to increase productivity and testing capacity. Strategic collaborations with regulatory agencies, food manufacturers, and laboratory networks help expand market reach and strengthen customer relationships.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Testing Technology
- 2.2.2 Pesticide Type
- 2.2.3 Food & Sample Matrix
- 2.2.4 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.5 Future outlook and strategic recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Tightening global mrl regulations & food safety enforcement
- 3.2.1.2 Growth in cross-border food trade & export certification requirements
- 3.2.1.3 Rising consumer demand for organic & pesticide-free food
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost of advanced analytical instruments
- 3.2.2.2 Shortage of skilled analytical chemists & accredited lab capacity
- 3.2.3 Market opportunities
- 3.2.3.1 Growth of portable & rapid residue testing for field-level & point-of-entry screening
- 3.2.3.2 Expansion of environmental pesticide residue testing
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By Testing Technology
- 3.9 Future market trends
- 3.10 Patent landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Testing Technology, 2022-2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 Chromatography-Based Methods
- 5.3 Immunoassay-Based Methods
- 5.4 Spectroscopy-Based Methods
- 5.5 Enzyme Inhibition-Based Methods
- 5.6 Biosensor & Rapid Test Kit-Based
- 5.7 Others (Emerging & Hybrid)
Chapter 6 Market Estimates and Forecast, By Pesticide Type, 2022-2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Herbicides
- 6.3 Insecticides
- 6.4 Fungicides
- 6.5 Acaricides
- 6.6 Nematicides
- 6.7 Plant Growth Regulators (PGRs)
- 6.8 Others
Chapter 7 Market Estimates and Forecast, By Food & Sample Matrix, 2022-2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Fruits & Vegetables
- 7.3 Cereals, Grains & Pulses
- 7.4 Meat & Poultry
- 7.5 Dairy Products
- 7.6 Processed Food & Beverages
- 7.7 Spices, Herbs & Dried Products
- 7.8 Water & Environmental Samples
- 7.9 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022-2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East and Africa
Chapter 9 Company Profiles
- 9.1 Eurofins Scientific SE
- 9.2 SGS SA
- 9.3 Thermo Fisher Scientific Inc.
- 9.4 Agilent Technologies Inc.
- 9.5 Waters Corporation
- 9.6 Bureau Veritas SA
- 9.7 Intertek Group plc
- 9.8 Shimadzu Corporation
- 9.9 LGC Group
- 9.10 Fera Science Ltd
- 9.11 Merieux NutriSciences
- 9.12 Food Safety Net Services (FSNS)
- 9.13 Neogen Corporation
- 9.14 Romer Labs
- 9.15 Charm Sciences Inc.

 全球農藥殘留檢測市場規模、佔有率、趨勢及成長分析報告(2026-2034年)
 農業檢驗市場規模、佔有率和趨勢分析報告:按樣本、類型、技術、最終用途、地區和細分市場預測(2026-2033 年)
 食品和農業檢測、檢驗和認證:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)農業檢驗:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)馬來西亞和越南花卉栽培材料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 農業檢驗市場:2026-2032年全球市場預測(按檢驗類型、作物類型、技術、服務形式、最終用戶和應用分類)
 農業用品直銷市場:未來預測(至2034年)-依產品類型、平台類型、經營模式、作物類型、農場規模、最終用戶、通路和地區進行分析
 農業檢驗市場規模、佔有率、趨勢和預測:按樣本、技術、應用和地區分類(2026-2034 年)
 2026年全球農業材料市場報告
 農業檢驗市場:依樣本數和地區分類