


 |
市場調查報告書
商品編碼
2107336
層析法市場:依產品類型、層析法設備類型、液相層析法、組成、固定相形式、最終用戶和地區分類:趨勢與預測至2035年Chromatography Market By Type of Product, Type of Chromatography Instrument, Type of Liquid Chromatography, Component, Stationary Phase Format, End User, and Geographical Regions - Trends and Forecast Till 2035 |
||||||

層析法市場概覽
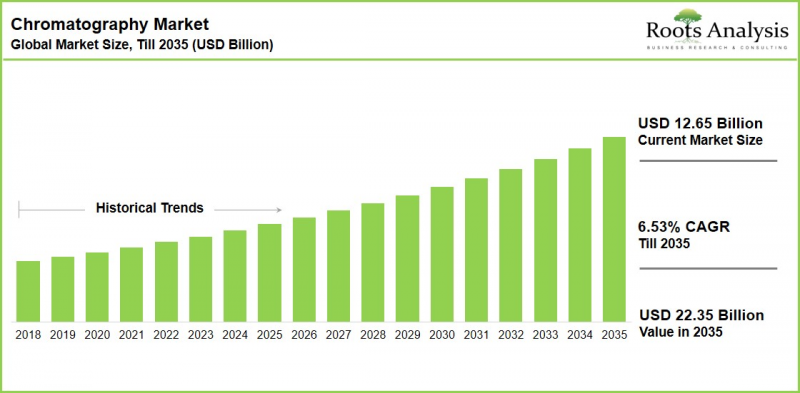
全球層析法市場預計將從今年的 126.5 億美元成長到 2035 年的 223.5 億美元,預測期內複合年成長率約為 6.53%。
層析法市場:成長與趨勢
層析法由米哈伊爾·茲維特於20世紀初發明,至今仍是分離、鑑定和純化複雜混合物中各組分的基本分析方法。此技術的工作原理是將待測物分配到流動相(液體或氣體)和固定相之間。此後,這項原理被廣泛應用於各種儀器和耗材的開發,服務於製藥、生物技術、化學、食品和石油化工等行業的終端用戶。
在製藥和生物技術行業,層析法的需求正在不斷成長。這項需求主要源自於層析法在轉化研究、精準腫瘤學以及疫苗和病毒載體開發中的定性和定量分析方面發揮的關鍵作用。預計層析法在法醫學和診斷領域也將得到更廣泛的應用。持續的平台創新不斷拓展其在研發領域的應用範圍,也為此成長提供了支持。
成長要素:支持市場擴張的因素
持續的技術創新是成長要素。產業公司正在整合人工智慧、先進的檢測系統和小型化技術,以拓展層析法在科研和工業領域的應用。同時,連續層析法平台的處理能力不斷提升,每次分析的運作成本也顯著降低。
同時,隨著環保意識的增強,對永續消耗品(包括環保溶劑和二氧化碳等超臨界流體)的需求正在加速成長,具有卓越環保效率的產品線正成為關鍵的商業性差異化因素。
此外,透過併購進行的產業重組正在推動成長。過去五年,層析法儀器製造商的併購活動以每年約4%的速度成長。企業越來越傾向於透過收購來擴展其儀器和耗材產品組合,而不是依賴內部成長。近期案例包括沃特世(Waters)與BD生物科學(BD Biosciences)的合併、海法實驗室(Haifa Labs)對Lucidity的收購,以及島津公司(Shimadzu Corporation)參與的Alsakim與Biomaneo的整合。
市場挑戰:阻礙進展的主要障礙
層析法面臨其他分離技術的競爭,這些技術在特定應用中能夠提供更快的速度或更高的通量,例如結晶、超過濾、膜過濾和高壓複性。特別是聯用系統,例如液相層析質譜聯用(LC-MS)和氣相層析質譜聯用(GC-MS),更為複雜,需要專業的知識來進行方法開發、樣品製備和數據分析。熟練專業人員的匱乏仍然是限制這些技術應用普及的因素,尤其是在新興市場。
層析法市場:關鍵洞察
本報告對層析法市場現狀進行了詳細分析,重點關注行業內的潛在成長機會,尤其從分銷商和通路合作夥伴的角度出發。主要發現包括:
- 與臨床診斷領域(沃特世和BD)的整合:沃特世已同意與BD的生物科學和診斷解決方案業務合併,旨在將液相層析法-質譜(LC-MS)整合到自動化臨床診斷工作流程中。
- 區域生物程序擴張(島津公司和 Sepragen):島津公司已獲得 Sepragen 生物程序層析法系統的獨家經銷權,以佔領印度、日本、韓國和東南亞的商業生物製造下游加工市場。
- 專用上游生物製程柱(沃特世):沃特世推出了專用的 Protein A親和性和柱,旨在用於生物製藥開發中的即時監測,從而加速下游分析方法的最佳化。
- 區域網路擴展(Testa Analytical 和 Maze & Company):Testa Analytical 與 Maze & Company 合作,旨在擴大法語歐洲和北非地區高精度分析液體流量測量設備的供應。
- 向預包裝和永續耗材過渡:供應商優先考慮預包裝色譜柱和生物基/可生物分解的填充材,以消除勞動密集型的手動色譜柱填充,並與公司的綠色化學計劃保持一致。
- 從硬體到工作流程的策略:市場領先的公司正在從銷售單一 LC/GC 儀器轉向提供 AI 驅動的自動化綜合生態系統,整合聯用系統(LC-MS/GC-MS)、專用色譜柱和合規軟體。
層析法市場細分
Roots Analysis 根據以下參數對全球層析法市場機會進行分類:
層析法產品類型
- 裝置
- 消耗品
- 其他產品
層析法儀類型
- 液相層析法儀
- 氣相層析法儀
- 其他層析法設備
液相層析法法
- 高效液相層析(HPLC)
- 超高效液相層析(UHPLC)
- 尺寸排阻層析法
- 快速層析法
- 其他方法
層析法組分類型
- 靜止期
- 流動相
按固定相類型
- 預注管柱
- 瓶子/散裝樹脂
- 其他格式
最終用戶
- 製藥和生物技術產業
- 學術和研究機構
- 其他
按地區
- 北美洲
- 歐洲
- 亞太地區
- 其他地區
層析法市場:關鍵細分市場分析
設備領域是市場的主要驅動力。
目前,儀器設備在整個層析法市場中佔據最大佔有率。這一高佔有率反映了儀器在分離、純化和鑑定複雜混合物中的組分方面發揮的核心作用,涵蓋從常規分析流程到高級分析流程的各個環節。對更自動化和小型化平台的持續投資預計將維持該領域的領先地位。
儘管儀器設備領域佔據市場主導地位,但包括色譜柱、樹脂、流動相試劑和其他組件在內的耗材領域預計在預測期內將以更高的複合年成長率成長。這種前所未有的成長是由對客製化和永續耗材形式(例如可生物分解的填充材)日益成長的需求所驅動的。
液相層析法設備佔據市場主導地位。
目前,液相層析法系統佔據最大的市場佔有率。這一成長歸功於其能夠有效分離極性化合物和熱不穩定化合物,而這些化合物難以用氣相層析法分離。在液相層析法領域,高效液相層析(HPLC)仍然是主導技術,尤其因為它在滿足新藥認證的監管級分析要求方面發揮核心作用。
然而,隨著實驗室對更短的分析時間、更高的解析度和更高的靈敏度提出更高的要求,超高效液相層析(UHPLC)預計將在液相層析法技術中實現最高的複合年成長率(CAGR)。另一方面,氣相層析法預計在預測期內也將實現最高的複合年成長率。這種高成長率得益於氣相層析系統相對較高的成本效益和易用性。
雖然固定階段市場佔據主導地位,但移動階段市場正在迅速發展。
在層析法的各個組成部分中,固定相佔據最大的市場佔有率。這種主導地位反映了固定相在實現高解析度、高選擇性和低成本分離方面發揮的核心作用。預計流動相市場在預測期內將以更高的複合年成長率成長。這一可觀的成長得益於配方技術的進步以及與液相色譜-質譜聯用(LC-MS)和氣相色譜-質譜聯用(GC-MS)等聯用技術的緊密結合,這些技術正在提升流動相在整體分析性能中的作用。
預注管柱佔據市場主導地位。
按規格分類,預注管柱佔據最大的市場佔有率,並處於主導地位。尤其值得一提的是,預計該細分市場在預測期內將實現最高的複合年成長率。這項優勢主要源自於預注管柱減少了手動裝樣所需的時間和精力,從而縮短了層析法分離的周轉時間。
製藥和生物技術產業是市場的主要驅動力。
製藥和生物技術公司在層析法市場銷售額方面佔據最大佔有率。這一高佔有率源於該技術在藥物研發和品管中發揮的關鍵作用,它可用於分離、鑑定和純化生物分子和化合物。
學術和研究機構是成長最快的終端用戶群體,預計在預測期內將保持最高的複合年成長率。這一潛在成長主要得益於蛋白質體學、代謝體學和合成生物學等領域研究的不斷拓展,這些研究需要靈活、高解析度的分析能力。
雖然北美仍保持領先地位,但亞太地區正在崛起成為成長最快的地區。
根據我們的市場預測,到 2035 年,北美預計將佔據全球層析法市場收入的最大佔有率。這一最高成長是由成熟的儀器和耗材供應商高度集中、成熟的研究基礎設施以及人工智慧賦能和小型化層析法系統的早期應用所驅動的。
預計亞太地區在預測期內將以更高的複合年成長率成長。這一成長主要得益於中國、印度和日本國內製藥業的擴張,以及該地區生物製藥合約研究組織(CRO)和合約受託製造廠商(CMO)數量的成長,而這兩者都高度依賴層析法進行分析和純化。
層析法市場主要公司示例
- Agilent Technologies
- Bio-Rad Laboratories
- Gilson
- JASCO
- MilliporeSigma
- Revvity(原名 PerkinElmer)
- Sartorius
- Shimadzu Scientific Instruments
- Thermo Fisher Scientific
層析法市場:研究範圍
- 市場規模和機會分析:按產品類型、儀器類型、液相層析法方法、組成、固定相形式、最終用戶和地區進行詳細的收入分析。
- 競爭格局評估:市場分析提供了約 90 家設備製造商和約 95 家耗材製造商的信息,按公司規模、總部所在地、主要產品和成立年份進行分類。
- 公司簡介:主要公司的詳細介紹。這些簡介涵蓋公司概況、產品系列和近期策略措施。
- 專利分析:我們將檢驗與層析法設備和耗材相關的專利申請和已註冊專利,並按司法管轄區、申請人類型和公開趨勢進行分類。
- 併購:本章對層析法設備和耗材市場的併購活動進行了全面評估。它按交易類型、年份、公司所有權結構和地區(包括洲際交易、洲內交易、區域交易和國際交易)分析了交易趨勢。
- 市場影響分析:本分析全面闡述了影響短期和長期市場變化的促進因素、限制因素、機會和挑戰。
本報告解答的主要問題
- 目前哪些公司在層析法市場處於領先地位?
- 在層析法市場中,哪個地區佔據最大的市場佔有率?哪個地區成長速度最快?
- 目前影響層析法應用的主要趨勢是什麼?
- 到 2035 年,哪些因素將對市場發展產生最大影響?
- 層析法供應商面臨的主要障礙有哪些?
- 目前市場規模是多少?預計未來市場規模為何?
- 預計市場在預測期內將維持怎樣的複合年成長率?
- 市場機會在產品、設備和最終用戶領域是如何分佈的?
購買本報告的理由
本報告專為考慮進入層析法市場的經銷商、通路合作夥伴和業務發展團隊編寫。
- 我們提供整體市場和每個細分市場的全面收入預測,使其對現有企業和新參與企業都很有用。
- 我們為相關人員提供關於市場促進因素、阻礙因素、機會和挑戰的清晰展望,以支持數據驅動的決策。
- 我們為企業提供支持,幫助他們識別和評估層析法相關領域的新機會。
- 我們為新參與企業提供必要的市場環境洞察,以建立可靠的打入市場策略。
- 我們透過對機會進行量化、通用的理解,來加強相關人員之間的溝通。
目錄
第1章:序言
第2章:調查方法
第3章 經濟及其他項目特定考量因素
第4章執行摘要
第5章:引言
第6章:層析法設備供應商市場趨勢
第7章層析法設備供應商:企業競爭力分析
第8章:層析法耗材供應商市場趨勢
第9章:公司簡介
- 章節概要
- Agilent Technologies
- Bio-Rad Laboratories
- PerkinElmer
- Sartorius
- Shimadzu
- Thermo Fisher Scientific
第10章 專利分析
第11章併購
第12章 市場影響分析:促進因素、阻礙因素、機會與挑戰
第13章:全球層析法市場
第14章:層析法市場:依產品類型分類的分佈(至2035年)
第15章層析法市場:依層析法設備類型分類的分佈
第16章:層析法市場:依耗材類型分類的分佈(至2035年)
第17章層析法市場:依最終用戶分類
第18章層析法市場:區域分佈
第19章 結論
第20章:高階主管洞見
第21章附錄1:表格形式數據
第22章 附錄2:公司與組織列表
CHROMATOGRAPHY MARKET: OVERVIEW
As per Roots Analysis, the global chromatography market is estimated to grow from USD 12.65 billion in the current year to USD 22.35 billion by 2035, reflecting a compound annual growth rate (CAGR) of approximately 6.53% during the forecast period.
Chromatography Market: Growth and Trends
Chromatography remains the analytical backbone for separating, identifying, and purifying components within complex mixtures, since its introduction by Mikhail Tsvet in the early twentieth century. The method works by partitioning analytes between a moving mobile phase, liquid or gaseous, and a fixed stationary phase. This is a principle that has since been engineered into a wide family of instruments and consumables serving pharmaceutical, biotechnology, chemical, food, and petrochemical end users.
Demand for chromatography has increased across the pharmaceutical and biotechnology industries. This demand is driven by its essential role in qualitative and quantitative analysis for translational research, precision oncology, and vaccine and viral vector development. Looking ahead, chromatography is expected to see broader adoption in forensics and diagnostics. This expansion is supported by ongoing platform innovations that expand its applications across research and industrial development.
Growth Drivers: Factors Fueling Market Expansion
Continuous technology innovation is the primary growth factor of the market. Industry players are aiming to integrate artificial intelligence, advanced detection systems, and miniaturized formats to widen chromatography's applicability across research and industrial settings. On the other hand, the continuous chromatography platforms have improved throughput and lowered per-run operating costs.
In parallel, rising environmental scrutiny has accelerated demand for sustainable consumables, including green solvents and supercritical fluids such as carbon dioxide, positioning eco-efficient product lines as a meaningful commercial differentiator.
Further, consolidation activities, such as mergers and acquisitions are reinforcing the growth momentum. Merger and acquisition activity among chromatography providers has increased by approximately 4% annually over the past five years. Companies are increasingly using acquisitions to expand their instruments and consumable portfolios rather than relying on organic growth. Recent examples include the Waters and BD Biosciences merger, Hypha Labs' acquisition of Lucidity, and the Shimadzu-linked combination of Alsachim and Biomaneo.
Market Challenges: Critical Barriers Hindering Progress
Chromatography faces growing competition from alternative separation techniques, such as crystallization, ultrafiltration, membrane filtration, and high-pressure refolding, which offer faster or higher-throughput performance for specific applications. Notably, hyphenated systems, such as LC-MS and GC-MS, are more complex and require specialized expertise for method development, sample preparation, and data analysis. Limited access to skilled professionals continues to restrict their adoption, particularly in emerging markets.
Chromatography Market: Key Insights
The report delves into the current state of the chromatography market and identifies potential growth opportunities within the industry, particularly from a distributor and channel-partner perspective. Some key findings include:
- Clinical Diagnostics Integration (Waters & BD): Waters agreed to merge with BD's Biosciences & Diagnostic Solutions Business to embed Liquid Chromatography-Mass Spectrometry (LC-MS) into automated clinical diagnostics workflows.
- Regional Bioprocess Expansion (Shimadzu & Sepragen): Shimadzu secured exclusive distribution for Sepragen's bioprocess chromatography systems to capture commercial biomanufacturing downstream processing in India, Japan, South Korea, and Southeast Asia.
- Targeted Upstream Bioprocess Columns (Waters): Waters launched specialized Protein A affinity columns designed for real-time monitoring in biologic drug development to speed up downstream method optimization.
- Geographic Network Growth (Testa Analytical & Mazet & Co): Testa Analytical partnered with Mazet & Co to expand access to precision analytical liquid flow measurement devices across French-speaking Europe and North Africa.
- Shift to Prepacked & Sustainable Consumables: Vendors are prioritizing prepacked columns and bio-based/biodegradable packing media to eliminate labor-intensive manual column packing and align with corporate green chemistry initiatives.
- Hardware-to-Workflow Strategy: Market leaders are shifting from selling standalone LC/GC instruments toward offering complete, AI-automated ecosystems that bundle hyphenated systems (LC-MS/GC-MS), specialized columns, and compliance software.
Chromatography Market Segments
Roots Analysis segments the global chromatography opportunity across the following parameters:
By Type of Chromatography Product
- Instruments
- Consumables
- Other Products
By Type of Chromatography Instrument
- Liquid Chromatography Instruments
- Gas Chromatography Instruments
- Other Chromatography Instruments
By Type of Liquid Chromatography
- High Performance Liquid Chromatography (HPLC)
- Ultra-High Performance Liquid Chromatography (UHPLC)
- Size-Exclusion Chromatography
- Flash Chromatography
- Other Techniques
By Type of Chromatography Component
- Stationary Phase
- Mobile Phase
By Format of Stationary Phase
- Prepacked Columns
- Bottles / Bulk Resins
- Other Formats
By End User
- Pharmaceutical and Biotechnology Industries
- Academic and Research Institutes
- Other End Users
By Geographical Regions
- North America
- Europe
- Asia-Pacific
- Rest of the World
Chromatography Market: Key Segments Insight
Instruments Segment Leads the Market
Instruments currently account for the highest share of total chromatography market share. This highest share reflects their central role in separating, purifying, and identifying components within complex mixtures across both routine and advanced analytical workflows. Continued investment in more automated and miniaturized platforms is expected to maintain the dominance of this segment.
While the instruments segment is dominating the market, the consumables segment, comprising columns, resins, and mobile-phase reagents, is expected to grow at a higher CAGR during the forecast period. This unprecedented growth is due to the growing demand for customized and sustainable consumable formats such as biodegradable packing materials.
Liquid Chromatography Instruments Dominate Market
Liquid chromatography instruments currently capture highest share of the market. This growth is due to its effectiveness in separating polar and thermolabile compounds that are poorly suited to gas-phase methods. Within liquid chromatography specifically, HPLC remains the dominant technique, given its central role in meeting regulatory-grade analytical requirements for new drug approvals.
However, UHPLC is expected to grow fastest among liquid chromatography techniques, at a higher CAGR, as laboratories prioritize faster run times, sharper resolution, and greater sensitivity. On the other hand, gas chromatography is expected to grow at the fastest CAGR during the forecast period. This highest growth is supported by the relative cost-efficiency and ease of use of gas-based systems.
Stationary Phase Leads the Market, While Mobile Phase Gains Momentum
Among chromatography components, the stationary phase segment holds the largest share of the market. This dominance reflects its central function in achieving high-resolution, selective, and cost-efficient separations. The mobile phase segment is forecast to grow at a higher CAGR during the forecast period. This lucrative growth is driven by formulation advances and tighter integration with hyphenated techniques such as LC-MS and GC-MS that have raised mobile phase role in overall analytical performance.
Prepacked Columns Dominate Market
By format, prepacked columns lead by occupying the largest share of the market. Notably, this segment also registers the fastest CAGR during the forecast period. This dominance is largely because pre-assembled columns eliminate the time and labor associated with manual packing, shortening turnaround for chromatographic separations.
Pharmaceutical and Biotechnology Industries Dominate the Market
Pharmaceutical and biotechnology companies account for the largest share of chromatography market revenue. This highest share is driven by the technique's essential role in separating, identifying, and purifying biomolecules and chemical compounds during drug development and quality control.
Academic and research institutes represent the fastest growing end-user segment, at a projected higher CAGR during the forecast period. This potential growth is due to the expanding proteomics, metabolomics, and synthetic biology research that demands flexible, high-resolution analytical capacity.
North America Leads, While Asia-Pacific Emerges as the Fastest-Growing Region
According to our market projections, North America is likely to hold the largest share of global chromatography market revenue through 2035. This highest growth is supported by a dense concentration of established instrument and consumable providers, mature research infrastructure, and early adoption of AI-enabled and miniaturized chromatography systems.
Asia-Pacific is expected to grow at a higher CAGR during the forecast period. This growth is driven by expanding domestic pharmaceutical manufacturing in China, India, and Japan, along with the region's growing biologics CRO and CMO base, both of which rely heavily on chromatography for analytical and purification support.
Example Players in Chromatography Market
- Agilent Technologies
- Bio-Rad Laboratories
- Gilson
- JASCO
- MilliporeSigma
- Revvity (Previously known as PerkinElmer)
- Sartorius
- Shimadzu Scientific Instruments
- Thermo Fisher Scientific
CHROMATOGRAPHY MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: In-depth revenue analysis across product type, instrument type, liquid chromatography technique, component, stationary phase format, end user, and geography.
- Competitive Landscape Assessment: The market landscape analysis provides information on close to 90 instrument providers and roughly 95 consumable providers by company size, headquarters location, product focus, and year of establishment.
- Company Profiles: Detailed profiles of leading players, covering company overview, product portfolio, and recent strategic initiatives.
- Patent Analysis: Review of patents filed and granted related to chromatography instruments and consumables, by jurisdiction, applicant type, and publication trend.
- Mergers and Acquisitions: A comprehensive assessment of merger and acquisition activity in the chromatography instruments and consumables market. The chapter analyzes deal trends by type, year, company ownership, and geography, including intercontinental, intracontinental, local, and international transactions.
- Market Impact Analysis: Consolidated view of drivers, restraints, opportunities, and challenges shaping near- and long-term market evolution.
Key Questions Answered in this Report
- Which companies currently lead the chromatography market?
- Which region holds the largest chromatography market share, and which is growing fastest?
- What are the key trends shaping chromatography adoption today?
- What factors will most influence market evolution through 2035?
- What are the primary barriers facing chromatography providers?
- What is the current and projected market size?
- What CAGR is the market expected to sustain through the forecast period?
- How is market opportunity distributed across product, instrument, and end-user segments?
Reasons to Buy this Report
This report has been specifically developed to support distributors, channel partners, and business development teams evaluating entry into the chromatography market.
- Provides comprehensive revenue projections for the overall market and each sub-segment, useful to both incumbents and new entrants.
- Gives stakeholders a clear view of drivers, restraints, opportunities, and challenges to support data-driven decision-making.
- Helps businesses identify and evaluate emerging opportunities across chromatography-adjacent sectors.
- Equips new entrants with the market context needed to build credible go-to-market strategies.
- Strengthens stakeholder communication through a shared, quantified view of the opportunity.
Additional Benefits
- Complementary Insights Pack
- Complementary PPT Insights Pack
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Project Objectives
- 1.3. Scope of the Report
- 1.4. Inclusions and Exclusions
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.3. Project Methodology
- 2.4. Forecast Methodology
- 2.5. Robust Quality Control
- 2.6. Key Market Segmentations
- 2.7. Key Considerations
- 2.7.1. Demographics
- 2.7.2. Economic Factors
- 2.7.3. Government Regulations
- 2.7.4. Supply Chain
- 2.7.5. COVID Impact / Related Factors
- 2.7.6. Market Access
- 2.7.7. Healthcare Policies
- 2.7.8. Industry Consolidation
3. ECONOMIC AND OTHER PROJECT SPECIFIC CONSIDERATIONS
- 3.1. Chapter Overview
- 3.2. Market Dynamics
- 3.2.1. Time Period
- 3.2.1.1. Historical Trends
- 3.2.1.2. Current and Future Estimates
- 3.2.2. Currency Coverage
- 3.2.2.1. Overview of Major Currencies Affecting the Market
- 3.2.2.2. Impact of Currency Fluctuations on the Industry
- 3.2.3. Foreign Exchange Impact
- 3.2.3.1. Evaluation of Foreign Exchange Rates and Their Impact on Market
- 3.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 3.2.4. Recession
- 3.2.4.1. Historical Analysis of Past Recessions and Lessons Learnt
- 3.2.4.2. Assessment of Current Economic Conditions and Potential Impact on the Market
- 3.2.5. Inflation
- 3.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 3.2.5.2. Potential Impact of Inflation on the Market Evolution
- 3.2.1. Time Period
4. EXECUTIVE SUMMARY
5. INTRODUCTION
- 5.1. Chapter Overview
- 5.2. Overview of Chromatography
- 5.3. Principle of Chromatography
- 5.4. Types of Chromatography
- 5.5. Applications of Chromatography
- 5.6. Future Perspectives
- 5.7. Concluding Remarks
6. CHROMATOGRAPHY INSTRUMENTS PROVIDERS MARKET LANDSCAPE
- 6.1. Chapter Overview
- 6.2. Chromatography Instrument Providers: Overall Market Landscape
- 6.2.1. Analysis by Year of Establishment
- 6.2.2. Analysis by Company Size
- 6.2.3. Analysis by Location of Headquarters
- 6.2.4. Analysis by Company Size and Location of Headquarters
- 6.2.5. Analysis by Chromatography Instrument Offered
- 6.2.6. Analysis by Type of Mobile Phase Used
- 6.2.7. Analysis by Type of Chromatography Consumables Offered
- 6.2.8. Analysis by Scale of Operation
- 6.2.9. Analysis by Type of Industry Served
7. CHROMATOGRAPHY INSTRUMENTS PROVIDERS: COMPANY COMPETITIVENESS ANALYSIS
- 7.1. Chapter Overview
- 7.2. Assumptions and Key Parameters
- 7.3. Methodology
- 7.4. Chromatography Instrument Providers: Company Competitiveness Analysis
- 7.4.1. Small Companies Providing Chromatography Instruments
- 7.4.2. Mid-sized Companies Providing Chromatography Instruments
- 7.4.3. Large Companies Providing Chromatography Instruments
- 7.4.4. Very Large Companies Providing Chromatography Instruments
8. CHROMATOGRAPHY CONSUMABLES PROVIDERS MARKET LANDSCAPE
- 8.1. Chapter Overview
- 8.2. Chromatography Consumables Providers: Overall Market Landscape
- 8.2.1. Analysis by Year of Establishment
- 8.2.2. Analysis by Company Size
- 8.2.3. Analysis by Location of Headquarters
- 8.2.4. Analysis by Company Size and Location of Headquarters
- 8.2.5. Analysis by Type of Separation Technique Used
- 8.2.6. Analysis by Type of Solid Phase Offered
- 8.2.7. Analysis by Type of Consumable Format Offered
- 8.2.8. Analysis by Type of Analyte
- 8.2.9. Analysis by Application Area of Chromatography Consumables
9. COMPANY PROFILES
- 9.1. Chapter Overview
- 9.2. Agilent Technologies
- 9.2.1. Company Overview
- 9.2.2. Chromatography Product Portfolio
- 9.2.3. Recent Developments and Future Outlook
- 9.3. Bio-Rad Laboratories
- 9.3.1. Company Overview
- 9.3.2. Chromatography Product Portfolio
- 9.3.3. Recent Developments and Future Outlook
- 9.4. PerkinElmer
- 9.4.1. Company Overview
- 9.4.2. Chromatography Product Portfolio
- 9.4.3. Recent Developments and Future Outlook
- 9.5. Sartorius
- 9.5.1. Company Overview
- 9.5.2. Chromatography Product Portfolio
- 9.5.3. Recent Developments and Future Outlook
- 9.6. Shimadzu
- 9.6.1. Company Overview
- 9.6.2. Chromatography Product Portfolio
- 9.6.3. Recent Developments and Future Outlook
- 9.7. Thermo Fisher Scientific
- 9.7.1. Company Overview
- 9.7.2. Chromatography Product Portfolio
- 9.7.3. Recent Developments and Future Outlook
10. PATENT ANALYSIS
- 10.1. Chapter Overview
- 10.2. Scope and Methodology
- 10.3. Chromatography Instruments and Consumables: Patent Analysis
- 10.3.1. Analysis by Patent Publication Year
- 10.3.2. Analysis by Patent Application Year
- 10.3.3. Analysis of Granted Patents and Patent Applications by Publication Year
- 10.3.4. Analysis by Patent Jurisdiction
- 10.3.5. Analysis by CPC Symbols
- 10.3.6. Analysis by Type of Applicant
- 10.3.7. Leading Industry Players: Analysis by Number of Patents
- 10.3.8. Leading Non-Industry Players: Analysis by Number of Patents
- 10.3.9. Leading Individual Patent Assignees: Analysis by Number of Patents
- 10.4. Chromatography Instruments and Consumables: Patent Benchmarking Analysis
- 10.4.1. Analysis by Patent Characteristics
- 10.5. Chromatography Instruments and Consumables: Patent Valuation
- 10.6. Leading Patents by Number of Citations
11. MERGERS AND ACQUISITIONS
- 11.1. Chapter Overview
- 11.2. Merger and Acquisition Models
- 11.3. Chromatography Instruments and Consumables: Mergers and Acquisitions
- 11.3.1. Analysis by Type of Deal
- 11.3.2. Analysis by Year of Deal
- 11.3.3. Analysis by Company Ownership
- 11.3.4. Analysis by Geography
- 11.3.4.1. Intercontinental and Intracontinental Deals
- 11.3.4.2. Local and International Deals
- 11.3.5. Most Active Players: Analysis by Number of Mergers and Acquisitions
- 11.3.6. Analysis by Key Value Drivers
- 11.3.7. Key Acquisitions: Deal Multiples
12. MARKET IMPACT ANALYSIS: DRIVERS, RESTRAINTS, OPPORTUNITIES AND CHALLENGES
- 12.1. Chapter Overview
- 12.2. Market Drivers
- 12.3. Market Restraints
- 12.4. Market Opportunities
- 12.5. Market Challenges
- 12.6. Conclusion
13. GLOBAL CHROMATOGRAPHY MARKET
- 13.1. Chapter Overview
- 13.2. Assumptions and Methodology
- 13.3. Global Chromatography Market, Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 13.3.1. Scenario Analysis
- 13.4. Key Market Segmentations
- 13.5. Dynamic Dashboard
14. CHROMATOGRAPHY MARKET: DISTRIBUTION BY TYPE OF PRODUCT, TILL 2035
- 14.1. Chapter Overview
- 14.2. Key Assumptions and Methodology
- 14.3. Chromatography Instruments: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 14.4. Chromatography Consumables: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 14.5. Other Accessories: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 14.6. Data Triangulation
- 14.6.1. Insights from Primary Research
- 14.6.2. Insights from Secondary Research
- 14.6.3. Insights from In-house Repository
15. CHROMATOGRAPHY MARKET: DISTRIBUTION BY TYPE OF CHROMATOGRAPHY INSTRUMENT
- 15.1. Chapter Overview
- 15.2. Key Assumptions and Methodology
- 15.3. Liquid Chromatography Instrument: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 15.4. Gas Chromatography Instrument: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 15.5. Other Instruments: Historical Trends (Since 2022) and Future Estimates (Till 2035)
- 15.6. Data Triangulation
- 15.6.1. Insights based on Primary Research
- 15.6.2. Insights based on Secondary Research
- 15.6.3. Insights from In-house Repository
16. CHROMATOGRAPHY MARKET: DISTRIBUTION BY TYPE OF CONSUMABLE FORMAT OFFERED, TILL 2035
- 16.1. Chapter Overview
- 16.2. Key Assumptions and Methodology
- 16.3. Pre-Packed Columns: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 16.4. Bottles / Bulk Resins: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 16.5. Other Formats: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 16.6. Data Triangulation
- 16.6.1. Insights based on Primary Research
- 16.6.2. Insights based on Secondary Research
- 16.6.3. Insights from In-house Repository
17. CHROMATOGRAPHY MARKET: DISTRIBUTION BY END USER
- 17.1. Chapter Overview
- 17.2. Key Assumptions and Methodology
- 17.3. Pharmaceutical and Biopharmaceutical Companies: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 17.4. Academic / Research Institutes: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 17.5. Other Industries: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 17.6. Data Triangulation
- 17.6.1. Insights based on Primary Research
- 17.6.2. Insights based on Secondary Research
- 17.6.3. Insights from In-house Repository
18. CHROMATOGRAPHY MARKET: DISTRIBUTION BY GEOGRAPHY
- 18.1. Chapter Overview
- 18.2. Key Assumptions and Methodology
- 18.3. North America: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 18.3.1. Chromatography Market for Chromatography Instruments
- 18.3.2. Chromatography Market for Chromatography Consumables
- 18.3.3. Chromatography Market for Other Accessories
- 18.4. Europe: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 18.4.1. Chromatography Market for Chromatography Instruments
- 18.4.2. Chromatography Market for Chromatography Consumables
- 18.4.3. Chromatography Market for Other Accessories
- 18.5. Asia-Pacific: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 18.5.1. Chromatography Market for Chromatography Instruments
- 18.5.2. Chromatography Market for Chromatography Consumables
- 18.5.3. Chromatography Market for Other Accessories
- 18.6. Rest of the World: Historical Trends (Since 2017) and Future Estimates (Till 2035)
- 18.6.1. Chromatography Market for Chromatography Instruments
- 18.6.2. Chromatography Market for Chromatography Consumables
- 18.6.3. Chromatography Market for Other Accessories
- 18.7. Data Triangulation
- 18.7.1. Insights based on Primary Research
- 18.7.2. Insights based on Secondary Research
- 18.7.3. Insights from In-house Repository
19. CONCLUSION
20. EXECUTIVE INSIGHTS
21. APPENDIX 1: TABULATED DATA
22. APPENDIX 2: LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 6.1 Chromatography Instruments Providers: Information on Year of Establishment, Company Size, Location of Headquarters, Type of Chromatography Instrument Offered, Type of Mobile Phase Offered, and Type of Chromatography Consumable Offered
- Table 6.2 Chromatography Instruments Providers: Information on Scale of Operation and Type of Industry Served
- Table 8.1 Chromatography Consumables Providers: Information on Chromatography Consumables Providers and Type of Separation Technique Offered
- Table 8.2 Chromatography Consumables Providers: Information of Type of Separation Technique Offered, Type of Solid Phase Offered and Type of Format Offered
- Table 8.3 Chromatography Consumables Providers: Information of Type of Separation Technique Offered and Type of Analyte Separated
- Table 8.4 Chromatography Consumables Providers: Information of Type of Separation Technique Offered and Application Areas
- Table 9.1 Leading Chromatography Instruments and Consumables Providers
- Table 9.2 Agilent Technologies: Company Overview
- Table 9.3 Agilent Technologies: Chromatography Instruments Portfolio
- Table 9.4 Agilent Technologies: Chromatography Consumables Portfolio
- Table 9.5 Agilent Technologies: Recent Developments and Future Outlook
- Table 9.6 Bio-Rad Laboratories: Company Overview
- Table 9.7 Bio-Rad Laboratories: Chromatography Instruments Portfolio
- Table 9.8 Bio-Rad Laboratories: Chromatography Consumables Portfolio
- Table 9.9 PerkinElmer: Company Overview
- Table 9.10 PerkinElmer: Chromatography Instruments Portfolio
- Table 9.11 PerkinElmer: Chromatography Consumables Portfolio
- Table 9.12 PerkinElmer: Recent Developments and Future Outlook
- Table 9.13 Sartorius: Company Overview
- Table 9.14 Sartorius: Chromatography Instruments Portfolio
- Table 9.15 Sartorius: Chromatography Consumables Portfolio
- Table 9.16 Sartorius: Recent Developments and Future Outlook
- Table 9.17 Shimadzu: Company Overview
- Table 9.18 Shimadzu: Chromatography Instruments Portfolio
- Table 9.19 Shimadzu: Chromatography Consumables Portfolio
- Table 9.20 Shimadzu: Recent Developments and Future Outlook
- Table 9.21 Thermo Fisher Scientific: Company Overview
- Table 9.22 Thermo Fisher Scientific: Chromatography Instruments Portfolio
- Table 9.23 Thermo Fisher Scientific: Chromatography Consumables Portfolio
- Table 9.24 Thermo Fisher Scientific: Recent Developments and Future Outlook
- Table 10.1 Patent Analysis: Top CPC Symbols
- Table 10.2 Patent Analysis: Top CPC Codes
- Table 10.3 Patent Analysis: Summary of Benchmarking Analysis
- Table 10.4 Patent Analysis: Categorization based on Weighted Valuation Scores
- Table 10.5 Patent Portfolio: List of Leading Patents (by Highest Relative Valuation)
- Table 10.6 Patent Portfolio: List of Leading Patents (by Number of Citations)
- Table 11.1 Chromatography Instruments and Consumables: List of Mergers and Acquisitions, 2015-2023
- Table 11.2 Acquisitions: Information on Key Value Drivers
- Table 11.3 Key Acquisitions: Information on Deal Multiples, 2015-2023
- Table 20.1 Hemochrom: Company Snapshot
- Table 20.2 SRI Instruments: Company Snapshot
- Table 21.1 Chromatography Instruments Providers: Distribution by Year of Establishment
- Table 21.2 Chromatography Instruments Providers: Distribution by Company Size
- Table 21.3 Chromatography Instruments Providers: Distribution by Location of Headquarters
- Table 21.4 Chromatography Instruments Providers: Distribution by Company Size and Location of Headquarters
- Table 21.5 Chromatography Instruments Providers: Distribution by Chromatography Instrument Offered
- Table 21.6 Chromatography Instruments Providers: Distribution by Type of Mobile Phase Used
- Table 21.7 Chromatography Instruments Providers: Distribution by Type of Consumables Offered
- Table 21.8 Chromatography Instruments Providers: Distribution by Scale of Operation
- Table 21.9 Chromatography Instruments Providers: Distribution by Type of Industry Served
- Table 21.10 Chromatography Consumables Providers: Distribution by Year of Establishment
- Table 21.11 Chromatography Consumables Providers: Distribution by Company Size
- Table 21.12 Chromatography Consumables Providers: Distribution by Location of Headquarters
- Table 21.13 Chromatography Consumables Providers: Distribution by Company Size and Location of Headquarters
- Table 21.14 Chromatography Consumables Providers: Distribution by Type of Separation Technique Used
- Table 21.15 Chromatography Consumables Providers: Distribution by Type of Solid Phase Used
- Table 21.16 Chromatography Consumables Providers: Distribution by Type of Consumable Formats Offered
- Table 21.17 Chromatography Consumables Providers: Distribution by Type of Analyte
- Table 21.18 Chromatography Consumables Providers: Distribution by Application Area
- Table 21.19 Patent Analysis: Distribution by Type of Patent
- Table 21.20 Patent Analysis: Distribution by Patent Publication Year, 2020-2023
- Table 21.21 Patent Analysis: Distribution by Patent Application Year, Pre-2019-2022
- Table 21.22 Patent Analysis: Distribution of Granted Patents and Patent Applications by Publication Year, 2020-2023
- Table 21.23 Patent Analysis: Distribution by Patent Jurisdiction (Region)
- Table 21.24 Patent Analysis: Distribution by Patent Jurisdiction (Country)
- Table 21.25 Patent Analysis: Cumulative Year-wise Distribution by Type of Applicant, 2020-2023
- Table 21.26 Leading Industry Players: Distribution by Number of Patents
- Table 21.27 Leading Non-Industry Players: Distribution by Number of Patents
- Table 21.28 Leading Individual Patent Assignees: Distribution by Number of Patents
- Table 21.29 Patent Analysis: Distribution by Patent Age
- Table 21.30 Chromatography Instruments and Consumables: Patent Valuation
- Table 21.31 Mergers and Acquisitions: Cumulative Year-Wise Distribution, Pre-2017-2023
- Table 21.32 Mergers and Acquisitions: Distribution by Type of Deal
- Table 21.33 Acquisitions: Distribution by Company Ownership
- Table 21.34 Acquisitions and Mergers: Intercontinental and Intracontinental Deals
- Table 21.35 Mergers and Acquisitions: Distribution by Local and International Agreements
- Table 21.36 Most Active Players: Distribution by Number of Mergers and Acquisitions
- Table 21.37 Acquisitions: Key Value Drivers
- Table 21.38 Global Chromatography Market, Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.40 Global Chromatography Market, 2023-2035: Conservative Scenario
- Table 21.41 Chromatography Market: Distribution by Type of Product, 2018, 2023 and 2035 (USD Billion)
- Table 21.42 Chromatography Market for Chromatography Instruments: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.43 Chromatography Market for Chromatography Consumables: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.44 Chromatography Market for Other Accessories: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.45 Chromatography Market: Distribution by Type of Instrument, 2018, 2023 and 2035 (USD Billion)
- Table 21.46 Chromatography Market for Liquid Chromatography Instruments: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.47 Chromatography Market for Gas Chromatography Instruments: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.48 Chromatography Market for Other Instruments: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.49 Chromatography Market: Distribution by Type of Consumable Formats, 2018, 2023 and 2035 (USD Billion)
- Table 21.50 Chromatography Market for Pre-packed columns: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.51 Chromatography Market for Bottles / Bulk Resins: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.52 Chromatography Market for Other Formats: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.53 Chromatography Market: Distribution by End User, 2018, 2023 and 2035 (USD Billion)
- Table 21.54 Chromatography Market for Pharmaceutical and Biotechnology Companies: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.55 Chromatography Market for Academic and Research Institutes: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.56 Chromatography Market for Other Industries: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.57 Chromatography Market: Distribution by Key Geographical Regions, 2018, 2023 and 2035 (USD Billion)
- Table 21.58 Chromatography Market in North America: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.59 Chromatography Market in Europe: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.60 Chromatography Market in Asia-Pacific: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
- Table 21.61 Chromatography Market in Rest of the World: Historical Trends (2018-2022) and Forecasted Estimates (2023-2035)
List of Figures
- Figure 2.1 Research Methodology: Research Assumptions
- Figure 2.2 Research Methodology: Project Methodology
- Figure 2.3 Research Methodology: Forecast Methodology
- Figure 2.4 Research Methodology: Robust Quality Control
- Figure 2.5 Research Methodology: Key Market Segmentations
- Figure 4.1 Executive Summary: Chromatography Instrument Providers Market Landscape
- Figure 4.2 Executive Summary: Chromatography Consumables Market Landscape
- Figure 4.3 Executive Summary: Patent Analysis
- Figure 4.4 Executive Summary: Mergers and Acquisitions
- Figure 4.5 Executive Summary: Market Sizing and Opportunity Analysis
- Figure 5.1 Components of Chromatography
- Figure 5.2 Types of Chromatography
- Figure 5.3 Applications of Chromatography
- Figure 6.1 Chromatography Instruments Providers: Distribution by Year of Establishment
- Figure 6.2 Chromatography Instruments Providers: Distribution by Company Size
- Figure 6.3 Chromatography Instruments Providers: Distribution by Location of Headquarters
- Figure 6.4 Chromatography Instruments Providers: Distribution by Company Size and Location of Headquarters
- Figure 6.5 Chromatography Instruments Providers: Distribution by Chromatography Instrument Offered
- Figure 6.6 Chromatography Instruments Providers: Distribution by Type of Mobile Phase Used
- Figure 6.7 Chromatography Instruments Providers: Distribution by Type of Consumables Offered
- Figure 6.8 Chromatography Instruments Providers: Distribution by Scale of Operation
- Figure 6.9 Chromatography Instruments Providers: Distribution by Type of Industry Served
- Figure 7.1 Small Companies Providing Chromatography Instruments
- Figure 7.2 Company Competitiveness Analysis: Leading Small Companies
- Figure 7.3 Mid-sized Companies Providing Chromatography Instruments
- Figure 7.4 Company Competitiveness Analysis: Leading Mid-sized Companies
- Figure 7.5 Large Companies Providing Chromatography Instruments
- Figure 7.6 Company Competitiveness Analysis: Leading Large Companies
- Figure 7.7 Very Large Companies Providing Chromatography Instruments
- Figure 7.8 Company Competitiveness Analysis: Leading Very Large Companies
- Figure 8.1 Chromatography Consumables Providers: Distribution by Year of Establishment
- Figure 8.2 Chromatography Consumable Providers: Distribution by Company Size
- Figure 8.3 Chromatography Consumable Providers: Distribution by Location of Headquarters
- Figure 8.4 Chromatography Consumable Providers: Distribution by Company Size and Location of Headquarters
- Figure 8.5 Chromatography Consumable Providers: Distribution by Type of Separation Technique Used
- Figure 8.6 Chromatography Consumable Providers: Distribution by Type of Solid Phase Used
- Figure 8.7 Chromatography Consumable Providers: Distribution by Type of Consumable Formats Offered
- Figure 8.8 Chromatography Consumable Providers: Distribution by Scale of Operation
- Figure 8.9 Chromatography Consumable Providers: Distribution by Application Area
- Figure 10.1 Patent Analysis: Distribution by Type of Patent
- Figure 10.2 Patent Analysis: Distribution by Patent Publication Year, 2020-2023
- Figure 10.3 Patent Analysis: Distribution by Patent Application Year, Pre-2019-2022
- Figure 10.4 Patent Analysis: Distribution of Granted Patents and Patent Applications by Publication Year, 2020-2023
- Figure 10.5 Patent Analysis: Distribution by Patent Jurisdiction (Region-wise)
- Figure 10.6 Patent Analysis: Distribution by Patent Jurisdiction (Country-wise)
- Figure 10.7 Patent Analysis: Distribution by CPC Symbols
- Figure 10.8 Patent Analysis: Cumulative Year-wise Distribution by Type of Applicant, 2020-2023
- Figure 10.9 Leading Industry Players: Distribution by Number of Patents
- Figure 10.10 Leading Non-Industry Players: Distribution by Number of Patents
- Figure 10.11 Leading Individual Patent Assignees: Distribution by Number of Patents
- Figure 10.12 Patent Benchmarking Analysis: Distribution of Leading Industry Player by Patent Characteristics (CPC Codes)
- Figure 10.13 Patent Analysis: Distribution by Patent Age
- Figure 10.14 Chromatography Instruments and Consumables: Patent Valuation
- Figure 11.1 Mergers and Acquisitions: Distribution by Type of Deal
- Figure 11.2 Mergers and Acquisitions: Cumulative Year-Wise Distribution, Pre-2017-2023
- Figure 11.3 Acquisitions: Distribution by Company Ownership
- Figure 11.4 Acquisitions and Mergers: Intercontinental and Intracontinental Deals
- Figure 11.5 Mergers and Acquisitions: Distribution by Local and International Deals
- Figure 11.6 Most Active Players: Distribution by Number of Mergers and Acquisitions
- Figure 11.7 Acquisitions: Key Value Drivers
- Figure 13.1 Global Chromatography Market, Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 13.2 Global Chromatography Market, 2023-2035: Optimistic Scenario
- Figure 13.3 Global Chromatography Market, 2023-2035: Conservative Scenario
- Figure 14.1 Chromatography Market for Chromatography Instruments: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 14.2 Chromatography Market for Chromatography Consumables: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 14.3 Chromatography Market for Other Accessories: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 15.1 Chromatography Market for Liquid Chromatography Instruments: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 15.2 Chromatography Market for Gas Chromatography Instruments: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 15.3 Chromatography Market for Other Instruments: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 16.1 Chromatography Market for Pre-packed columns: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 16.2 Chromatography Market for Bottles / Bulk Resins: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 16.3 Chromatography Market for Other Formats: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 17.1 Chromatography Market for Pharmaceutical and Biotechnology Companies: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 17.2 Chromatography Market for Academic and Research Institutes: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 17.3 Chromatography Market for Other Industries: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 18.1 Chromatography Market in North America: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 18.2 Chromatography Market in Europe: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 18.3 Chromatography Market in Asia-Pacific: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 18.4 Chromatography Market in Rest of the World: Historical Trends (2018-2022) and Future Estimates (2023-2035)
- Figure 19.1 Concluding Remarks: Chromatography Instrument Providers Market Landscape
- Figure 19.2 Concluding Remarks: Chromatography Consumables Providers Market Landscape
- Figure 19.3 Concluding Remarks: Patent Analysis
- Figure 19.4 Concluding Remarks: Mergers and Acquisitions
- Figure 19.5 Concluding Remarks: Market Sizing and Opportunity Analysis

 硼酸親和性和層析法市場規模、佔有率和成長分析:按產品類型、應用、最終用戶、方法和地區分類 - 產業預測,2026-2033年
 層析法耗材市場:依產品、層析法方法、最終用戶及地區分類:趨勢及至2035年的預測
 超臨界流體市場:依產品、設備、製程、最終用戶、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測層析法市場(2025-2030 年):市場概覽
 層析法設備市場:按組件、儀器類型、分析方法、檢測器類型和應用分類-2026-2032年全球市場預測離子交換層析法市場:2026-2032年全球市場預測(依產品類型、材料類型、方法類型、生產規模、分析類型、結構類型、應用和最終用戶分類)
 層析法資料系統市場:按產品類型、最終用戶產業、部署模式和地區分類芹菜素市場:依純度、原料、型態、應用、地區分類
 全球層析法設備市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 2026年全球一次性膜層析法系統市場報告