


 |
市場調查報告書
商品編碼
2106279
非病毒轉染試劑市場(第三版):按非病毒轉染方法、應用、最終用戶和地區分類的趨勢和預測(至2035年)Non-Viral Transfection Reagents Market (3rd Edition) by Type of Non-Viral Transfection Method, Application Area, End-User and Geographical Regions-Trends and Forecast Till 2035 |
||||||

非病毒轉染試劑市場概述
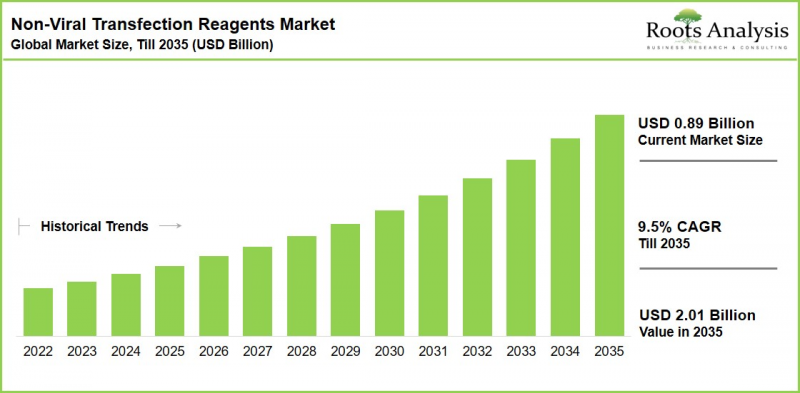
根據 Roots Analysis 的研究,全球非病毒轉染試劑市場規模預計將從今年的 8.9 億美元成長到 2035 年的 20.1 億美元,在預測期內(到 2035 年)的複合年成長率為 9.5%。
非病毒轉染試劑市場:成長與趨勢
基於核酸的療法在標靶多種疾病的遺傳機制方面展現出巨大潛力。因此,核准的此類療法數量不斷增加,證明了其臨床應用前景廣闊,並擴大了其作為治療層級的應用範圍。
隨著核酸療法產品線的擴展和商業化,對能夠確保靶向和有效胞內遞送的高效遞送平台的需求日益成長。傳統上,此類療法的開發和生產主要依賴病毒載體。然而,儘管病毒載體的研究和開發取得了顯著進展,但仍存在一些限制阻礙了其廣泛應用。
病毒載體面臨的主要挑戰包括免疫抗原性和細胞毒性問題、高昂的研發和生產成本,以及每次給藥可遞送的遺傳物質數量有限。為了克服這些限制,業內相關人員正擴大轉向非病毒基因遞送技術用於轉染應用。
非病毒轉染系統利用非病毒載體作為遞送介質,將遺傳物質標靶遞送至多種細胞類型。為了滿足日益成長的核酸療法需求,各公司正積極研發先進的非病毒轉染試劑和系統,這些試劑和系統非常適合體外細胞內遞送。此外,在非病毒載體應用日益廣泛以及轉染試劑和系統技術不斷進步的推動下,預計未來幾年非病毒轉染試劑市場將保持穩定成長。
非病毒轉染試劑市場
市場規模和機會分析根據以下參數進行分類:
非病毒轉染方法
- 化學方法
- 物理方法
- 其他方法
用途別
- 研究
- 臨床
最終用戶
- 獸醫大學和研究機構
- 製藥和生物技術公司
- 契約製造
- 其他
區域市場
- 北美洲
- 美國
- 加拿大
- 歐洲
- 法國
- 德國
- 英國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 日本
- 澳洲
- 韓國
- 中國
- 亞太其他地區
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 埃及
- 其他中東和非洲地區
- 拉丁美洲
- 巴西
- 阿根廷
- 其他拉丁美洲
非病毒轉染試劑市場:主要細分市場
就非病毒轉染方法而言,化學方法約佔整體市佔率的60%。這一主導地位歸功於基因治療應用中原代細胞轉染試劑和非病毒載體在全球的廣泛應用。
另一方面,受電穿孔等技術進步的推動,物理方法領域預計在預測期內將保持較高的複合年成長率。這些技術具有許多優勢,包括轉染時間更短、生物效率更高、毒性更低,以及能夠將核酸遞送至多種細胞類型,具有很高的通用性。
北美約佔全球非病毒轉染試劑市場的60%。其市場主導地位得益於成熟的製藥和生物技術產業以及先進非病毒轉染技術的快速普及。此外,北美擁有許多致力於複雜生技藥品(包括細胞和基因療法以及先進療法)研發的公司。這催生了對本地生產的非病毒轉染試劑和系統的巨大需求,特別是考慮到這些試劑和系統保存期限短且需要特殊處理。
預計到2035年,亞太地區非病毒轉染試劑市場將維持最高的複合年成長率。這一成長主要得益於該地區大規模生產原料藥(API)產能的擴張以及高價值生技藥品生產外包的增加。為了符合全球品質和出口標準,區域製造商正大力投資先進的生產基礎設施,並在其研發和生產流程中推廣使用非病毒轉染試劑和系統。
本報告考察了全球非病毒轉染試劑市場,提供了概述、背景、市場影響因素分析、市場規模趨勢和預測、按各個細分市場和地區/主要國家進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章:序言
第2章:調查方法
第3章 市場動態
第4章 宏觀經濟指標
第5章摘要整理
- 市場狀況
- 市場趨勢
- 市場預測與機會分析
第6章:引言
- 章節概要
- 轉染概述
- 轉染技術
- 基於病毒的
- 非病毒型
- 轉染的應用
- 先進治療藥物(ATMP)的開發
- 基因靜默
- 建構穩定表達細胞株
- 大規模蛋白質生產
- 幹細胞工程
- 前景
第7章 市集概況:非病毒轉染試劑
- 章節概要
- 非病毒轉染試劑:市場現狀
- 依適當的細胞類型/細胞株進行分析
- 將引入按分子類型進行分析的方法。
- 按轉染載體類型進行分析
- 細胞培養類型分析
- 血清相容性分析
- 非病毒轉染試劑供應商概覽
第8章 市場概況:基於電穿孔的轉染系統
- 章節概要
- 基於電穿孔的轉染系統:市場概覽
- 依適當的細胞類型/菌株進行分析
- 轉染分子的分析
- 波形類型分析
- 脈衝電壓分析
- 電穿孔轉染系統供應商概覽
第9章 市場趨勢:其他非病毒轉染技術/系統
- 章節概要
- 其他非病毒轉染技術/系統:市場概覽
- 按規定表格
- 適用的細胞類型/細胞系
- 透過轉染分子
- 其他非病毒轉染技術/系統供應商概覽
第10章:企業競爭力分析
- 章節概要
- 前提條件和關鍵參數
- 調查方法
- 企業競爭力分析:非病毒轉染試劑供應商
- 北美供應商(Peer GroupI)
- 歐洲供應商(Peer GroupII)
- 總部位於亞太地區的供應商(第三Peer Group)
第11章:技術競爭力分析
- 章節概要
- 前提條件和關鍵參數
- 調查方法
- 技術競爭力分析:基於電穿孔的轉染系統
- 北美公司提供的以電穿孔為基礎的轉染系統(Peer GroupI)
- 歐洲和亞太地區的公司提供的以電穿孔為基礎的轉染系統(第二類同Peer Group)。
- 技術競爭力分析:其他非病毒轉染技術/系統
- 北美公司提供的其他非病毒轉染技術/系統(Peer GroupI)
- 歐洲和亞太地區公司提供的其他非病毒轉染技術/系統(Peer GroupII)
第12章:公司簡介
- 章節概要
- 非病毒轉染試劑供應商
- MilliporeSigma
- OZ Biosciences
- Thermo Fisher Scientific
- 基於電穿孔的非病毒轉染系統供應商
- BEX
- Bio-Rad Laboratories
- Harvard Bioscience
- MaxCyte
- NepaGene
- 其他非病毒轉染技術/系統供應商
- LocateBio
- N4 Pharma
第13章:潛在戰略夥伴
- 章節概要
- 前提條件和關鍵參數
- 研究範圍和調查方法
- 北美非病毒轉染試劑和系統供應商的潛在策略夥伴。
- 歐洲非病毒轉染試劑和系統供應商的潛在策略夥伴
- 亞太地區及其他地區非病毒轉染試劑和系統供應商的潛在策略夥伴。
第14章 市場趨勢分析
- 章節概要
- 體外和體內療法的發展趨勢
- 病毒載體和非病毒載體的發展趨勢
第15章 專利分析
- 章節概要
- 研究範圍和調查方法
- 非病毒轉染:專利分析
- 專利基準分析
- 專利評估
第16章 文獻分析
- 章節概要
- 研究範圍和調查方法
- 非病毒轉染試劑與系統:文獻分析
- 主要版權所有者:按出版物數量分析
第17章:基於根分析的定價策略框架
- 章節概要
- ROOTS ANALYSIS 框架
- 結論
第18章 市場影響分析
- 章節概要
- 市場促進因素
- 市場限制因素
- 市場機遇
- 市場挑戰
第19章:全球非病毒轉染試劑與系統市場
- 章節概要
- 關鍵假設和調查方法
- 全球非病毒轉染試劑和系統市場:歷史趨勢和預測
- 主要市場區隔
第20章 非病毒轉染試劑與系統市場:依轉染法分類
- 章節概要
- 關鍵假設和調查方法
- 非病毒轉染試劑與系統市場:依轉染法分類
- 化學方法
- 物理方法
- 其他方法
- 數據三角測量與檢驗
第21章 非病毒轉染試劑與系統市場:依應用分類
- 章節概要
- 關鍵假設和調查方法
- 非病毒轉染試劑與系統市場:依應用領域分類
- 研究
- 臨床
- 數據三角測量與檢驗
第22章 非病毒轉染試劑與系統市場:依最終用戶分類
- 章節概要
- 關鍵假設和調查方法
- 非病毒轉染試劑和系統市場:依最終用戶分類
- 學術和研究機構
- 製藥和生物製藥公司
- 契約製造
- 其他
- 數據三角測量與檢驗
第23章 非病毒轉染試劑與系統市場:依主要地區分類
- 章節概要
- 關鍵假設和調查方法
- 非病毒轉染試劑與系統市場:依地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 市場動態評估
- 市場波動分析
- 滲透成長(PG)矩陣
- 數據三角測量與檢驗
第24章 結論
第25章:高階主管洞見
第26章附錄一:表格形式數據
第27章 附錄二:公司與組織列表
NON-VIRAL TRANSFECTION REAGENTS MARKET: OVERVIEW
As per Roots Analysis, the global non-viral transfection reagents market is estimated to grow from 0.89 billion in the current year to USD 2.01 billion by 2035, at a CAGR of 9.5% during the forecast period, till 2035.
NON-VIRAL TRANSFECTION REAGENTS MARKET: GROWTH AND TRENDS
Nucleic acid-based therapies have demonstrated significant potential in targeting genetic mechanisms for the treatment of a broad range of therapeutic indications. Consequently, a growing number of these therapies have secured regulatory approvals, underscoring both their clinical potential and the increasing adoption of this therapeutic class.
The expanding pipeline and commercialization of nucleic acid-based therapeutics have accelerated the demand for efficient delivery platforms capable of ensuring targeted and effective intracellular delivery. Traditionally, the development and manufacturing of such therapies have relied heavily on viral vectors. However, despite substantial advancements in viral vector research and manufacturing capabilities, several limitations continue to hinder their widespread applicability.
Key challenges associated with viral vectors include immunogenicity and cytotoxicity concerns, high development and manufacturing costs, and limitations related to the quantity of genetic material that can be delivered per dose. In response to these constraints, industry stakeholders are increasingly transitioning toward non-viral gene delivery technologies for transfection applications.
Non-viral transfection systems involve the targeted delivery of genetic material into a diverse range of cell types using non-viral vectors as delivery carriers. To address the growing demand for nucleic acid-based therapeutics, companies are actively developing advanced non-viral transfection reagents and systems that are highly suitable for in vitro intracellular delivery applications. Furthermore, driven by the rising preference for non-viral vectors and ongoing technological advancements in transfection reagents and systems, the non-viral transfection reagents market is anticipated to witness steady growth in the coming years.
Growth Drivers: Strategic Enablers of Market Expansion
The non-viral transfection reagents market is primarily driven by the growing demand for nucleic acid-based therapeutics, including gene therapies, mRNA therapeutics, RNAi-based drugs, and DNA vaccines, which require efficient intracellular delivery technologies. In addition, the limitations associated with viral vectors, such as immunogenicity, cytotoxicity, high manufacturing costs, and limited cargo capacity, are encouraging the adoption of non-viral delivery systems as safer and more scalable alternatives. The market is further supported by increasing research activities in cell and gene therapy, rising investments in biotechnology and pharmaceutical R&D, and the expanding adoption of gene editing technologies such as CRISPR-Cas9. Moreover, continuous technological advancements in lipid-based, polymer-based, and nanoparticle-based transfection systems have enhanced delivery efficiency and cell viability, thereby accelerating market adoption across research and therapeutic applications.
Market Challenges: Critical Barriers Impeding Progress
The non-viral transfection reagents market faces several challenges despite its growing adoption across research and therapeutic applications. One of the primary concerns is the relatively lower transfection efficiency of non-viral systems compared to viral vectors, particularly in hard-to-transfect and primary cell types. In addition, issues related to limited intracellular uptake, reduced stability of genetic material, transient gene expression, and potential cytotoxic effects of certain reagents continue to hinder widespread application. The lack of standardized protocols and variability in transfection performance across different cell lines further complicate product adoption in both research and clinical settings. Moreover, the development of highly efficient and targeted non-viral delivery systems requires substantial investment in research and optimization, increasing overall development costs. Regulatory complexities associated with advanced gene delivery technologies and the growing competition from emerging delivery platforms also pose significant challenges to market growth.
NON-VIRAL TRANSFECTION REAGENTS MARKET: KEY TRENDS
The report delves into the current state of the non-viral transfection reagents market and identifies potential growth opportunities within industry. Some key highlights in this domain include:
Rising Prevalence of Chronic Diseases: The increasing prevalence of chronic diseases has accelerated the demand for innovative and potentially curative therapeutic interventions, thereby driving the adoption of non-viral transfection reagents and systems. The growing preference for non-viral transfection technologies can be attributed to the multiple advantages they offer, including enhanced therapeutic efficacy through targeted and localized delivery while minimizing systemic exposure. As a result, these technologies have the potential to improve treatment outcomes and enhance patient quality of life across various therapeutic applications.
Advancements in Nanotechnology and Biotechnology: Continuous advancements in nanotechnology and biotechnology have enabled the developers to improve drug efficacy and delivery precision. Advanced nanomaterials facilitate targeted intracellular delivery while reducing systemic side effects, owing to their multifunctional design capabilities that allow the incorporation of targeting ligands and therapeutic payloads. Several non-viral transfection reagents leveraging nanotechnology-based delivery carriers have emerged in the market, including products such as jetOPTIMUS and PolyMag.
Non-Viral Transfection Reagents Market
The market sizing and opportunity analysis has been segmented across the following parameters:
Market by Type of Non-Viral Transfection Method
- Chemical Methods
- Physical Methods
- Other Methods
Market by Application Area
- Research Applications
- Clinical Applications
Market by End-User
- Veterinary Academic and Research Institutions
- Pharmaceutical and Biotechnological Companies
- Contract Manufacturers
- Other End-users
Market by Geographical Regions
- North America
- US
- Canada
- Europe
- France
- Germany
- UK
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- Japan
- Australia
- South Korea
- China
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- UAE
- Egypt
- Rest of Middle East and Africa
- Latin America
- Brazil
- Argentina
- Rest of Latin America
NON-VIRAL TRANSFECTION REAGENTS MARKET: KEY SEGMENTS
Which Type of Non-Viral Transfection Method Accounts for the Largest Share of the Non-Viral Transfection Reagents and Equipment Market?
The non-viral transfection reagents and equipment market is segmented based on the type of non-viral transfection method into chemical methods, physical methods, and other methods. According to the non-viral transfection reagents market analysis, the chemical methods segment captures nearly 60% of the overall market share. This dominance can be attributed to the increasing adoption of primary cell transfection reagents and non-viral vectors in gene therapy applications across the global market.
The physical methods segment is anticipated to witness a comparatively higher CAGR during the forecast period, driven by ongoing technological advancements in techniques such as electroporation. These technologies offer several advantages, including shorter transfection timelines, improved biological efficiency, lower toxicity, and enhanced versatility for nucleic acid delivery across a broad range of cell types.
Regional Analysis: Which Regions are Demonstrating the Fastest Growth in the Non-Viral Transfection Reagents Industry?
North America: Largest Regional Market
North America represents approximately 60% of the global non-viral transfection reagents market share. The region's leadership position is supported by its well-established pharmaceutical and biotechnology industry, coupled with the rapid adoption of advanced non-viral transfection technologies. Moreover, North America serves as a major hub for companies involved in the development of complex biologics and advanced therapeutics, including cell and gene therapies, thereby generating significant demand for locally manufactured non-viral transfection reagents and systems, particularly due to their limited shelf life and specialized handling requirements.
US Non-Viral Transfection Reagents Market Trends
In the US, supportive regulatory pathways established by the US Food and Drug Administration for the approval of DNA transfection reagents, RNA transfection reagents, and non-viral transfection technologies are contributing significantly to market growth. Although regulatory standards remain stringent, the availability of clear regulatory guidance for validation and commercialization has facilitated broader adoption and accelerated market entry for innovative transfection systems.
Asia-Pacific: Emerging as a Key Growth Hub
The Asia-Pacific non-viral transfection reagents market is anticipated to witness the highest CAGR through 2035. This growth is primarily driven by the region's expanding large-scale manufacturing capabilities for active pharmaceutical ingredients (APIs) and the increasing outsourcing of high-value biologics manufacturing activities. In order to comply with global quality and export standards, regional manufacturers are making significant investments in advanced manufacturing infrastructure and increasingly adopting non-viral transfection reagents and systems across research and production workflows.
Will the Research Applications Segment Continue to Hold the Largest Market Share?
According to the non-viral transfection reagents market forecast, the research applications segment currently represents the largest share of the market. This dominance can be attributed to the growing focus on research and development activities, along with the increasing adoption of non-viral transfection methods across molecular biology, cell biology, and gene therapy research applications. Meanwhile, the clinical applications segment is expected to register a higher CAGR during the forecast period. The rising prevalence of chronic diseases, coupled with the increasing number of approvals for cell and gene therapies, is anticipated to drive the growth of this segment over the coming years.
Primary Research Overview
Discussions with multiple stakeholders in this domain influenced the opinions and insights presented in this study. The market report includes detailed transcripts of interviews conducted with the following individuals:
- Former-Vice-President, Business Development and Partnerships, Small Company, US
- Former Global Business Development Manager, Clinical Operations, Mid-sized Company, France
- Researcher, Mid-sized Non-Industry Player, Chile
Additionally, the market report includes transcripts of the following third-party discussions:
- Chairman and Chief Executive Officer, Mid-sized Company, the US
- Co-Founder and Chief Executive Officer, Small Company, the US
- Chief Scientific Officer and Executive Vice President of R&D, Mid-sized Company, the US
- Chief Scientific Officer, Mid-sized Company, the US
- Vice President of Cell Therapy Process Development, Large Company, the US
- Group Leader of R&D Transfection, and Director and Senior Product Manager, Large Company, Switzerland
Example Players in Non-Viral Transfection Reagents Market
- BEX
- Bio-Rad Laboratories
- Harvard Bioscience
- LocateBio
- MaxCyte
- MilliporeSigma
- Nepa Gene
- N4 Pharma
- OZ Biosciences
- Thermo Fisher Scientific
NON-VIRAL TRANSFECTION REAGENTS MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: The report features an in-depth analysis of the global non-viral transfection reagents market, focusing on key market segments, including [A] type of non-viral transfection method, [B] application area, [C] end-user and [D] key geographical regions.
- Non-Viral Transfection Reagents Market Landscape: A comprehensive evaluation of the companies developing non-viral transfection reagents, based on several relevant parameters, such as [A] type of carrier used, [B] compatible cell type, [C] type of molecule delivered and [D] serum compatibility. Additionally, a comprehensive evaluation of non-viral transfection reagent developers, based on several relevant parameters, such as [A] year of establishment, [B] company size and [C] location of headquarters.
- Electroporation-Based Transfection Systems Market Landscape: A detailed analysis of the companies developing electroporation-based non-viral transfection systems, based on several relevant parameters, such as [A] compatible cell type and [B] type of molecule delivered. Additionally, a comprehensive evaluation of electroporation transfection systems developers, based on several relevant parameters, such as [A] year of establishment, [B] company size and [C] location of headquarters.
- Other Non-Viral Transfection Systems Market Landscape: An insightful evaluation of the companies developing other non-viral transfection systems, based on several relevant parameters, such as [A] compatible cell type and [B] type of molecule delivered. Additionally, a comprehensive evaluation of other non-viral transfection systems developers, based on several relevant parameters, such as [A] year of establishment, [B] company size and [C] location of headquarters.
- Company Competitiveness Analysis: A comprehensive competitive analysis of non-viral transfection reagent and system developers, examining factors, such as [A] developer strength and [B] product portfolio strength.
- Technology Competitiveness Analysis: A detailed analysis of electroporation transfection systems and other non-viral transfection systems, examining factors, such as [A] developer strength and [B] product portfolio strength.
- Company Profiles: In-depth profiles of key players that are engaged in the development of non-viral transfection reagents and systems, focusing on [A] overview of the company, [B] financial information (if available) and [C] recent developments and an informed future outlook.
- Potential Strategic Partners: An insightful analysis of more than 80 cell and gene therapy developers that are likely to partner with non-viral transfection reagent and system developers, based on several relevant parameters, such as [A] pipeline maturity, [B] developer strength, [C] pipeline strength and [D] type of therapy.
- Benchmark Analysis: A comprehensive benchmark analysis of various non-viral focused initiatives undertaken by big pharma players, based on several relevant parameters, such as [A] year of initiative, [B] type of initiative, [C] type of therapy and [D] target therapeutic area.
- Patent Analysis: An in-depth analysis of patents filed / granted till date in the non-viral transfection systems domain, based on various relevant parameters, such as [A] type of patent, [B] publication year, [C] application year, [D] geography, [E] type of applicant, [F] CPC symbols, [G] emerging focus areas, [H] leading players (in terms of number of patents granted / filed), [I] patent benchmarking and [J] valuation analysis.
- Publication Analysis: An insightful analysis of over 450 peer-reviewed, scientific articles focused on non-viral transfection reagents and systems, based on various relevant parameters, such as [A] year of publication, [B] type of publication, [C] type of molecule delivered, [D] target therapeutic area, [E] key focus areas, [F] popular cells and cell lines. Additionally, the section includes analysis of the leading publishers across different geographies and key journals (in terms of number of articles published).
- Roots Analysis Pricing Strategy Framework: A detailed framework for analyzing the pricing strategy of a company's non-viral transfection reagents and its competitive market position, including an equation to estimate reagent prices based on their characteristics.
- Market Impact Analysis: The report analyzes various factors such as drivers, restraints, opportunities, and challenges affecting the market growth.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which are the leading companies in the non-viral transfection reagents market?
- Which region dominates the non-viral transfection reagents market?
- What are the key trends observed in non-viral transfection reagents market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by non-viral transfection reagents providers?
- What is the current and future market size?
- What is the CAGR of this market?
- How is the current and future market opportunity likely to be distributed across key market segments?
REASONS TO BUY THIS REPORT
- The report provides a comprehensive market analysis, offering detailed revenue projections of the overall market and its specific sub-segments. This information is valuable to both established market leaders and emerging entrants.
- The report offers stakeholders a comprehensive overview of the market, including key drivers, barriers, opportunities, and challenges. This information empowers stakeholders to stay abreast of market trends and make data-driven decisions to capitalize on growth prospects.
- The report can aid businesses in identifying future opportunities in any sector. It also helps in understanding if those opportunities are worth pursuing.
- The report helps in identifying customer demand by understanding the needs, preferences, and behavior of the target audience in order to tailor products or services effectively.
- The report equips new entrants with requisite information regarding a particular market to help them build successful business strategies.
- The report allows for more effective communication with the audience and in building strong business relations.
ADDITIONAL BENEFITS
- Complementary PPT Insights Pack
- Complimentary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Report Coverage
- 1.3. Market Segmentation
- 1.4. Key Market Insights
- 1.5. Market Share Insights
- 1.6. Key Questions Asked
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations on the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
- 5.1. Executive Summary: Market Landscape
- 5.2. Executive Summary: Market Trends
- 5.3. Executive Summary: Market Forecast and Opportunity Analysis
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Introduction to Transfection
- 6.3. Methods of Transfection
- 6.3.1. Virus Based Transfection
- 6.3.1.1. Types of Viral Transfection Vectors
- 6.3.1.1.1. Adeno-associated Virus-based Vectors
- 6.3.1.1.2. Adenovirus-based Vectors
- 6.3.1.1.3. Herpes Virus-based Vectors
- 6.3.1.1.4. Lentivirus-based Vectors
- 6.3.1.1.5. Retrovirus-based Vectors
- 6.3.1.1. Types of Viral Transfection Vectors
- 6.3.2. Non-Virus Based Transfections
- 6.3.2.1. Chemical Methods based Transfection
- 6.3.2.1.1. Lipoplexes-based Transfection
- 6.3.2.1.2. Polyplexes-based Transfection
- 6.3.2.1.3. Lipo-polyplexes-based Transfection
- 6.3.2.1.4. Dendrimer-based Transfection
- 6.3.2.1.5. Cell Penetrating Peptide-based Transfection
- 6.3.2.2. Physical Method based Transfections
- 6.3.2.2.1. Electroporation-based Transfection
- 6.3.2.2.2. Gene Gun-based Transfection
- 6.3.2.2.3. Sonoporation-based Transfection
- 6.3.2.2.4. Microinjection-based Transfection
- 6.3.2.2.5. Magnetofection-based Transfection
- 6.3.2.1. Chemical Methods based Transfection
- 6.3.1. Virus Based Transfection
- 6.4. Applications of Transfection
- 6.4.1. Advanced Therapeutic Medicinal Product Development
- 6.4.2. Gene Silencing
- 6.4.3. Generation of Stable Cell Lines
- 6.4.4. Large-scale Protein Production
- 6.4.5. Stem Cell Engineering
- 6.5. Future Perspective
7. MARKET LANDSCAPE: NON-VIRAL TRANSFECTION REAGENTS
- 7.1. Chapter Overview
- 7.2. Non-Viral Transfection Reagents: Overall Market Landscape
- 7.2.1. Analysis by Compatible Cell Type / Line
- 7.2.2. Analysis by Transfected Molecule
- 7.2.3. Analysis by Type of Transfection Carrier Used
- 7.2.4. Analysis by Type of Cell Culture
- 7.2.5. Analysis by Serum Compatibility
- 7.3. Non-Viral Transfection Reagent Providers Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
8. MARKET LANDSCAPE: ELECTROPORATION-BASED TRANSFECTION SYSTEMS
- 8.1. Chapter Overview
- 8.2. Electroporation-based Transfection Systems: Overall Market Landscape
- 8.2.1. Analysis by Compatible Cell Type / Line
- 8.2.2. Analysis by Transfected Molecule
- 8.2.3. Analysis by Type of Waveform
- 8.2.4. Analysis by Pulse Voltage
- 8.3. Electroporation-based Transfection System Providers Landscape
- 8.3.1. Analysis by Year of Establishment
- 8.3.2. Analysis by Company Size
- 8.3.3. Analysis by Location of Headquarters
- 8.3.4. Analysis by Leading Players
9. MARKET LANDSCAPE: OTHER NON-VIRAL TRANSFECTION TECHNOLOGIES / SYSTEMS
- 9.1. Chapter Overview
- 9.2. Other Non-Viral Transfection Technologies / Systems: Market Landscape
- 9.2.1. Analysis by Type of Offering
- 9.2.2. Analysis by Compatible Cell Type / Line
- 9.2.3. Analysis by Transfected Molecule
- 9.3. Other Non-Viral Transfection Technologies / System Providers Landscape
- 9.3.1. Analysis by Year of Establishment
- 9.3.2. Analysis by Company Size
- 9.3.3. Analysis by Location of Headquarters
10. COMPANY COMPETITIVENESS ANALYSIS
- 10.1. Chapter Overview
- 10.2. Assumptions and Key Parameters
- 10.3. Methodology
- 10.4. Company Competitiveness Analysis: Non-Viral Transfection Reagent Providers
- 10.4.1. Non-Viral Transfection Reagent Providers based in North America (Peer Group I)
- 10.4.2. Non-Viral Transfection Reagent Providers based in Europe (Peer Group II)
- 10.4.3. Non-Viral Transfection Reagent Providers based in Asia-Pacific (Peer Group III)
11. TECHNOLOGY COMPETITIVENESS ANALYSIS
- 11.1. Chapter Overview
- 11.2. Assumptions and Key Parameters
- 11.3. Methodology
- 11.4. Technology Competitiveness Analysis: Electroporation-based Transfection Systems
- 11.4.1. Electroporation-based Transfection Systems Offered by Players based in North America (Peer Group I)
- 11.4.2. Electroporation-based Transfection Systems Offered by Players based in Europe and Asia-Pacific (Peer Group II)
- 11.5. Technology Competitiveness Analysis: Other Non-Viral Transfection Technology / Systems
- 11.5.1. Other Non-Viral Transfection Technologies / Systems Offered by Players based in North America (Peer Group I)
- 11.5.2. Other Non-Viral Transfection Technologies / Systems Offered by Players based in Europe and Asia-Pacific (Peer Group II)
12. COMPANY PROFILES
- 12.1. Chapter Overview
- 12.2. Non-Viral Transfection Reagent Providers
- 12.2.1. MilliporeSigma
- 12.2.1.1. Company Overview
- 12.2.1.2. Financial Information
- 12.2.1.3. Non-Viral Transfection Reagents Portfolio
- 12.2.1.4. Recent Developments and Future Outlook
- 12.2.2. OZ Biosciences
- 12.2.2.1. Company Overview
- 12.2.2.2. Non-Viral Transfection Reagents Portfolio
- 12.2.2.3. Recent Developments and Future Outlook
- 12.2.3. Thermo Fisher Scientific
- 12.2.3.1. Company Overview
- 12.2.3.2. Financial Information
- 12.2.3.3. Non-Viral Transfection Reagents Portfolio
- 12.2.3.4. Recent Development and Future Outlook
- 12.2.1. MilliporeSigma
- 12.3. Electroporation-based Non-Viral Transfection System Providers
- 12.3.1. BEX
- 12.3.1.1. Company Overview
- 12.3.1.2. Electroporation-based Non-Viral Transfection System Portfolio
- 12.3.1.3. Recent Developments and Future Outlook
- 12.3.2. Bio-Rad Laboratories
- 12.3.2.1. Company Overview
- 12.3.2.2. Financial Information
- 12.3.2.3. Electroporation-based Non-Viral Transfection System Portfolio
- 12.3.2.4. Recent Developments and Future Outlook
- 12.3.3. Harvard Bioscience
- 12.3.3.1. Company Overview
- 12.3.3.2. Financial Information
- 12.3.3.3. Electroporation-based Non-Viral Transfection System Portfolio
- 12.3.3.4. Recent Developments and Future Outlook
- 12.3.4. MaxCyte
- 12.3.4.1. Company Overview
- 12.3.4.2. Financial Information
- 12.3.4.3. Electroporation-based Non-Viral Transfection System Portfolio
- 12.3.4.4. Recent Developments and Future Outlook
- 12.3.5. NepaGene
- 12.3.5.1. Company Overview
- 12.3.5.2. Electroporation-based Non-Viral Transfection System Portfolio
- 12.3.5.3. Recent Developments and Future Outlook
- 12.3.1. BEX
- 12.4. Other Non-Viral Transfection Technology / System Providers
- 12.4.1. LocateBio
- 12.4.1.1. Company Overview
- 12.4.1.2. Other Non-Viral Transfection Technology / System Portfolio
- 12.4.1.3. Recent Developments and Future Outlook
- 12.4.2. N4 Pharma
- 12.4.2.1. Company Overview
- 12.4.2.2. Other Non-Viral Transfection Technology / System Portfolio
- 12.4.2.3. Recent Developments and Future Outlook
- 12.4.1. LocateBio
13. POTENTIAL STRATEGIC PARTNERS
- 13.1. Chapter Overview
- 13.2. Assumptions and Key Parameters
- 13.3. Scope and Methodology
- 13.4. Potential Strategic Partners for Non-Viral Transfection Reagents and Systems Providers based in North America
- 13.4.1. Most Likely Partners
- 13.4.2. Likely Partners
- 13.4.3. Less Likely Partners
- 13.4.4. Least Likely Partners
- 13.5. Potential Strategic Partners for Non-Viral Transfection Reagents and Systems Providers based in Europe
- 13.5.1. Most Likely Partners
- 13.5.2. Likely Partners
- 13.5.3. Less Likely Partners
- 13.5.4. Least Likely Partners
- 13.6. Potential Strategic Partners for Non-Viral Transfection Reagents and Systems Providers based in Asia-Pacific and Rest of the World
- 13.6.1. Most Likely Partners
- 13.6.2. Likely Partners
- 13.6.3. Less Likely Partners
- 13.6.4. Least Likely Partners
14. MARKET TRENDS ANALYSIS
- 14.1. Chapter Overview
- 14.2. Ex-vivo and In-vivo Therapy Trends
- 14.3. Viral and Non-Viral Vector Trends
15. PATENT ANALYSIS
- 15.1. Chapter Overview
- 15.2. Scope and Methodology
- 15.3. Non-Viral Transfection: Patent Analysis
- 15.3.1. Analysis by Patent Publication Year
- 15.3.2. Analysis by Type of Patent and Publication Year
- 15.3.3. Analysis by Patent Application Year
- 15.3.4. Analysis by Patent Jurisdiction
- 15.3.5. Analysis by CPC Symbols
- 15.3.6. Analysis by Type of Applicant
- 15.3.7. Leading Players: Analysis by Number of Patents
- 15.3.8. Leading Inventors: Analysis by Number of Patents
- 15.4. Patent Benchmarking Analysis
- 15.4.1. Analysis by Patent Characteristics
- 15.5. Patent Valuation
16. PUBLICATION ANALYSIS
- 16.1. Chapter Overview
- 16.2. Scope and Methodology
- 16.3. Non-Viral Transfection Reagents and Systems: Publication Analysis
- 16.3.1. Analysis by Year of Publication
- 16.3.2. Most Active Publisher: Analysis by Number of Publications
- 16.3.3. Key Journals: Analysis by Journal Impact Factor
- 16.3.4. Most Popular Journals: Analysis by Number of Publications
- 16.4. Prominent Copyright Holders: Analysis by Number of Publications
17. ROOTS ANALYSIS PRICING STRATEGY FRAMEWORK
- 17.1. Chapter Overview
- 17.2. Roots Analysis Framework
- 17.2.1. Methodology
- 17.2.2. Theoretical Framework and Price Evaluation Hypothesis
- 17.2.3. Results and Interpretation
- 17.2.3.1. Product Price Evaluation Matrix: Based on Transfection Efficiency
- 17.2.3.2. Product Price Evaluation Matrix: Based on Compatible Cell Type / Line
- 17.2.3.3. Product Price Evaluation Matrix: Based on Type of Carrier Used
- 17.2.3.4. Product Price Evaluation Matrix: Based on Type of Molecule Delivered
- 17.2.3.5. Product Price Evaluation Matrix: Based on Type of Reagent
- 17.3. Concluding Remarks
18. MARKET IMPACT ANALYSIS
- 18.1. Chapter Overview
- 18.2. Market Drivers
- 18.3. Market Restraints
- 18.4. Market Opportunities
- 18.5. Market Challenges
19. GLOBAL NON-VIRAL TRANSFECTION REAGENTS AND SYSTEMS MARKET
- 19.1. Chapter Overview
- 19.2. Key Assumptions and Methodology
- 19.3. Global Non-Viral Transfection Reagents and Systems Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 19.3.1. Scenario Analysis
- 19.3.1.1. Conservative Scenario
- 19.3.1.2. Optimistic Scenario
- 19.3.1. Scenario Analysis
- 19.4. Key Market Segmentations
20. NON-VIRAL TRANSFECTION REAGENTS AND SYSTEMS MARKET, BY TYPE OF TRANSFECTION METHOD
- 20.1. Chapter Overview
- 20.2. Key Assumptions and Methodology
- 20.3. Non-Viral Transfection Reagents and Systems Market: Distribution by Type of Transfection Method
- 20.3.1. Non-Viral Transfection Reagents and Systems Market for Chemical Methods, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 20.3.2. Non-Viral Transfection Reagents and Systems Market for Physical Methods, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 20.3.3. Non-Viral Transfection Reagents and Systems Market for Other Methods, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 20.4. Data Triangulation and Validation
21. NON-VIRAL TRANSFECTION REAGENTS AND SYSTEMS MARKET, BY APPLICATION AREA
- 21.1. Chapter Overview
- 21.2. Key Assumptions and Methodology
- 21.3. Non-Viral Transfection Reagents and Systems Market: Distribution by Application Area
- 21.3.1. Non-Viral Transfection Reagents and Systems Market for Research Applications, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 21.3.2. Non-Viral Transfection Reagents and Systems Market for Clinical Applications, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 21.4. Data Triangulation and Validation
22. NON-VIRAL TRANSFECTION REAGENTS AND SYSTEMS MARKET, BY END-USER
- 22.1. Chapter Overview
- 22.2. Key Assumptions and Methodology
- 22.3. Non-Viral Transfection Reagents and Systems Market: Distribution by End-User
- 22.3.1. Non-Viral Transfection Reagents and Systems Market for Academic and Research Institutes, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 22.3.2. Non-Viral Transfection Reagents and Systems Market for Pharmaceutical and Biopharmaceutical Companies, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 22.3.3. Non-Viral Transfection Reagents and Systems Market for Contract Manufacturers, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 22.3.4. Non-Viral Transfection Reagents and Systems Market for Other End-Users, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 22.4. Data Triangulation and Validation
23. NON-VIRAL TRANSFECTION REAGENTS AND SYSTEMS MARKET, BY KEY GEOGRAPHICAL REGIONS
- 23.1. Chapter Overview
- 23.2. Key Assumptions and Methodology
- 23.3. Non-Viral Transfection Reagents and Systems Market: Distribution by Geographical Regions
- 23.3.1. Non-Viral Transfection Reagents and Systems Market in North America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.1.1. Non-Viral Transfection Reagents and Systems Market in the US, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.1.2. Non-Viral Transfection Reagents and Systems Market in Canada, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2. Non-Viral Transfection Reagents and Systems Market in Europe, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2.1. Non-Viral Transfection Reagents and Systems Market in Germany, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2.2. Non-Viral Transfection Reagents and Systems Market in France, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2.3. Non-Viral Transfection Reagents and Systems Market in the UK, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2.4. Non-Viral Transfection Reagents and Systems Market in Italy, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2.5. Non-Viral Transfection Reagents and Systems Market in Spain, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.2.6. Non-Viral Transfection Reagents and Systems Market in Rest of Europe, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.3. Non-Viral Transfection Reagents and Systems Market in Asia-Pacific, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.3.1. Non-Viral Transfection Reagents and Systems Market in Japan, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.3.2. Non-Viral Transfection Reagents and Systems Market in Australia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.3.3. Non-Viral Transfection Reagents and Systems Market in South Korea, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.3.4. Non-Viral Transfection Reagents and Systems Market in China, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.3.5. Non-Viral Transfection Reagents and Systems Market in Rest of Asia-Pacific, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.4. Non-Viral Transfection Reagents and Systems Market in Middle East and Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.4.1. Non-Viral Transfection Reagents and Systems Market in Saudi Arabia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.4.2. Non-Viral Transfection Reagents and Systems Market in UAE, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.4.3. Non-Viral Transfection Reagents and Systems Market in Egypt, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.4.4. Non-Viral Transfection Reagents and Systems Market in Rest of Middle East and Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.5. Non-Viral Transfection Reagents and Systems Market in Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.5.1. Non-Viral Transfection Reagents and Systems Market in Brazil, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.5.2. Non-Viral Transfection Reagents and Systems Market in Argentina, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.5.3. Non-Viral Transfection Reagents and Systems Market in Rest of Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.3.1. Non-Viral Transfection Reagents and Systems Market in North America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- 23.4. Market Dynamics Assessment
- 23.4.1. Market Movement Analysis
- 23.4.2. Penetration-Growth (P-G) Matrix
- 23.5. Data Triangulation and Validation
24. CONCLUDING REMARKS
25. EXECUTIVE INSIGHTS
- 25.1. Chapter Overview
- 25.2. Company A
- 25.2.1. Interview Transcript: Former Vice President, Business Development and Partnerships
- 25.3. Company B
- 25.3.1. Interview Transcript: Former Global Business Development Manager, Clinical Operations
- 25.4. Company C
- 25.4.1. Interview Transcript: Researcher
26. APPENDIX I: TABULATED DATA
27. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 3.1 Specifications of Viral Vectors
- Table 7.1 Non-Viral Transfection Reagents: Information on Compatible Cell Type / Line and Volume of Reagent (per unit DNA / RNA)
- Table 7.2 Non-Viral Transfection Reagents: Information on Transfected Molecule and Type of Transfection Carrier Used
- Table 7.3 Non-Viral Transfection Reagents: Information on Type of Cell Culture and Serum Compatibility
- Table 7.4 Non-Viral Transfection Reagents: List of Providers
- Table 8.1 Electroporation-based Transfection Systems: Information on Compatible Cell Type / Line and Transfected Molecule
- Table 8.2 Electroporation-based Transfection Systems: Information on Type of Waveform and Pulse Voltage
- Table 8.3 Electroporation-based Transfection Systems: Information on Pulse Time, Efficiency, Cell Viability and Reaction Time
- Table 8.4 Electroporation-based Transfection Systems: List of Providers
- Table 9.1 Other Non-Viral Transfection Systems: Information on Type of Offering, Compatible Cell Type / Line, and Transfected Molecule
- Table 9.2 Other Non-Viral Transfection Technology / System Providers: Information on Year of Establishment, Company Size and Location of Headquarters
- Table 12.1 List of Non-viral Transfection Reagents, Systems, and Technology Providers Profiled
- Table 12.2 MilliporeSigma: Company Overview
- Table 12.3 MilliporeSigma: Non-viral Transfection Reagents Portfolio
- Table 12.4 MilliporeSigma: Recent Developments and Future Outlook
- Table 12.5 OZ Biosciences: Company Overview
- Table 12.6 OZ Biosciences: Non-viral Transfection Reagents Portfolio
- Table 12.7 Thermo Fisher Scientific: Company Overview
- Table 12.8 Thermo Fisher Scientific: Non-viral Transfection Reagents Portfolio
- Table 12.9 Thermo Fisher Scientific: Recent Developments and Future Outlook
- Table 12.10 BEX: Company Overview
- Table 12.11 BEX: Electroporation Systems for Non-viral Transfection
- Table 12.12 Bio-Rad Laboratories: Company Overview
- Table 12.13 Bio-Rad Laboratories: Electroporation Systems for Non-viral Transfection
- Table 12.14 Bio-Rad Laboratories: Recent Developments and Future Outlook
- Table 12.15 Harvard Bioscience: Company Overview
- Table 12.16 Harvard Bioscience: Electroporation Systems for Non-viral Transfection
- Table 12.17 Harvard Bioscience: Recent Developments and Future Outlook
- Table 12.18 MaxCyte: Company Overview
- Table 12.19 MaxCyte: Electroporation Systems for Non-Viral Transfection
- Table 12.20 MaxCyte: Recent Developments and Future Outlook
- Table 12.21 Nepa Gene: Company Overview
- Table 12.22 Nepa Gene: Electroporation Systems for Non-viral Transfection
- Table 12.23 LocateBio: Company Overview
- Table 12.24 LocateBio: Non-viral Transfection System / Technology
- Table 12.25 N4 Pharma: Company Overview
- Table 12.26 N4 Pharma: Non-viral Transfection System / Technology
- Table 12.27 N4 Pharma: Recent Developments and Future Outlook
- Table 13.1 Most Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in North America
- Table 13.2 Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in North America
- Table 13.3 Less Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in North America
- Table 13.4 Least Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in North America
- Table 13.5 Most Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Europe
- Table 13.6 Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Europe
- Table 13.7 Less Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Europe
- Table 13.8 Least Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Europe
- Table 13.9 Most Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Asia-Pacific and Rest of the World
- Table 13.10 Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Asia-Pacific and Rest of the World
- Table 13.11 Less Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Asia-Pacific and Rest of the World
- Table 13.12 Least Likely Partners for Non-Viral Transfection Reagent and System Providers Headquartered in Europe
- Table 15.1 Patent Analysis: Top CPC Sections
- Table 15.2 Patent Analysis: Top CPC Symbols
- Table 15.3 Patent Analysis: Top CPC Codes
- Table 15.4 Patent Analysis: Categorization based on Weighted Valuation Scores
- Table 15.5 Patent Portfolio: List of Leading Patents (by Highest Relative Valuation)
- Table 17.1 Product Price Evaluation Matrix: Based on Transfection Efficiency (USD)
- Table 17.2 Product Price Evaluation Matrix: Based on Compatible Cell Type (USD)
- Table 17.3 Product Price Evaluation Matrix: Based on Type of Carrier Used (USD)
- Table 17.4 Product Price Evaluation Matrix: Based on Type of Molecule Delivered (USD)
- Table 17.5 Product Price Evaluation Matrix: Based on Serum Compatibility (USD)
- Table 17.6 Product Price Evaluation Matrix: Based on Transfection Efficiency (USD)
- Table 17.7 Product Price Evaluation Matrix: Based on Compatible Cell Type
- Table 17.8 Product Price Evaluation Matrix: Based on Type of Carrier Used (USD)
- Table 17.9 Product Price Evaluation Matrix: Based on Type of Molecule Delivered (USD)
- Table 17.10 Product Price Evaluation Matrix: Based on Serum Compatibility (USD)
- Table 25.1 Non-Viral Transfection Reagents: Distribution by Compatible Cell Type / Line
- Table 25.2 Non-Viral Transfection Reagents: Distribution by Transfected Molecule
- Table 25.3 Non-Viral Transfection Reagents: Distribution by Type of Transfection Carrier Used
- Table 25.4 Non-Viral Transfection Reagents: Distribution by Type of Cell Culture
- Table 25.5 Non-Viral Transfection Reagents: Distribution by Serum Compatibility
- Table 25.6 Non-Viral Transfection Reagent Providers: Distribution by Year of Establishment
- Table 25.7 Non-Viral Transfection Reagent Providers: Distribution by Company Size
- Table 25.8 Non-Viral Transfection Reagent Providers: Distribution by Location of Headquarters
- Table 25.9 Electroporation-based Transfection Systems: Distribution by Compatible Cell Type / Line
- Table 25.10 Electroporation-based Transfection Systems: Distribution by Transfected Molecule
- Table 25.11 Electroporation-based Transfection Systems: Distribution by Type of Waveform
- Table 25.12 Electroporation-based Transfection Systems: Cumulative Distribution by Pulse Voltage
- Table 25.13 Electroporation-based Transfection System Providers: Distribution by Year of Establishment
- Table 25.14 Electroporation-based Transfection System Providers: Distribution by Company Size
- Table 25.15 Electroporation-based Transfection System Providers: Distribution by Location of Headquarters
- Table 25.16 Leading Players: Number of Electroporation-based Transfection System Offered
- Table 25.17 Other Non-Viral Transfection Technology / Systems: Distribution by Type of Offering
- Table 25.18 Other Non-Viral Transfection Technology / Systems: Distribution by Compatible Cell Type / Line
- Table 25.19 Other Non-Viral Transfection Technology / Systems: Distribution by Transfected Molecule
- Table 25.20 Other Non-Viral Transfection Technology / System Providers: Distribution by Year of Establishment
- Table 25.21 Other Non-Viral Transfection Technology / System Providers: Distribution by Company Size
- Table 25.22 Other Non-Viral Transfection Technology / System Providers: Distribution by Location of Headquarters
- Table 25.23 Patent Analysis: Distribution by Type of Patent
- Table 25.24 Patent Analysis: Cumulative Distribution by Patent Publication Year, 2022-2025
- Table 25.25 Patent Analysis: Cumulative Distribution by Patent and Patent Publication Year, 2022-2025
- Table 25.26 Patent Analysis: Cumulative Distribution by Patent Application Year, Pre-2022-2025
- Table 25.27 Patent Analysis: Distribution by Patent Jurisdiction
- Table 25.28 Patent Analysis: Cumulative Year-wise Distribution by Type of Applicant, 2022-2025
- Table 25.29 Leading Players: Distribution by Number of Patents
- Table 25.30 Leading Inventors: Distribution by Number of Patents
- Table 25.31 Patent Analysis: Distribution by Patent Age
- Table 25.32 Publication Analysis: Cumulative Year-wise Trend, 2020-2025
- Table 25.33 Most Active Publisher: Distribution by Number of Publications
- Table 25.34 Key Journals: Distribution by Journal Impact Factor
- Table 25.35 Most Popular Journals: Distribution by Number of Publications
- Table 25.36 Prominent Copyright Holders: Distribution by Number of Publications
- Table 25.37 Global Non-Viral Transfection Reagents and Systems Market, Historical Trends Since 2022 and Forecasted Estimates Till 2035: Base Scenario (USD Billion)
- Table 25.38 Global Non-Viral Transfection Reagents and Systems Market, Forecasted Estimates Till 2035: Conservative Scenario (USD Billion)
- Table 25.39 Global Non-Viral Transfection Reagents and Systems Market, Forecasted Estimates Till 2035: Optimistic Scenario (USD Billion)
- Table 25.40 Non-Viral Transfection Reagents and Systems Market: Distribution by Type of Transfected Method
- Table 25.41 Non-Viral Transfection Reagents and Systems Market for Chemical Methods, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.42 Non-Viral Transfection Reagents and Systems Market for Physical Methods, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.43 Non-Viral Transfection Reagents and Systems Market for Other Methods, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.44 Non-Viral Transfection Reagents and Systems Market: Distribution by Application Area
- Table 25.45 Non-Viral Transfection Reagents and Systems Market for Research Applications, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.46 Non-Viral Transfection Reagents and Systems Market for Clinical Applications, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.47 Non-Viral Transfection Reagents and Systems Market: Distribution by End-Users
- Table 25.48 Non-Viral Transfection Reagents and Systems Market for Academic and Research Institutes, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.49 Non-Viral Transfection Reagents and Systems Market for Pharmaceutical and Biopharmaceutical Companies, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.50 Non-Viral Transfection Reagents and Systems Market for Contract Manufacturers, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.51 Non-Viral Transfection Reagents and Systems Market for Other End-Users, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.52 Non-Viral Transfection Reagents and Systems Market: Distribution by Geographical Regions
- Table 25.53 Non-Viral Transfection Reagents and Systems Market in North America, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.54 Non-Viral Transfection Reagents and Systems Market in the US, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.55 Non-Viral Transfection Reagents and Systems Market in Canada, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.56 Non-Viral Transfection Reagents and Systems Market in Europe, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.57 Non-Viral Transfection Reagents and Systems Market in Germany, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.58 Non-Viral Transfection Reagents and Systems Market in France, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.59 Non-Viral Transfection Reagents and Systems Market in the UK, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.60 Non-Viral Transfection Reagents and Systems Market in Italy, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.61 Non-Viral Transfection Reagents and Systems Market in Spain, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.62 Non-Viral Transfection Reagents and Systems Market in Rest of Europe, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.63 Non-Viral Transfection Reagents and Systems Market in Asia-Pacific, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.64 Non-Viral Transfection Reagents and Systems Market in Japan, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.65 Non-Viral Transfection Reagents and Systems Market in Australia, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.66 Non-Viral Transfection Reagents and Systems Market in South Korea, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.67 Non-Viral Transfection Reagents and Systems Market in China, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.68 Non-Viral Transfection Reagents and Systems Market in Rest of Asia-Pacific, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.69 Non-Viral Transfection Reagents and Systems Market in Middle East and Africa, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.70 Non-Viral Transfection Reagents and Systems Market in Saudi Arabia, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.71 Non-Viral Transfection Reagents and Systems Market in UAE, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.72 Non-Viral Transfection Reagents and Systems Market in Egypt, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.73 Non-Viral Transfection Reagents and Systems Market in Rest of Middle East and Africa, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.74 Non-Viral Transfection Reagents and Systems Market in Latin America, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.75 Non-Viral Transfection Reagents and Systems Market in Brazil, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.76 Non-Viral Transfection Reagents and Systems Market in Argentina, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 25.77 Non-Viral Transfection Reagents and Systems Market in Rest of Latin America, Forecasted Estimates Till 2035, Conservative, Base and Optimistic Scenarios (USD Billion)
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 2.3 Research Methodology: Robust Quality Control
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Market Assessment Framework
- Figure 4.1 Lessons Learnt from Past Recessions
- Figure 5.1 Executive Summary: Market Landscape
- Figure 5.2 Executive Summary: Market Trends
- Figure 5.3 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 6.1 Commonly Used Viral Vectors
- Figure 6.2 Types of Non-Viral Transfection Methods
- Figure 6.3 Electroporation Mechanism
- Figure 6.4 Gene Gun Mechanism
- Figure 6.5 Sonoporation Mechanism
- Figure 6.6 Microinjection Mechanism
- Figure 6.7 Magnetofection Mechanism
- Figure 6.8 Applications of Transfection
- Figure 7.1 Non-viral Transfection Reagents: Distribution by Compatible Cell Type / Line
- Figure 7.2 Non-Viral Transfection Reagents: Distribution by Transfected Molecule
- Figure 7.3 Non-Viral Transfection Reagents: Distribution by Type of Transfection Carrier Used
- Figure 7.4 Non-Viral Transfection Reagents: Distribution by Type of Cell Culture
- Figure 7.5 Non-Viral Transfection Reagents: Distribution by Serum Compatibility
- Figure 7.6 Non-Viral Transfection Reagent Providers: Distribution by Year of Establishment
- Figure 7.7 Non-Viral Transfection Reagent Providers: Distribution by Company Size
- Figure 7.8 Non-Viral Transfection Reagent Providers: Distribution by Location of Headquarters
- Figure 8.1 Electroporation-based Transfection Systems: Distribution by Compatible Cell Type / Line
- Figure 8.2 Electroporation-based Transfection Systems: Distribution by Transfected Molecule
- Figure 8.3 Electroporation-based Transfection Systems: Distribution by Type of Waveform
- Figure 8.4 Electroporation-based Transfection Systems: Cumulative Distribution by Pulse Voltage
- Figure 8.5 Electroporation-based Transfection System Providers: Distribution by Year of Establishment
- Figure 8.6 Electroporation-based Transfection System Providers: Distribution by Company Size
- Figure 8.7 Electroporation-based Transfection System Providers: Distribution by Location of Headquarters
- Figure 8.8 Leading Players: Distribution by Number of Electroporation-based Transfection Systems Offered
- Figure 9.1 Other Non-Viral Transfection Technologies / Systems: Distribution by Type of Offering
- Figure 9.2 Other Non-Viral Transfection Technologies / Systems: Distribution by Compatible Cell Type / Line
- Figure 9.3 Other Non-Viral Transfection Technology / Systems: Distribution by Transfected Molecule
- Figure 9.4 Other Non-Viral Transfection Technology / System Providers: Distribution by Year of Establishment
- Figure 9.5 Other Non-Viral Transfection Technology / System Providers: Distribution by Company Size
- Figure 9.6 Other Non-Viral Transfection Technology / System Providers: Distribution by Location of Headquarters
- Figure 10.1 Company Competitiveness Analysis: Non-Viral Transfection Reagent Providers based in North America (Peer Group I)
- Figure 10.2 Company Competitiveness Analysis: Non-Viral Transfection Reagent Providers based in Europe (Peer Group II)
- Figure 10.3 Company Competitiveness Analysis: Non-Viral Transfection Reagent Providers based in Asia-Pacific (Peer Group III)
- Figure 11.1 Electroporation-based Systems: Distribution of Technologies Offered by Players based in North America (Peer Group Ia)
- Figure 11.2 Electroporation-based Systems Distribution of Technologies Offered by Players based in Europe and Asia-Pacific (Peer Group Ib)
- Figure 11.3 Other Non-Viral Transfection Technologies / Systems: Distribution of Technologies Offered by Players based in North America (Peer Group IIa)
- Figure 11.4 Other Non-Viral Transfection Technologies / Systems: Distribution of Technologies Offered by Players based in Europe and Asia-Pacific (Peer Group IIb)
- Figure 12.1 MilliporeSigma: Annual Revenues(EUR Billion)
- Figure 12.2 Thermo Fisher Scientific: Business Segment-wise Annual Revenues(USD Billion)
- Figure 12.3 Bio-Rad Laboratories: Business Segment-wise Annual Revenues(USD Million)
- Figure 12.4 Harvard Bioscience: Business Segment-wise Annual Revenues(USD Million)
- Figure 12.5 MaxCyte: Business Segment-wise Annual Revenues(USD Billion)
- Figure 15.1 Patent Analysis: Distribution by Type of Patent
- Figure 15.2: Patent Analysis: Cumulative Distribution by Patent Publication Year, 2022-2025
- Figure 15.3 Patent Analysis: Distribution by Type of Patent and Publication Year, 2022-2025
- Figure 15.4 Patent Analysis: Distribution by Patent Application Year, Pre-2022-2025
- Figure 15.5 Patent Analysis: Distribution by Patent Jurisdiction
- Figure 15.6 Patent Analysis: Distribution by CPC Symbols
- Figure 15.7 Patent Analysis: Cumulative Year-wise Distribution by Type of Applicant, 2022-2025
- Figure 15.8 Leading Players: Distribution by Number of Patents
- Figure 15.9 Leading Inventors: Distribution by Number of Patents
- Figure 15.10 Patent Benchmarking Analysis: Distribution of Patent Characteristics (CPC Codes) by Leading Players
- Figure 15.11 Patent Benchmarking Analysis: Distribution of Leading Players by Patent Characteristics (CPC Codes)
- Figure 15.12 Patent Analysis: Distribution by Patent Age
- Figure 15.13 Non-Viral Transfection: Patent Valuation
- Figure 16.1 Publication Analysis: Cumulative Year-wise Trend, 2020-2025
- Figure 16.2 Most Active Publisher: Distribution by Number of Publication
- Figure 16.3 Key Journals: Distribution by Journal Impact Factor
- Figure 16.4 Most Popular Journals: Distribution by Number of Publications
- Figure 16.5 Prominent Copyright Holders: Distribution by Number of Publications
- Figure 17.1 Non-Viral Transfection Reagents: Roots Analysis Pricing Strategy Graphical Interpretation
- Figure 17.2 Non-Viral Transfection Reagents: Roots Analysis Pricing Strategy Graphical Interpretation
- Figure 19.1 Global Non-Viral Transfection Reagents and Systems Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.2 Global Non-Viral Transfection Reagents and Systems Market, Forecasted Estimates Till 2035, Conservative Scenario (USD Billion)
- Figure 19.3 Global Non-Viral Transfection Reagents and Systems Market, Forecasted Estimates Till 2035, Optimistic Scenario (USD Billion)
- Figure 20.1 Non-Viral Transfection Reagents and Systems Market: Distribution by Type of Transfection Method
- Figure 20.2 Non-Viral Transfection Reagents and Systems Market for Chemical Methods, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 20.3 Non-Viral Transfection Reagents and Systems Market for Physical Methods, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 20.4 Non-Viral Transfection Reagents and Systems Market for Other Methods, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 21.1 Non-Viral Transfection Reagents and Systems Market: Distribution by Application Area
- Figure 21.2 Non-Viral Transfection Reagents and Systems Market for Research Applications, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 21.3 Non-Viral Transfection Reagents and Systems Market for Clinical Applications, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 22.1 Non-Viral Transfection Reagents and Systems Market: Distribution by End-User
- Figure 22.2 Non-Viral Transfection Reagents and Systems Market for Academic and Research Institutes, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 22.3 Non-Viral Transfection Reagents and Systems Market for Pharmaceutical and Biopharmaceutical Companies, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 22.4 Non-Viral Transfection Reagents and Systems Market for Contract Manufacturers, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 22.5 Non-Viral Transfection Reagents and Systems Market for Other End-Users, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.1 Non-Viral Transfection Reagents and Systems Market: Distribution by Geographical Regions
- Figure 23.2 Non-Viral Transfection Reagents and Systems Market in North America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.3 Non-Viral Transfection Reagents and Systems Market in the US, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.4 Non-Viral Transfection Reagents and Systems Market in Canada, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.5 Non-Viral Transfection Reagents and Systems Market in Europe, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.6 Non-Viral Transfection Reagents and Systems Market in Germany, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.7 Non-Viral Transfection Reagents and Systems Market in France, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.8 Non-Viral Transfection Reagents and Systems Market in the UK, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.9 Non-Viral Transfection Reagents and Systems Market in Italy, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.10 Non-Viral Transfection Reagents and Systems Market in Spain, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.11 Non-Viral Transfection Reagents and Systems Market in Rest of Europe, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.12 Non-Viral Transfection Reagents and Systems Market in Asia-Pacific, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.13 Non-Viral Transfection Reagents and Systems Market in Japan, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.14 Non-Viral Transfection Reagents and Systems Market in Australia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.15 Non-Viral Transfection Reagents and Systems Market in South Korea, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.16 Non-Viral Transfection Reagents and Systems Market in China, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.17 Non-Viral Transfection Reagents and Systems Market in Rest of Asia-Pacific, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.18 Non-Viral Transfection Reagents and Systems Market in Middle East and Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.19 Non-Viral Transfection Reagents and Systems Market in Saudi Arabia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.20 Non-Viral Transfection Reagents and Systems Market in UAE, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.21 Non-Viral Transfection Reagents and Systems Market in Egypt, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.22 Non-Viral Transfection Reagents and Systems Market in Rest of Middle East and Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.23 Non-Viral Transfection Reagents and Systems Market in Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.24 Non-Viral Transfection Reagents and Systems Market in Brazil, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.25 Non-Viral Transfection Reagents and Systems Market in Argentina, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.26 Non-Viral Transfection Reagents and Systems Market in Rest of Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 23.27 Market Movement Analysis: Geographical Regions
- Figure 23.28 Penetration-Growth (P-G) Matrix: Geographical Regions
- Figure 24.1 Concluding Remarks: Overall Market Landscape of Non-Viral Transfection Reagents
- Figure 24.2 Concluding Remarks: Overall Market Landscape of Electroporation-based Non-Viral Transfection Systems
- Figure 24.3 Concluding Remarks: Overall Market Landscape of Other Non-Viral Transfection Technologies / Systems
- Figure 24.4 Concluding Remarks: Patent Analysis
- Figure 24.5 Concluding Remarks: Market Sizing and Opportunity Analysis

 全球病毒載體生產市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 基因遞送平台市場:按遞送平台、載體類型、應用、最終用戶和地區分類
 病毒載體市場規模、佔有率和成長分析:按載體類型、應用、適應症、最終用戶和地區分類-2026-2033年產業預測
 AAV包裝服務市場:按容器類型、包裝材料、尺寸、交貨方式、應用和最終用戶分類 - 全球預測 2026-2032
 病毒載體市場規模、佔有率和趨勢分析報告:按載體類型、應用、最終用途、地區和細分市場預測(2026-2033 年)腺病毒純化試劑盒市場按技術、規格、等級、應用和最終用戶分類-全球預測(2026-2032 年)
 腺結合病毒(AAV)媒介市場:產業趨勢和全球預測 - 各治療類型,各治療領域,各給藥途徑,各產業規模,各地區
 病毒載體疫苗市場(按疾病、按類型、按最終用戶、按國家和地區)-2025 年至 2032 年全球產業分析、市場規模、市場佔有率及預測
 病毒·非病毒載體的全球市場:2024年