


 |
市場調查報告書
商品編碼
2157018
印尼全軌道公路(FTL):市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)Indonesia Full-Truck-Load (FTL) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
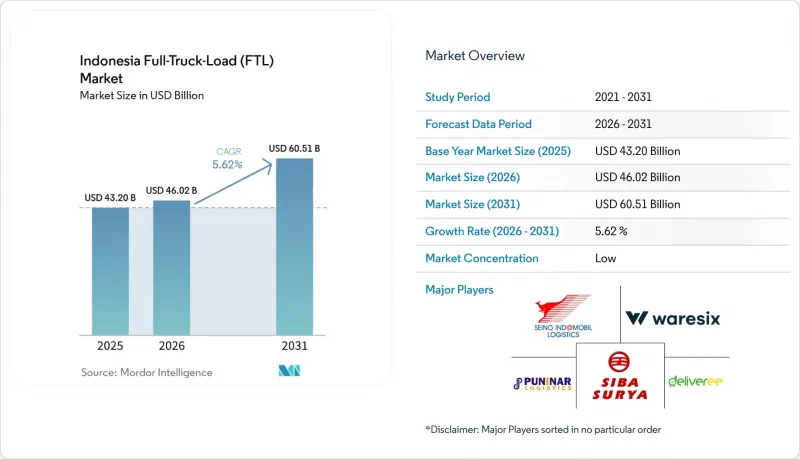
據 Mordor Intelligence 稱,2025 年印尼整車運輸 (FTL) 市場價值為 432 億美元,預計到 2031 年將達到 605.1 億美元,而 2026 年為 460.2 億美元,預測期(2026-2031 年)的複合年成長率為 5.62%。
印尼整車運輸市場趨勢與洞察
國內物流生態系和更快的門到港處理速度
印尼國家物流生態系統徹底改變了港口系統與道路運輸者之間的貨物運輸方式。該專案簡化了文書工作,使承運商能夠更清晰地了解貨物交付狀態。單一提交流程減少了船舶清關、貨物清關和許可證申請中的重複提交。自動化閘口的QR碼認證也減少了人工檢查,從而縮短了卡車發車時間。印尼整車運輸 (FTL) 市場將從中受益,因為營運商可以根據更可靠的出港時間安排卡車,並透過利用數位化回程傳輸配對來減少車輛閒置時間。
電子商務、現代零售和直接分銷的擴張。
隨著電子商務、現代零售和直銷模式的擴張,工廠、區域樞紐和門市之間準時運輸的需求日益成長。製造商擴大選擇將整車貨物直接運送至配送中心,而不是依賴多批發商模式。這種方式使托運人能夠更精準地控制交貨時間,並增加專用貨車路線的班次。收費公路的擴建透過縮短現有路線的行駛時間並改善工業走廊的交通狀況,為這一轉變提供了支持。公共工程及住宅部計劃在2025年至2029年間建設總計2,461公里的收費公路,其中爪哇島1,306公里,蘇門答臘島1,112公里。預計在新建公路網連接製造群、物流樞紐和大規模消費中心的地區,印尼整車運輸(FTL)市場將迎來最大成長。
港口大門出口擁擠和不可預測的停留時間
在印尼主要貨櫃門戶丹戎不碌港,港口延誤仍是限制卡車運輸效率的直接因素。根據印尼海關總署的報告,預計到2025年,將有近1萬個貨櫃在丹戎不碌港長期滯留,高峰期擁擠時將有3100份文件無法處理。據報道,丹戎不碌港的延誤時間為6-7天,而港口當局設定的目標是3-4天。等待不確定的清關時間意味著卡車白白浪費了一整天的時間,而這原本可以用於生產性作業。此外,確保特定路線和倉庫內的貨物安全需要監控、駕駛人管理以及確保安全的停車位,而高價值貨物還會產生額外的成本和營運要求。
細分市場分析
到2025年,印尼國內貨運將佔印尼整車運輸市場佔有率的62.89%。爪哇島、蘇門答臘島和蘇拉威西島的島嶼物流和消費需求支撐了這一規模。食品補給、現代零售週期和製造業供應鏈推動了雅加達-泗水、棉蘭-巨港和望加錫-帕盧等路線的定期整車運輸。這些成熟的路線為承運商提供了頻繁的裝貨機會,並使托運人能夠比共乘運輸更精確地控制交貨時間。由於需求穩定且路線熟悉,國內運輸服務仍是許多業者的重要業務基礎。
國際貨運是成長最快的行業,預計到2031年將以6.65%的複合年成長率成長。爪哇島的出口型製造商利用保稅卡車運輸路線將貨物運往帕蒂芒和丹戎不碌,而跨境電子商務的履約也需要高效率的運輸方式將貨物送達保稅物流中心。 「國家物流生態系統」可以簡化與這些運輸相關的文書工作。 DHL表示,未來五年,印尼將躋身全球貿易成長率和貿易量前30名的國家。隨著保稅運輸、港口准入和製造商調度協同運作,形成一個完整的系統,印尼整車運輸(FTL)市場預計將進一步成長。
到2025年,乾貨運輸將佔印尼整車運輸市場規模的81.36%。煤炭、棕櫚油、水泥、包裝商品和其他散裝貨物將佔據這一需求的大部分。標準乾貨運輸競爭激烈,因此在高密度運輸路線上,燃油效率、駕駛員生產力和可靠的班次管理至關重要。雖然乾貨市場規模龐大且運輸量穩定,但在成熟路線上,差異化優勢有限。運輸商必須在控制成本的同時,保持可靠的運輸能力,以確保獲利。
冷藏貨物運輸是需要溫控的領域中成長最快的,預計2031年複合年成長率將達到7.39%。這一成長主要受藥品運輸、現代食品零售以及蘇拉威西島和東爪哇島水產養殖產品分銷等需求的推動。在島際運輸路線上,電力連接和冷藏倉庫並非總是唾手可得。配備冷藏車輛、監控系統和相應港口流程的營運商可以滿足更專業的客戶群。在印尼的整車運輸(FTL)產業,冷藏運輸的進入門檻高於傳統乾貨運輸。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
- 市場規模、成長率與未來預測
- 主要需求因素和業務趨勢
- 關鍵細分市場和整車運輸需求模式評估
- 競爭格局與主要FTL服務供應商
第4章 市場狀況
- 市場概況及整車運輸的重要性
- 市場促進因素
- 國內物流生態系和更快的門到港處理速度
- 電子商務、現代零售和直銷的擴張
- 改善收費公路與工業走廊之間的連結性
- 擴大國內藥品及生技藥品冷鏈
- 蘇拉威西島上從鎳到電池製造的走廊
- 最佳化數位回程傳輸並提高軌道運轉率
- 市場限制因素
- 港口大門外交通堵塞,等待時間難以預測。
- 零超尺寸超載合規成本
- 每條航線的貨物竊盜和安全附加費
- 缺乏島際交通和冷藏運輸服務的基礎設施。
- 價值鏈結構與供應鏈動態分析
- 陸上貨運的法律規範和合規狀況
- FTL技術採用和數位化趨勢
- 道路交通及貨運配送狀況
- 對 FTL 票價和定價結構的分析
- 燃油價格趨勢及其對陸上貨運成本的影響
- 主要輕軌走廊及路線密度分析
- 評估港口連通性和卡車運輸流量至內陸地區
- 波特五力分析
- 地緣政治事件對供應鏈轉型的影響
第5章 市場規模與成長預測
- 按目的地
- 國內的
- 國際的
- 按類型進行溫度控制
- 乾燥
- 冷藏貨櫃
- 按運輸距離
- 長途(500英里或以上)
- 按地區(100-500英里)
- 近距離(不到100英里)
- 按最終用戶行業分類
- 農業
- 漁業和林業
- 建造
- 製造業
- 石油和天然氣
- 採礦和採石
- 批發和零售
- 其他
- 按地區
- 爪哇島(雅加達和博多)
- 蘇門答臘
- 加里曼丹
- 蘇拉威西
- 峇裡島和努沙登加拉
- 巴布亞地區和摩鹿加群島
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- PT Seino Indomobil Logistics
- Waresix
- Puninar Logistics
- Deliveree Indonesia
- PT Siba Surya
- Kargo Technologies
- DHL Group
- PT Dunia Express Transindo(DUNEX Logistics)
- DSV A/S
- GEODIS
- PT Kamadjaja Logistics
- PT Serasi Logistics Indonesia(SELOG)
- Pancaran Group
- PT Cipta Krida Bahari(CKB Logistics)
- PT Samudera Indonesia Tbk
- PT Iron Bird Logistics
- Lalamove Indonesia
- PT CJ Logistics Indonesia
- PT Rhenus Logistics Indonesia
- PT BGR Logistik Indonesia
- PT Amanat Perkasa Speed(Total Logistics)
- PT Indah Logistik
第7章 市場機會與未來展望
第8章附錄
According to Mordor Intelligence, the Indonesia full-truck-load (FTL) market size was valued at USD 43.20 billion in 2025, and is estimated to grow from USD 46.02 billion in 2026 to reach USD 60.51 billion by 2031, at a CAGR of 5.62% during the forecast period (2026-2031).
Indonesia Full-Truck-Load (FTL) Market Trends and Insights
National Logistics Ecosystem and Faster Door-to-Port Processing
Indonesia's National Logistics Ecosystem has changed the way cargo moves between port systems and road carriers. The program streamlines documentation and gives carriers a clearer view of cargo release activity. Its single-submission process reduces repeated submissions for vessel clearance, goods clearance, and licensing. QR-code authorization at autogates can also reduce manual checks that delay truck departures. The Indonesia full-truck-load (FTL) market benefits when operators can schedule trucks around more reliable gate-out times and use digital backhaul matching to limit empty trips.
E-Commerce, Modern Retail, and Direct Distribution Expansion
E-commerce, modern retail, and direct distribution are increasing the need for scheduled freight between factories, regional hubs, and stores. Manufacturers are increasingly sending full loads to distribution centers rather than relying on several layers of wholesale handling. This approach gives shippers more control over delivery timing and can increase the frequency of dedicated truck lanes. Toll-road expansion supports this shift by lowering travel times on established routes and improving access to industrial corridors. The Ministry of Public Works and Public Housing planned 2,461 km of toll-road development for 2025-2029, including 1,306 km in Java and 1,112 km in Sumatra. The Indonesia full-truck-load (FTL) market is likely to gain the most where new road capacity connects manufacturing clusters, logistics nodes, and large consumption centers.
Port Gate-Out Congestion and Unpredictable Dwell Time
Port delays remain a direct constraint on truck productivity at Indonesia's main container gateways. Indonesia's Directorate General of Customs and Excise reported that nearly 10,000 containers were in longstay status at Tanjung Priok during 2025, and 3,100 documents were pending during the peak of the congestion. Reported dwell time at Tanjung Priok was 6-7 days, compared with the port authority's 3-4 day target. A truck waiting for an uncertain release window can lose a full day that would otherwise be available for a productive trip. Cargo security on selected corridors and at warehouses also requires monitoring, driver controls, and secure parking, adding cost and operating requirements for high-value freight.
Other drivers and restraints analyzed in the detailed report include:
- Domestic Pharmaceutical and Biologics Cold-Chain Scaling
- Sulawesi Nickel-to-Battery Manufacturing Corridors
- Zero Over Dimension Over Loading Compliance Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Domestic freight accounted for 62.89% of Indonesia full-truck-load (FTL) market share in 2025. Intra-island distribution and consumer demand across Java, Sumatra, and Sulawesi support this scale. Grocery replenishment, modern retail cycles, and manufacturing supply chains create regular full-load movements on routes such as Jakarta-Surabaya, Medan-Palembang, and Makassar-Palu. These established lanes give carriers frequent loading opportunities and allow shippers to control delivery timing more closely than mixed-load arrangements. Domestic service remains the operating base for many providers because it combines recurring demand with familiar route conditions.
International freight is the fastest-growing destination segment, with a projected 6.65% CAGR through 2031. Export-oriented manufacturers in Java use bonded truck lanes to reach Patimban and Tanjung Priok, while cross-border e-commerce fulfillment needs efficient movement to bonded logistics centers. The National Logistics Ecosystem can simplify documentation for these movements. DHL stated that Indonesia is among the top 30 countries for trade growth in speed and scale over the following 5 years. The Indonesia full-truck-load (FTL) market gains when bonded transport, port access, and manufacturer scheduling work as a coordinated system.
Dry freight held 81.36% of Indonesia full-truck-load (FTL) market size in 2025. Coal, palm oil, cement, packaged goods, and other bulk cargoes account for much of this demand. Standard dry operations face intense rate competition, so fuel efficiency, driver productivity, and reliable scheduling are important on high-density routes. The large dry base provides steady volumes but limited differentiation on mature corridors. Carriers must maintain dependable capacity while controlling costs in order to protect returns.
Reefer freight is the fastest-growing temperature-control segment, with a projected 7.39% CAGR through 2031. Pharmaceutical requirements, modern food retail, and aquaculture distribution from Sulawesi and East Java are supporting this growth. Electrical plug-in points and cold storage are not consistently available on inter-island routes. Operators with reefer fleets, monitoring systems, and compatible port processes can serve a more specialized customer set. The Indonesia full-truck-load (FTL) industry has a higher barrier to entry in reefer operations than in standard dry freight.
Complete Report Scope:
- By Destination
- Domestic
- International
- By Temperature Control
- Dry
- Reefer
- By Haul Length
- Long-Haul (More than 500 miles)
- Regional (100-500 miles)
- Local (Less than 100 miles)
- By End-User Industry
- Agriculture
- Fishing and Forestry
- Construction
- Manufacturing
- Oil and Gas
- Mining and Quarrying
- Wholesale and Retail Trade
- Others
- By Region
- Java (Jakarta & BOD)
- Sumatra
- Kalimantan
- Sulawesi
- Bali and Nusa Tenggara
- Papua Region and Maluku Islands
List of Companies Covered in this Report:
- PT Seino Indomobil Logistics
- Waresix
- Puninar Logistics
- Deliveree Indonesia
- PT Siba Surya
- Kargo Technologies
- DHL Group
- PT Dunia Express Transindo (DUNEX Logistics)
- DSV A/S
- GEODIS
- PT Kamadjaja Logistics
- PT Serasi Logistics Indonesia (SELOG)
- Pancaran Group
- PT Cipta Krida Bahari (CKB Logistics)
- PT Samudera Indonesia Tbk
- PT Iron Bird Logistics
- Lalamove Indonesia
- PT CJ Logistics Indonesia
- PT Rhenus Logistics Indonesia
- PT BGR Logistik Indonesia
- PT Amanat Perkasa Speed (Total Logistics)
- PT Indah Logistik
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
- 3.1 Market Size, Growth, and Forecast Outlook
- 3.2 Key Demand Drivers and Operating Trends
- 3.3 Major Segments and FTL Demand Patterns Assessment
- 3.4 Competitive Landscape and Leading FTL Service Providers
4 MARKET LANDSCAPE
- 4.1 Market Overview and Importance of Full Truck Load Transportation
- 4.2 Market Drivers
- 4.2.1 National Logistics Ecosystem and Faster Door-to-Port Processing
- 4.2.2 E-Commerce, Modern Retail and Direct Distribution Expansion
- 4.2.3 Toll-Road and Industrial-Corridor Connectivity Improvements
- 4.2.4 Domestic Pharmaceutical and Biologics Cold-Chain Scaling
- 4.2.5 Sulawesi Nickel-to-Battery Manufacturing Corridors
- 4.2.6 Digital Backhaul Matching and Higher Truck Utilization
- 4.3 Market Restraints
- 4.3.1 Port Gate-Out Congestion and Unpredictable Dwell Time
- 4.3.2 Zero Over Dimension Over Loading Compliance Cost
- 4.3.3 Cargo Theft and Corridor-Specific Security Premiums
- 4.3.4 Inter-Island Handoffs and Sparse Reefer-Service Infrastructure
- 4.4 Value Chain Structure and Supply Dynamics Analysis
- 4.5 Regulatory Framework and Road Freight Compliance Landscape
- 4.6 Technology Adoption and Digitalization Trends in FTL
- 4.7 Road Traffic and Freight Flow Environment
- 4.8 FTL Freight Rates and Pricing Structure Analysis
- 4.9 Fuel Pricing Trends and Impact on Road Freight Costs
- 4.10 Major FTL Corridors and Route Density Analysis
- 4.11 Port Connectivity and Hinterland Trucking Flow Assessment
- 4.12 Porter's Five Forces Analysis
- 4.12.1 Threat of New Entrants
- 4.12.2 Bargaining Power of Buyers and Consumers
- 4.12.3 Bargaining Power of Suppliers
- 4.12.4 Threat of Substitute Services
- 4.12.5 Intensity of Competitive Rivalry
- 4.13 Impact of Geopolitical Events on Supply Chain Shifts
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Destination
- 5.1.1 Domestic
- 5.1.2 International
- 5.2 By Temperature Control
- 5.2.1 Dry
- 5.2.2 Reefer
- 5.3 By Haul Length
- 5.3.1 Long-Haul (More than 500 miles)
- 5.3.2 Regional (100-500 miles)
- 5.3.3 Local (Less than 100 miles)
- 5.4 By End-User Industry
- 5.4.1 Agriculture
- 5.4.2 Fishing and Forestry
- 5.4.3 Construction
- 5.4.4 Manufacturing
- 5.4.5 Oil and Gas
- 5.4.6 Mining and Quarrying
- 5.4.7 Wholesale and Retail Trade
- 5.4.8 Others
- 5.5 By Region
- 5.5.1 Java (Jakarta & BOD)
- 5.5.2 Sumatra
- 5.5.3 Kalimantan
- 5.5.4 Sulawesi
- 5.5.5 Bali and Nusa Tenggara
- 5.5.6 Papua Region and Maluku Islands
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 PT Seino Indomobil Logistics
- 6.4.2 Waresix
- 6.4.3 Puninar Logistics
- 6.4.4 Deliveree Indonesia
- 6.4.5 PT Siba Surya
- 6.4.6 Kargo Technologies
- 6.4.7 DHL Group
- 6.4.8 PT Dunia Express Transindo (DUNEX Logistics)
- 6.4.9 DSV A/S
- 6.4.10 GEODIS
- 6.4.11 PT Kamadjaja Logistics
- 6.4.12 PT Serasi Logistics Indonesia (SELOG)
- 6.4.13 Pancaran Group
- 6.4.14 PT Cipta Krida Bahari (CKB Logistics)
- 6.4.15 PT Samudera Indonesia Tbk
- 6.4.16 PT Iron Bird Logistics
- 6.4.17 Lalamove Indonesia
- 6.4.18 PT CJ Logistics Indonesia
- 6.4.19 PT Rhenus Logistics Indonesia
- 6.4.20 PT BGR Logistik Indonesia
- 6.4.21 PT Amanat Perkasa Speed (Total Logistics)
- 6.4.22 PT Indah Logistik
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space Opportunities and Unmet Market Needs
- 7.2 High-Potential End-User and Regional Opportunity Areas
- 7.3 Strategic Growth Priorities Across the FTL Ecosystem
- 7.4 Future Market Outlook and Emerging Demand Pockets
8 APPENDIX

 馬來西亞廂型車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 整車公路運輸市場規模、佔有率和趨勢分析報告:按卡車類型、服務、運輸方式、最終用途、地區和細分市場預測(2026-2033 年)
 2026-2030年全球卡車運輸市場
 高空作業車市場機會、成長要素、產業趨勢分析及2026-2035年預測
 卡車運輸市場:按規模、應用和區域分類
 2026年全球林業產品卡車運輸市場報告
 交通即服務 (TaaS) 市場分析及至 2035 年預測:按類型、產品、服務、技術、組件、應用、部署模式、最終用戶、模式和解決方案分類
 2026-2034年全球高空作業車市場規模、佔有率、趨勢及成長分析報告
 全球晶片製造本土化市場:預測(至2034年)-按晶片類型、本土化階段、製程技術、最終用戶和地區分類的分析
 2026-2030年全球整車運輸(FTL)市場