


 |
市場調查報告書
商品編碼
2038690
高空作業車市場機會、成長要素、產業趨勢分析及2026-2035年預測Bucket Trucks Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

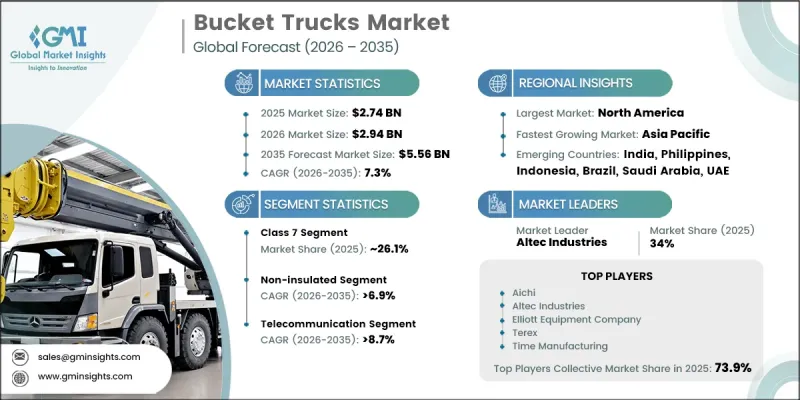
2025年全球高空作業車市場價值為27.4億美元,預計到2035年將以7.3%的複合年成長率成長至55.6億美元。
市場擴張的驅動力來自已開發經濟體和新興經濟體公共基礎建設投資的增加,以及城市維護需求的成長。對可靠配電系統、通訊網路擴展和市政服務持續改進的需求不斷成長,也顯著促進了市場成長。快速的都市化、智慧城市發展計畫以及老舊電網基礎設施的持續現代化改造,進一步提升了對先進高空作業平台的需求。過去依賴梯子等人工方式的公共產業和服務業,正擴大採用升降車等機械化升分解決方案,以提高營運效率、減少對人工的依賴,並增強高空職場的安全性。同時,對工人安全標準的日益重視和更嚴格的法規結構,也加速了多個終端用戶產業的採用。電力線路維護、通訊設備檢查和道路基礎設施維修等任務風險較高,促使企業投資更安全、更可控的作業解決方案。現代高空作業車採用絕緣臂架系統、穩定平台、符合人體工學的操作介面和增強的安全機制,即使在惡劣的工作環境中也能保持高效率和可靠性,從而實現更安全的操作。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 27.4億美元 |
| 預計金額 | 55.6億美元 |
| 複合年成長率 | 7.3% |
預計到2025年,7級起重機市佔率將達到26.1%,並在2035年之前以7.8%的複合年成長率成長。該細分市場憑藉其強大的承載能力、操作柔軟性和性能效率而佔據領先地位。由於其能夠處理重型起重系統,並在都市區和郊區環境中有效運作,因此廣泛應用於公共產業維護、通訊和市政領域。此外,該細分市場還支援液壓升降系統和加長臂作業,使其無需進行重大配置變更即可勝任眾多行業的複雜高空作業。
預計到2025年,非絕緣型高空作業車市佔率將達到57.7%,並在2026年至2035年間以6.9%的複合年成長率成長。此細分市場佔據主導地位,主要得益於其廣泛的適用性,涵蓋建築、電信、市政維護和一般服務運營等眾多行業。與絕緣型高空作業車相比,非絕緣型高空作業車因其成本效益高、設計更簡單、維護需求更低而更受歡迎。這些特性使得非絕緣型高空作業車尤其適用於無需高度防觸電的日常高空作業。
預計到2025年,美國高空作業車市場規模將達到8.244億美元,佔北美市場佔有率的83.58%。推動美國市場成長的大規模因素包括電力系統現代化改造、老舊基礎設施更換以及公共產業公共產業活動的增加。公用事業公司正在升級輸配電系統,以提高可靠性並降低停電風險,這顯著增加了高空作業平台的需求。頻繁發生的與天氣相關的電力中斷和緊急救援行動也推動了車輛需求。主要製造商的存在也促進了全國範圍內的持續產品創新和車輛現代化。
目錄
第1章:調查方法
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 電力和公共產業基礎設施的擴建
- 通訊網路的發展
- 都市化和智慧城市項目
- 重視工人安全和監管
- 產業潛在風險與挑戰
- 高昂的初始投資成本
- 維護和營運成本
- 市場機遇
- 電動和混合動力高空作業車的引進
- 新興市場的基礎建設
- 車輛現代化和更換需求
- 與智慧車隊管理系統整合
- 促進因素
- 成長潛力分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格分析(基於初步調查)
- 對過去價格趨勢的分析
- 按業務類型分類的定價策略(溢價/價值/成本加成)
- 監管指南
- 北美洲
- 美國職業安全與健康管理局高空作業平台標準(29 CFR 1910.67)
- 加拿大 - CSA C225 飛機設備標準
- 歐洲
- 德國 - DGUV 第 52 號法規(起重機和起重設備)
- 英國- LOLER 1998(關於起重作業和起重設備的法規)
- 法國 - INRS ED 828(高空作業平台指南)
- 北歐國家 - EN 280 標準(移動式高空作業平台)
- 亞太地區
- 中國GB/T 9465高空作業平台安全標準
- 印度 - IS 13367(第一部分和第二部分)高空作業平台標準
- 日本 - 工業安全衛生法(高空作業平台)
- 拉丁美洲
- 巴西 - NR-12 機械設備安全法規
- 中東和非洲(MEA)
- 沙烏地阿拉伯 - SASO ISO 16368 高空作業平台標準
- 北美洲
- 波特五力分析
- PESTEL 分析
- 專利趨勢(基於初步調查)
- 貿易數據分析(基於付費資料庫)
- 進出口量及進口額趨勢
- 主要貿易走廊和關稅的影響
- 人工智慧和生成式人工智慧對市場的影響(基於初步研究)
- 利用人工智慧改造現有經營模式
- GenAI 各細分市場的應用案例與部署藍圖
- 風險、局限性和監管考量
- 生產能力和生產趨勢(基於初步調查)
- 各地區及主要生產商的產能
- 運轉率和擴張計劃
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 環保意識的舉措
- 關於碳足跡的考量
- 預測假設和情境分析(基於初步研究)
- 基本案例-驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境-宏觀經濟與產業的順風
- 悲觀情景-宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 企業級分層基準測試
- 層級分類標準與選擇標準
- 按收入、地區和創新能力分類的層級定位矩陣。
第5章 市場估價與預測:依產品分類,2022-2035年
- 四年級
- 絕緣
- 非絕緣
- 五年級
- 絕緣
- 非絕緣
- 六年級
- 絕緣
- 非絕緣
- 七年級
- 絕緣
- 非絕緣
- 八年級
- 絕緣
- 非絕緣
第6章 市場估計與預測:依類型分類,2022-2035年
- 絕緣
- 非絕緣
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 建造
- 公共產業
- 電
- 水
- 電訊
- 林業
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 比利時
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 菲律賓
- 印尼
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲(MEA)
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第9章:公司簡介
- 世界公司
- Aichi
- Altec Industries
- Bronto Skylift
- Elliott Equipment Company
- Haulotte
- JLG Industries
- Palfinger
- Tadano
- Terex
- Time Manufacturing Company
- 當地公司
- CMC
- CTE
- Dur-A-Lift
- GSR
- Multitel Pagliero
- Niftylift
- Oil&Steel
- Platform Basket
- Posi-Plus Technologies
- Socage
- 新興企業
- Klubb
- Manitex International
- Omme Lift
- Sinoboom
- Zhejiang Dingli Machinery
The Global Bucket Trucks Market was valued at USD 2.74 billion in 2025 and is estimated to grow at a CAGR of 7.3% to reach USD 5.56 billion by 2035.
Market expansion is driven by increasing investments in utility infrastructure development and rising urban maintenance requirements across both developed and emerging economies. Growing demand for reliable electricity distribution systems, expanding telecommunication networks, and ongoing municipal service upgrades are significantly contributing to market growth. Rapid urbanization, smart city development initiatives, and continuous modernization of aging power grid infrastructure are further increasing the need for advanced aerial access equipment. Utility and service industries, which previously depended on manual lifting methods such as ladders, are increasingly adopting mechanized lifting solutions like bucket trucks to improve operational productivity, reduce labor dependency, and enhance workplace safety in elevated operations. At the same time, growing emphasis on worker safety standards and stricter regulatory frameworks is accelerating adoption across multiple end-use sectors. Activities such as power line maintenance, telecom servicing, and street infrastructure repair involve elevated risk exposure, prompting companies to invest in safer, more controlled working solutions. Modern bucket trucks now incorporate insulated boom systems, stabilized platforms, ergonomic control interfaces, and enhanced safety mechanisms, enabling safer operations while maintaining high efficiency and reliability in demanding field environments.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.74 Billion |
| Forecast Value | $5.56 Billion |
| CAGR | 7.3% |
The Class 7 segment held a 26.1% share in 2025 and is projected to grow at a CAGR of 7.8% through 2035. This segment leads the market due to its strong combination of load-handling capability, operational flexibility, and performance efficiency. It is widely deployed across utility maintenance, telecommunications, and municipal applications because it can accommodate heavy lifting systems while still operating effectively in urban and semi-urban environments. The segment also supports hydraulic lift systems and extended boom operations, making it suitable for complex elevated tasks across multiple industries without requiring major configuration changes.
The non-insulated segment accounted for 57.7% share in 2025 and is expected to grow at a CAGR of 6.9% between 2026 and 2035. This segment dominates due to its broad applicability across construction, telecom, municipal maintenance, and general service operations. It is favored for its cost efficiency, simpler design, and reduced maintenance requirements compared to insulated alternatives. These characteristics make non-insulated bucket trucks highly suitable for routine aerial operations where electrical hazard protection is not a primary operational requirement.
U.S. Bucket Trucks Market generated USD 824.4 million in 2025 and held 83.58% share in North America. Market growth in the country is being driven by extensive investments in power grid modernization, replacement of aging infrastructure, and rising utility maintenance activities. Utility operators are upgrading transmission and distribution systems to improve reliability and reduce outage risks, significantly boosting demand for aerial work platforms. Frequent weather-related disruptions and emergency restoration activities further strengthen fleet requirements. The presence of leading manufacturers also supports continuous product innovation and fleet modernization across the country.
Key companies operating in the Global Bucket Trucks Industry include Terex, Altec Industries, JLG Industries, Palfinger, Aichi, Tadano, Haulotte, Elliott Equipment Company, Bronto Skylift, and Time Manufacturing. Companies in the bucket trucks market are focusing on advancing product safety, improving operational efficiency, and integrating smart hydraulic and control systems to strengthen their competitive position. Continuous investment in R&D is enabling the development of lightweight yet high-capacity aerial platforms with improved stability and reach. Manufacturers are also prioritizing electrification and hybrid powertrain solutions to align with sustainability goals and reduce operating emissions. Expansion of rental and leasing models is helping companies increase market penetration and cater to cost-sensitive customers. Strengthening after-sales service networks and mobile maintenance support is further enhancing customer retention.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast Model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product
- 2.2.3 Type
- 2.2.4 Application
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Expansion of Power & Utility Infrastructure
- 3.2.1.2 Growth in Telecommunication Networks
- 3.2.1.3 Rising Urbanization & Smart City Projects
- 3.2.1.4 Emphasis on Worker Safety & Regulations
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Initial Investment Costs
- 3.2.2.2 Maintenance & Operational Costs
- 3.2.3 Market opportunities
- 3.2.3.1 Adoption of Electric & Hybrid Bucket Trucks
- 3.2.3.2 Emerging Markets Infrastructure Development
- 3.2.3.3 Fleet Modernization & Replacement Demand
- 3.2.3.4 Integration with Smart Fleet Management Systems
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory guideline
- 3.6.1 North America
- 3.6.1.1 US - OSHA Aerial Lift Standard (29 CFR 1910.67)
- 3.6.1.2 Canada - CSA C225 Aerial Device Standard
- 3.6.2 Europe
- 3.6.2.1 Germany - DGUV Regulation 52 (Cranes & Lifting Equipment)
- 3.6.2.2 UK - LOLER 1998 (Lifting Operations and Lifting Equipment Regulations)
- 3.6.2.3 France - INRS ED 828 (Aerial Work Platform Guidelines)
- 3.6.2.4 Nordics - EN 280 Standard (Mobile Elevating Work Platforms)
- 3.6.3 Asia Pacific
- 3.6.3.1 China - GB/T 9465 Aerial Work Platform Safety Standard
- 3.6.3.2 India - IS 13367 (Part 1 & 2) Aerial Platforms Standard
- 3.6.3.3 Japan - Industrial Safety and Health Act (Aerial Work Platforms)
- 3.6.4 Latin America
- 3.6.4.1 Brazil - NR-12 Machinery and Equipment Safety Regulation
- 3.6.5 MEA
- 3.6.5.1 Saudi Arabia - SASO ISO 16368 Aerial Work Platform Standard
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Patent Landscape (Driven by Primary Research)
- 3.10 Trade Data Analysis (Based on Paid Database)
- 3.10.1 Import/Export Volume & Value Trends
- 3.10.2 Key Trade Corridors & Tariff Impact
- 3.11 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.11.1 AI-Driven Disruption of Existing Business Models
- 3.11.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.11.3 Risks, Limitations & Regulatory Considerations
- 3.12 Capacity & Production Landscape (Driven by Primary Research)
- 3.12.1 Production Capacity by Region & Key Producer
- 3.12.2 Capacity Utilization Rates & Expansion Pipelines
- 3.13 Sustainability and environmental aspects
- 3.13.1 Sustainable practices
- 3.13.2 Waste reduction strategies
- 3.13.3 Energy efficiency in production
- 3.13.4 Eco-friendly initiatives
- 3.13.5 Carbon footprint considerations
- 3.14 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.14.1 Base Case - Key Macro & Industry Variables Driving CAGR
- 3.14.2 Optimistic Scenarios - Favourable macro and industry tailwinds
- 3.14.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company Tier Benchmarking
- 4.6.1 Tier Classification Criteria & Qualifying Thresholds
- 4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5 Market Estimates & Forecast, By Product, 2022 - 2035 ($Bn, Units)
- 5.1 Key trends
- 5.2 Class 4
- 5.2.1 Insulated
- 5.2.2 Non-insulated
- 5.3 Class 5
- 5.3.1 Insulated
- 5.3.2 Non-insulated
- 5.4 Class 6
- 5.4.1 Insulated
- 5.4.2 Non-insulated
- 5.5 Class 7
- 5.5.1 Insulated
- 5.5.2 Non-insulated
- 5.6 Class 8
- 5.6.1 Insulated
- 5.6.2 Non-insulated
Chapter 6 Market Estimates & Forecast, By Type, 2022 - 2035 ($Bn, Units)
- 6.1 Key trends
- 6.2 Insulated
- 6.3 Non-insulated
Chapter 7 Market Estimates & Forecast, By Application, 2022 - 2035 ($Bn, Units)
- 7.1 Key trends
- 7.2 Construction
- 7.3 Utility
- 7.3.1 Electric
- 7.3.2 Water
- 7.4 Telecommunication
- 7.5 Forestry
Chapter 8 Market Estimates & Forecast, By Region, 2022 - 2035 ($Bn, Units)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 US
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Italy
- 8.3.5 Spain
- 8.3.6 Russia
- 8.3.7 Netherlands
- 8.3.8 Belgium
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Philippines
- 8.4.7 Indonesia
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 MEA
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Global Players
- 9.1.1 Aichi
- 9.1.2 Altec Industries
- 9.1.3 Bronto Skylift
- 9.1.4 Elliott Equipment Company
- 9.1.5 Haulotte
- 9.1.6 JLG Industries
- 9.1.7 Palfinger
- 9.1.8 Tadano
- 9.1.9 Terex
- 9.1.10 Time Manufacturing Company
- 9.2 Regional Players
- 9.2.1 CMC
- 9.2.2 CTE
- 9.2.3 Dur-A-Lift
- 9.2.4 GSR
- 9.2.5 Multitel Pagliero
- 9.2.6 Niftylift
- 9.2.7 Oil&Steel
- 9.2.8 Platform Basket
- 9.2.9 Posi-Plus Technologies
- 9.2.10 Socage
- 9.3 Emerging Players
- 9.3.1 Klubb
- 9.3.2 Manitex International
- 9.3.3 Omme Lift
- 9.3.4 Sinoboom
- 9.3.5 Zhejiang Dingli Machinery

 馬來西亞廂型車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 全履帶公路市場機會、成長促進因素、產業趨勢分析及2026-2035年預測
 2026-2030年全球零擔運輸市場
 整車公路運輸市場規模、佔有率和趨勢分析報告:按卡車類型、服務、運輸方式、最終用途、地區和細分市場預測(2026-2033 年)
 高空作業車市場規模、佔有率和成長分析:按車輛類型、驅動方式、工作高度、裝載方式、應用、最終用戶和地區分類-2026-2033年產業預測
 2026-2030年全球卡車運輸市場商用卡車市場機會、成長要素、產業趨勢分析及2026-2035年預測
 卡車運輸市場:按規模、應用和區域分類小包裹運輸市場:依運輸重量、最終用途產業和地區分類。
 2026年全球林業產品卡車運輸市場報告