


 |
市場調查報告書
商品編碼
2155676
高性能彈性體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)High Performance Elastomer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,高性能彈性體市場在 2025 年的價值為 186.7 億美元,預計在預測期(2026-2031 年)內將以 7.15% 的複合年成長率成長,從 2026 年的 199.1 億美元成長到 2031 年的 281.2 億美元。
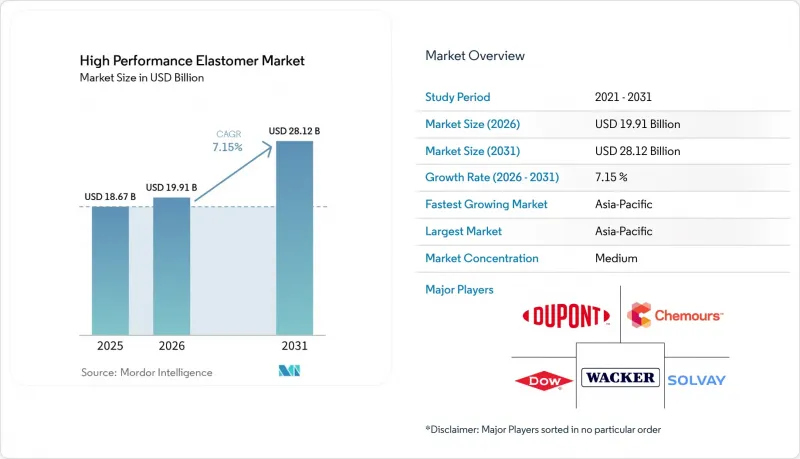
全球高性能彈性體市場趨勢與洞察
汽車電氣化和熱負荷增加
電池式電動車(BEV) 平台改變了對彈性體密封件的熱學和化學性能要求。高壓車輛系統需要絕緣和密封材料,這些材料必須在電池、馬達和充電組件所在的環境中正常運作。電池組還需要間隙填充材,以在熱循環過程中保持熱傳遞和性能。歐盟 (EU) 電池法規對廢電池組件的處置提出了材料方面的要求。瓦克化學股份公司 (Wacker Chemie AG) 推出了用於電池灌封和間隙填充的“ELASTOSIL RT 7616 TC”和“ELASTOSIL RT 7624 TC”。這些產品具有旨在減少填料沉澱的流變性能。隨著汽車專案轉向兼具電絕緣、溫度控管和持久密封性能的化合物,高性能彈性體市場正在蓬勃發展。
嚴苛條件下對密封解決方案的需求
在高溫、壓力波動、化學物質腐蝕以及維護週期長的應用場合,密封件至關重要。半導體設備、工業泵浦、化學設備和汽車系統等設備在各種不同的工況下運作,因此供應商需要相應地最佳化材料和檢驗方法。當密封件必須在嚴苛的運作條件下保持性能時,傳統的橡膠可能並不適用。這種趨勢推動了對具有可控清潔度、耐化學性和壓縮永久變形性能的專用配方的需求。此外,高性能彈性體市場不僅需要材料供應,還需要技術支持,因為客戶通常需要有關配方選擇和認證的指導。這些要求可能會使供應商更難找到替代已獲關鍵應用認證的現有材料的方案。
特殊原物料價格波動
高性能彈性體的配方依賴特殊的化學原料,這些原料未必能被標準材料取代。腈基配方易受丙烯腈價格波動的影響,而氟橡膠則依賴特殊的氟化單體。供應中斷會導致化合物價格上漲,並使供應商和買家之間的合約談判複雜化。此類價格波動也會影響汽車和工業設備項目中已指定的材料。在對價格敏感的應用領域,原物料成本上漲可能會延遲客戶在高效能彈性體市場的採購決策。擁有原料供應管道和長期採購合約的供應商,即使在供應中斷期間,也可能維持供應的連續性。
細分市場分析
到2025年,矽橡膠將佔銷售額的36.17%,成為高性能彈性體市場中佔有率最大的材料。這些材料廣泛應用於汽車溫度控管系統、醫療設備和高壓電絕緣材料。液態矽橡膠(LSR)、高溫硫化矽橡膠和室溫硫化矽橡膠分別滿足不同的加工需求。 2026年2月,杜邦公司推出了醫療設備的“Liveo C6-8XX LSR”,提供五種硬度選擇,邵氏A硬度範圍從30到70。
2026年6月,陶氏宣布了一項1億美元的特種矽酮投資計劃,其中包括在肯塔基州和中國建造液態矽橡膠生產線。預計到2031年,氟橡膠的複合年成長率將達到7.78%,在所有產品類別中成長最高。半導體銷售和化學加工活動正在推動對氟碳材料的需求,尤其是在那些氟碳材料性能難以替代的應用領域。隨著3M公司於2025年停止生產全氟烷基物質(PFAS)和Dyneon,客戶的認證活動已轉向其他供應商。其他特殊等級的氟橡膠,包括氫化丁腈橡膠(HNBR)和乙丙橡膠(EPM),將繼續應用於汽車和可再生能源領域。
區域分析
亞太地區預計到2025年將佔總銷售額的45.03%,並預計到2031年將以7.93%的複合年成長率成長。這一成長得益於中國和韓國的汽車供應鏈、日本和台灣的半導體生產以及東南亞國協的醫療設備組裝。繼2025年10月第一期工程投產後,阿朗新科於2026年2月在常州舉行了「特邦」(Therban)氫化丁腈橡膠(HNBR)工廠的開幕典禮。該工廠一期年產能為2500噸,並預留了未來擴建的空間。
在北美,市場主要由半導體製造、航太和製藥等高附加價值應用領域所驅動。亞利桑那州、德克薩斯州和紐約州的新建半導體製造項目支撐了對特殊密封劑的需求。墨西哥在汽車產業的近岸外包作用也促進了對密封劑的需求。該地區高性能彈性體市場的規模不僅受需求本身的影響,也受對高品質產品要求的影響。
在歐洲,汽車和工業機械行業的需求以及不斷上漲的監管合規和認證成本是推動需求的主要因素。瓦克化學股份公司於2026年在捷克共和國卡羅維發利開設了一家特種矽酮生產工廠。在南美洲,巴西的汽車和石油業對特種矽酮的需求旺盛。在中東和非洲,石油化工、天然氣加工和採礦業對特種矽酮的需求也十分旺盛。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 車輛電氣化和熱負荷增加
- 惡劣環境下對密封解決方案的需求
- 半導體和高純度電子元件的市場擴張
- 醫療設備和藥品生產規模擴大
- 新能源系統專用彈性體的認證。
- 市場限制因素
- 特殊原物料價格波動
- 關於氟化合物法規和 PFAS 合規性的不確定性
- 新型彈性體配方認證延誤
- 價值鏈分析
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 丁腈橡膠
- 矽橡膠
- 氟橡膠
- 其他
- 透過使用
- 密封件和墊圈
- 軟管和管子
- 模製零件
- 電線電纜
- 其他
- 按最終用戶行業分類
- 汽車和運輸業
- 工業機械
- 衛生保健
- 建築/施工
- 電氣和電子設備
- 其他
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- 3M
- AGC Inc.
- ARLANXEO
- DAIKIN INDUSTRIES, Ltd.
- Dow
- DuPont
- Exxon Mobil Corporation
- Mitsubishi Chemical Corporation
- Mitsui Chemicals, Inc.
- Momentive
- Solvay
- The Chemours Company
- Trelleborg Group
- Wacker Chemie AG
- ZEON CORPORATION
第7章 市場機會與未來展望
According to Mordor Intelligence, the high performance elastomer market size was valued at USD 18.67 billion in 2025 and is estimated to grow from USD 19.91 billion in 2026 to USD 28.12 billion by 2031, at a CAGR of 7.15% during the forecast period (2026-2031).
Global High Performance Elastomer Market Trends and Insights
Electrification and Higher Thermal Loads in Vehicles
Battery-electric vehicle platforms have changed the thermal and chemical requirements for elastomer seals. High-voltage vehicle systems require insulation and sealing materials that operate in the presence of batteries, motors, and charging components. Battery packs also require gap-filling materials that support heat transfer and performance during thermal cycling. The European Union Battery Regulation introduces material considerations for the end-of-life treatment of battery components. Wacker Chemie AG introduced ELASTOSIL RT 7616 TC and ELASTOSIL RT 7624 TC for battery potting and gap-filling applications, with rheological properties designed to reduce filler sedimentation. The high performance elastomer market is supported as vehicle programs shift toward compounds that combine electrical insulation, thermal management, and durable sealing.
Demand for Extreme Condition Sealing Solutions
Sealing materials are required for applications involving high temperatures, pressure fluctuations, chemical exposure, and long service intervals. Semiconductor equipment, industrial pumps, chemical processing equipment, and vehicle systems operate under varying conditions, requiring suppliers to tailor materials and validation methods accordingly. Conventional rubbers may not be suitable when seals must maintain performance under demanding operating conditions. This trend supports specialty formulations with controlled cleanliness, chemical resistance, and compression-set performance. The high performance elastomer market also requires technical support in addition to material supply, as customers often need guidance on compound selection and qualification. These requirements can make it more difficult for suppliers to replace established materials after approval for critical applications.
Specialty Feedstock Price Volatility
High performance elastomer formulations rely on specialty chemical inputs that standard materials cannot always replace. Nitrile formulations are exposed to acrylonitrile price fluctuations, while fluoroelastomers depend on specialized fluorinated monomers. Supply disruptions can increase compound prices and complicate contract negotiations between suppliers and buyers. These price fluctuations can affect materials already specified in automotive and industrial equipment programs. In price-sensitive applications, higher input costs can delay customer purchasing decisions in the high performance elastomer market. Suppliers with access to feedstock or long-term procurement agreements may maintain supply continuity during disruptions.
Other drivers and restraints analyzed in the detailed report include:
- Semiconductor and High-Purity Electronics Expansion
- Increasing Medical Device and Pharmaceutical Manufacturing
- Fluorochemical Restrictions and PFAS Compliance Uncertainty
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone elastomers accounted for 36.17% of revenue in 2025, representing the largest share of the high performance elastomer market. These materials are used in automotive thermal management systems, medical devices, and high-voltage electrical insulation. Liquid silicone rubber, high-temperature vulcanized silicone, and room-temperature vulcanized silicone serve distinct processing requirements. DuPont introduced Liveo C6-8XX LSR for healthcare devices in February 2026, offering five Shore A hardness options ranging from 30 to 70.
Dow announced targeted specialty silicone investments of USD 100 million in June 2026, including liquid silicone rubber manufacturing lines in Kentucky and China. Fluoroelastomers are projected to grow at a CAGR of 7.78% through 2031, the highest rate among type segments. Semiconductor sales and chemical processing activities support demand for applications in which fluorocarbon performance remains difficult to replace. 3M's 2025 exit from per- and polyfluoroalkyl substances (PFAS) and Dyneon manufacturing shifted customer qualification activity toward alternative suppliers. Other specialty grades, including hydrogenated nitrile-butadiene rubber (HNBR) and ethylene-propylene-monomer (EPM), continue to serve automotive and renewable energy applications.
Complete Report Scope:
- By Type
- Nitrile-Based Elastomers
- Silicone Elastomers
- Fluoroelastomers
- Others
- By Application
- Seals and Gaskets
- Hoses and Tubing
- Molded Parts
- Wires and Cables
- Others
- By End-User Industry
- Automotive and Transportation
- Industrial Machinery
- Healthcare
- Building and Construction
- Electrical and Electronics
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 45.03% of revenue in 2025 and is forecast to grow at a CAGR of 7.93% through 2031. Growth is supported by automotive supply chains in China and South Korea, semiconductor production in Japan and Taiwan, and medical device assembly across ASEAN countries. ARLANXEO inaugurated its Therban Hydrogenated Nitrile Butadiene Rubber (HNBR) plant in Changzhou in February 2026, following the commencement of Phase 1 operations in October 2025. The facility has an annual Phase 1 capacity of 2,500 tons and is designed for future expansion.
North America serves high-value applications in semiconductor fabrication, aerospace, and pharmaceutical manufacturing. New semiconductor fabrication projects in Arizona, Texas, and New York support demand for specialized seals. Mexico's role in automotive nearshoring also supports demand for sealing materials. Premium product requirements, rather than demand alone, influence the size of the high performance elastomer market in the region.
Europe combines automotive and industrial machinery demand with higher regulatory compliance and qualification costs. Wacker Chemie AG opened a specialty silicones production site in Karlovy Vary, Czech Republic, in 2026. South America has demand from Brazil's automotive and petroleum activities. The Middle East and Africa have demand from petrochemical, gas processing, and mining applications.
- 3M
- AGC Inc.
- ARLANXEO
- DAIKIN INDUSTRIES, Ltd.
- Dow
- DuPont
- Exxon Mobil Corporation
- Mitsubishi Chemical Corporation
- Mitsui Chemicals, Inc.
- Momentive
- Solvay
- The Chemours Company
- Trelleborg Group
- Wacker Chemie AG
- ZEON CORPORATION
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrification and Higher Thermal Loads in Vehicles
- 4.2.2 Demand for Extreme-Condition Sealing Solutions
- 4.2.3 Semiconductor and High-Purity Electronics Expansion
- 4.2.4 Increasing Medical Device and Pharmaceutical Manufacturing
- 4.2.5 Application-Specific Elastomer Qualification for New Energy Systems
- 4.3 Market Restraints
- 4.3.1 Specialty Feedstock Price Volatility
- 4.3.2 Fluorochemical Restrictions and PFAS Compliance Uncertainty
- 4.3.3 Qualification Delays for New Elastomer Formulations
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Nitrile-Based Elastomers
- 5.1.2 Silicone Elastomers
- 5.1.3 Fluoroelastomers
- 5.1.4 Others
- 5.2 By Application
- 5.2.1 Seals and Gaskets
- 5.2.2 Hoses and Tubing
- 5.2.3 Molded Parts
- 5.2.4 Wires and Cables
- 5.2.5 Others
- 5.3 By End-User Industry
- 5.3.1 Automotive and Transportation
- 5.3.2 Industrial Machinery
- 5.3.3 Healthcare
- 5.3.4 Building and Construction
- 5.3.5 Electrical and Electronics
- 5.3.6 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 AGC Inc.
- 6.4.3 ARLANXEO
- 6.4.4 DAIKIN INDUSTRIES, Ltd.
- 6.4.5 Dow
- 6.4.6 DuPont
- 6.4.7 Exxon Mobil Corporation
- 6.4.8 Mitsubishi Chemical Corporation
- 6.4.9 Mitsui Chemicals, Inc.
- 6.4.10 Momentive
- 6.4.11 Solvay
- 6.4.12 The Chemours Company
- 6.4.13 Trelleborg Group
- 6.4.14 Wacker Chemie AG
- 6.4.15 ZEON CORPORATION
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

 動態硫化合金市場:全球市場預測,2026-2032年
 歐洲、中東和非洲(EMEA)彈性體市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)汽車內裝TPV材料市場:全球市場預測,2026-2032年
 2026-2034年全球3D列印彈性體市場規模、佔有率、趨勢與成長分析報告
 航太彈性體市場報告:趨勢、預測與競爭分析(至2035年)工業用聚氨酯彈性體市場-2026-2032年全球市場預測3D列印彈性體市場-2026-2032年全球市場預測彈性體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 聚烯彈性體市場:依應用和地區分類彈性體市場:2026-2032年全球市場預測(依彈性體類型、聚合製程、產品形式及應用分類)