


 |
市場調查報告書
商品編碼
2154406
智慧體人工智慧諮詢服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Agentic AI Consulting Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年基於代理的 AI 諮詢服務的市場規模為 28.6 億美元,預計到 2031 年將從 2026 年的 35.5 億美元成長到 102.7 億美元,在預測期(2026-2031 年)內成長到 102.7 億美元,在預測期(2026-2031 年)內的複合年成長率為 23.67%。
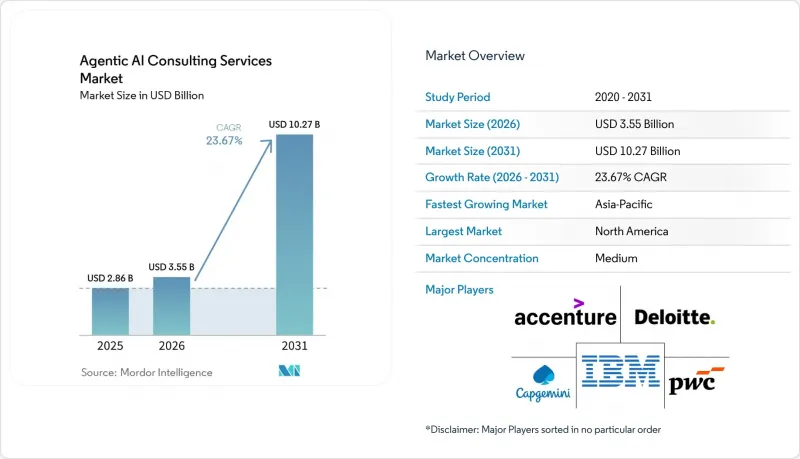
全球基於代理的人工智慧諮詢服務市場趨勢與洞察。
企業對自主工作流程轉型的需求
基於代理的人工智慧諮詢服務市場正受益於企業對自主工作流程的投資,而非僅僅進行一次性演示。企業需要協助明確哪些任務可以自動化,哪些核准流程應由人工執行,以及如何衡量結果。由於工作流程通常涉及財務、營運、服務和合規團隊,因此這種需求貫穿從初始規劃階段到生產支援的整個過程。此外,客戶的興趣正從以諮詢工時轉向與營運成果掛鉤的商業模式。這種轉變有利於那些能夠設定清晰的交貨里程碑並在整個實施過程中保持管理標準的供應商。
多代理企業部署的複雜性日益增加。
基於代理的人工智慧諮詢服務市場面臨的挑戰在於,如何從單一代理過渡到與業務應用程式互動的協作系統。這些系統需要可靠的資料存取、任務路由、記憶體控制、監控工具和異常處理程序。即使目標用例定義明確,舊有系統和資料品質的差異性也可能導致部署延遲。當代理程式支援關鍵決策和操作時,人工審核仍然至關重要。 IBM 和 SAP 於 2026 年擴展了合作夥伴關係,以實現 IBM Consulting Advantage 代理程式和 SAP Joule 代理程式之間的互通性,凸顯了跨平台部署所需的技術協作的重要性。
高度自動化工作流程的投資報酬率 (ROI) 尚不明確
在基於代理的人工智慧諮詢服務市場,如果客戶無法將代理部署與可衡量的營運成果連結起來,他們可能會推遲購買決策。概念驗證(PoC) 或許能夠展現技術能力,但卻無法證明整體業務流程的改善。整合工作、資料修正和管治審查也會延緩投資回報的顯現。因此,財務經理可能更傾向於分階段簽訂、里程碑明確的契約,而不是廣泛的轉型協議。能夠提供檢驗的用例和透明的績效指標的供應商,更有優勢將先導計畫轉化為生產專案。
細分市場分析
2025年,實施和系統整合諮詢將佔基於代理的人工智慧諮詢服務市場的31.53%。此細分市場佔據領先地位,因為企業必須將代理商整合到企業資源規劃 (ERP)、客戶關係管理 (CRM)、服務管理和營運平台中。這些項目需要資料管道、應用程式介面、存取控制和流程測試。由於業務規則和來源系統會發生變化,部署後的工作通常仍需繼續。部署團隊還需要記錄故障回應和升級流程。預計到2031年,代理架構和解決方案設計將以24.13%的複合年成長率成長。這一成長反映了對代理角色、任務路由、記憶體管理、工具存取和人工監督等方面的決策需求。
在企業專案的初期階段,策略和準備的諮詢仍然至關重要。這使客戶能夠在技術工作開始之前,確定用例的優先順序、識別營運風險並建立決策權。數據、雲端和基礎設施的諮詢有助於確保代理商能夠可靠地存取企業資料。這些系統包括資訊搜尋工作流程、資料管治管理和監控工具。基於代理的人工智慧諮詢服務市場還包括代理維運 (AgentOps)、代理評估設計和模型風險管理等新興需求。 2026 年 5 月,IBM 推出了 Context Studio 和 Process Studio,旨在協助客戶將代理商與組織的資料緊密結合,並將營運流程轉化為面向代理商的工作流程。這些功能表明,架構和整合工作必須同步進行。同時具備業務流程知識和技術交付能力的供應商能夠滿足更大比例的業務需求。
到2025年,雲端技術將佔據基於代理的AI諮詢服務市場64.28%的佔有率。雲端服務憑藉其提供的託管模型存取、資料儲存、監控和運算能力,引領著產業發展。諮詢顧問可以專注於配置工作流程和企業整合,而無需建立各個基礎設施層。此外,隨著程式的開發,利用雲端平台可以更方便地更新模型和可觀測性工具。這種方法能夠支援在資料和控制要求明確的用例中更快地部署。預計到2031年,雲端部署將以24.44%的複合年成長率成長。這一趨勢表明,企業正在利用託管服務來減輕生產環境中代理程式的維運負擔。
對於資料居住、安全或稽核要求嚴格的組織而言,本地部署仍然至關重要。金融機構、政府機構和國防相關使用者可能需要對推理、資料處理和決策記錄進行更嚴格的控制。歐盟人工智慧法強化了相關高風險人工智慧應用中文件記錄和監管的必要性。這些情況可能會擴大部署諮詢的範圍和持續時間。Accenture和Google雲端於2026年4月推出了Gemini企業加速計劃,該計劃旨在為自主部署提供支援。這表明自主部署和託管部署模式正在成為不同的服務領域。由於客戶需求因風險狀況和地區而異,這兩種部署方式將持續並存。
區域分析
2025年,北美將佔據基於代理的人工智慧諮詢服務市場38.73%的佔有率。該地區受惠於眾多擁有成熟技術方案的公司,以及與領先顧問公司和平台供應商的便利對接。客戶的工作重點日益集中於將已確定的代理用例從試點階段過渡到生產階段。 2026年4月,Google宣布與Accenture、德勤、麥肯錫和波士頓顧問公司合作,投資7.5億美元,以支援基於合作夥伴的人工智慧開發。這將加強該地區大規模的合作夥伴生態系統的作用。北美的計畫很可能融合平台實施、工作流程重構和管治支援等多個面向。
預計到2031年,亞太地區的複合年成長率將達到24.61%。這一成長主要得益於企業快速採用人工智慧技術以及政府對在地化人工智慧基礎設施的重視。微軟在2025年4月發布的報告顯示,亞太地區53%的高階主管正在使用人工智慧代理來自動化其整個工作流程,74%的高階主管熟悉人工智慧代理。印度和新加坡是諮詢服務的重要早期市場,因為企業和政府機構都在優先考慮基於代理商的營運模式。另一方面,日本則呈現出更謹慎的趨勢,支持人機協同設計的需求。此外,印度的IT服務公司透過與微軟的夥伴關係,擁有廣泛的平台使用者基礎。
在歐洲,德國、英國和法國的需求顯著,尤其是在受監管的產業。歐盟人工智慧法將於2026年8月2日全面實施,屆時將對相關系統提出合規要求。這將為管治諮詢創造機遇,但預計也會延長實施週期。桑坦德銀行在歐洲使用受監管的人工智慧代理商進行支付,是金融服務公司的早期案例。南美洲的人工智慧發展起步小規模,巴西的金融業可望成為自動化服務的潛在切入點。在中東,各國,特別是阿拉伯聯合大公國和沙烏地阿拉伯,正致力於發展國家主導的人工智慧基礎設施和戰略。非洲仍處於起步階段,技能和基礎設施的限制可能會阻礙人工智慧的廣泛應用。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 企業對自主工作流程轉型的需求
- 多代理企業部署的複雜性日益增加。
- 對人工智慧管治和主權人工智慧準備工作的需求日益成長。
- 專業化的基於代理的人工智慧工程和轉型管理人才短缺
- 在受監管行業中擴大基於代理的人工智慧的應用
- 向以結果為導向、積極主動的人工智慧轉型計劃過渡
- 市場限制因素
- 高度自動化工作流程的投資報酬率 (ROI) 尚不明確。
- 代理之間的互通性和評估標準的碎片化
- 計算、推理和代理運行成本不斷上升
- 自主決策缺乏課責制
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 科技趨勢
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 策略和準備方面的諮詢
- 代理架構和解決方案設計
- 提供數據、雲端運算和基礎設施的諮詢服務。
- 實施和系統整合諮詢
- 管治、風險和合規 (GRC) 諮詢
- 變革管理與員工賦權
- AgentOps 最佳化和託管服務
- 其他服務類型
- 不同的發展
- 雲端採用
- 本地部署
- 按組織規模
- 大公司
- 小型企業
- 最終用戶
- BFSI
- 醫療保健和生命科學
- 資訊科技/通訊
- 零售與電子商務
- 政府/公共部門
- 車
- 能源公用事業
- 物流/運輸
- 媒體與娛樂
- 教育
- 房地產
- 其他最終用戶
- 透過使用
- 預測分析與決策支持
- 變革客戶經驗與客服中心
- RPA整合與流程協作
- 軟體開發與測試
- 網路安全保全行動
- 財務和會計運營
- 供應鍊和採購
- 人力資源與勞動管理
- 監理合規與風險管理
- 其他用途
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accenture plc
- International Business Machines Corporation
- Deloitte Touche Tohmatsu Limited
- PricewaterhouseCoopers International Limited
- Ernst & Young Global Limited
- McKinsey & Company, Inc.
- Boston Consulting Group, Inc.
- Bain & Company, Inc.
- Capgemini SE
- KPMG International Cooperative
- Tata Consultancy Services Limited
- Cognizant Technology Solutions Corporation
- Wipro Limited
- HCL Technologies Limited
- NTT DATA Corporation
- Avanade Inc.
- ServiceNow, Inc.
- Salesforce, Inc.
- UiPath, Inc.
- EPAM Systems, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the agentic AI consulting services market size was valued at USD 2.86 billion in 2025 and estimated to grow from USD 3.55 billion in 2026 to reach USD 10.27 billion by 2031, at a CAGR of 23.67% during the forecast period (2026-2031).
Global Agentic AI Consulting Services Market Trends and Insights
Enterprise Demand for Autonomous Workflow Transformation
The Agentic AI Consulting Services Market benefits when enterprises commit funding to autonomous workflows rather than isolated demonstrations. Organizations need help defining which activities can be automated, what approvals remain with people, and how results should be measured. This need extends from early planning to production support, as workflows often span finance, operations, service, and compliance teams. Client interest is also shifting toward commercial models tied to operating outcomes rather than consultant time. That shift favors providers that can set clear delivery milestones and maintain control standards throughout deployment.
Rising Complexity of Multi-Agent Enterprise Deployments
The Agentic AI Consulting Services Market is supported by the difficulty of moving from a single agent to coordinated systems that interact with business applications. These systems need reliable data access, task routing, memory controls, observation tools, and procedures for exceptions. Legacy systems and uneven data quality can slow implementation even when the target use case is well defined. Human review remains important when an agent supports material decisions or actions. IBM and SAP expanded their collaboration in 2026 to enable interactions between IBM Consulting Advantage agents and SAP Joule agents, highlighting the technical coordination required for cross-platform deployments.
Unclear Return on Investment for High-Autonomy Workflows
The Agentic AI Consulting Services Market may see slower buying decisions when clients cannot connect agent deployments to measurable operational outcomes. A proof of concept may show technical capability without proving that it improves a full business process. Integration work, data remediation, and governance review can also delay the point at which returns become visible. Finance leaders may therefore prefer phased engagements with defined milestones instead of broad transformation contracts. Providers that bring validated use cases and transparent performance measures are better placed to convert pilots into production programs.
Other drivers and restraints analyzed in the detailed report include:
- Growing Need for AI Governance and Sovereign AI Readiness
- Expansion of Agentic AI Use Cases Across Regulated Industries
- Fragmented Agent Interoperability and Evaluation Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Implementation and systems integration consulting held 31.53% of the agentic AI consulting services market in 2025. The segment leads because organizations must connect agents to enterprise resource planning, customer relationship management, service management, and operational platforms. These projects require data pipelines, application interfaces, access controls, and process testing. The work often continues after launch because business rules and source systems change. Implementation teams also need to document failure paths and escalation procedures. Agent architecture and solution design are projected to grow at a 24.13% CAGR through 2031. Its growth reflects demand for decisions on agent roles, task routing, memory management, tool access, and human oversight.
Strategy and readiness consulting remain important at the start of an enterprise program. It helps clients prioritize use cases, identify operating risks, and set decision rights before technical work begins. Data, cloud, and infrastructure consulting support the systems that give agents reliable access to company information. Those systems can include retrieval workflows, data governance controls, and monitoring tools. The Agentic AI Consulting Services Market also includes emerging needs such as AgentOps, agent evaluation design, and model risk management. IBM introduced Context Studio and Process Studio in May 2026 to help clients ground agents in organizational data and turn operating procedures into agent-ready workflows. These capabilities show why architecture and integration work must proceed together. Providers that combine business process knowledge with technical delivery can address a larger share of the work.
Cloud deployment accounted for 64.28% of the agentic AI consulting services market in 2025. It leads because cloud services provide managed model access, data storage, monitoring, and computing capacity. Consultants can focus on workflow configuration and enterprise integration instead of building each infrastructure layer. Cloud platforms also make it easier to update models and observability tools as a program develops. This approach can support faster deployment for use cases with clear data and control requirements. Cloud deployment is projected to grow at a 24.44% CAGR through 2031. The pattern shows that enterprises are using managed services to reduce operational burden in production agent programs.
On-premises deployment remains relevant for organizations with strict data-residency, security, or audit requirements. Financial institutions, government agencies, and defense-related users may need greater control over inference, data handling, and decision records. The EU AI Act reinforces the need for documentation and oversight in relevant high-risk AI applications. These conditions can increase the scope and duration of deployment consulting. Accenture and Google Cloud launched the Gemini Enterprise Acceleration Program in April 2026 with sovereign-deployment-ready agents. This indicates that sovereign and controlled deployment models are becoming a defined service area. The two deployment approaches will continue to coexist because client requirements differ by risk profile and geography.
Complete Report Scope:
- By Service Type
- Strategy and Readiness Consulting
- Agent Architecture and Solution Design
- Data, Cloud, and Infrastructure Consulting
- Implementation and Systems Integration Consulting
- Governance, Risk, and Compliance Consulting
- Change Management and Workforce Enablement
- AgentOps Optimization and Managed Services
- Other Service Type
- By Deployment
- Cloud Deployment
- On-Premises Deployment
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By End User
- BFSI
- Healthcare and Life Sciences
- Information Technology and Telecommunications
- Retail and E-Commerce
- Government and Public Sector
- Automotive
- Energy and Utilities
- Logistics and Transportation
- Media and Entertainment
- Education
- Real Estate
- Other End Users
- By Application
- Predictive Analytics and Decision Support
- Customer Experience and Contact Center Transformation
- RPA Integration and Process Orchestration
- Software Development and Testing
- Cybersecurity Operations
- Finance and Accounting Operations
- Supply Chain and Procurement
- Human Resources and Workforce Operations
- Regulatory Compliance and Risk Management
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 38.73% of the agentic AI consulting services market in 2025. The region benefits from a large base of enterprises with mature technology programs and access to major consulting and platform providers. Client work is increasingly focused on moving defined agent use cases from trials into production operations. Google announced a USD 750 million commitment in April 2026 to support partner agentic AI development with Accenture, Deloitte, McKinsey, and BCG. This strengthens the role of large partner ecosystems in the region. North American engagements are likely to combine platform implementation with workflow redesign and governance support.
Asia-Pacific is projected to grow at a 24.61% CAGR through 2031. The region combines rapid enterprise adoption with government interest in locally controlled AI infrastructure. Microsoft reported in April 2025 that 53% of Asia-Pacific leaders were using agents to automate entire workstreams and that 74% were highly familiar with AI agents. India and Singapore are important early markets for consulting work as enterprises and public institutions prioritize agent-enabled operations. Japan shows a more cautious pattern, supporting demand for human-in-the-loop designs. India-based IT services firms also have a broad platform deployment base through their Microsoft partnerships.
Europe has significant demand from Germany, the United Kingdom, and France, particularly in regulated sectors. The EU AI Act is fully applicable as of August 2, 2026, and introduces compliance requirements for relevant systems. This creates opportunities in governance consulting while also lengthening implementation timelines. Santander's regulated AI-agent payment in Europe provides an early operational example for financial services firms. South America is developing from a smaller base, with Brazil's financial sector offering a potential entry point for automation services. The Middle East is focused on sovereign AI infrastructure and strategy work, especially in the United Arab Emirates and Saudi Arabia. Africa remains at an earlier stage because limitations in skills and infrastructure can delay wider adoption.
List of Companies Covered in this Report:
- Accenture plc
- International Business Machines Corporation
- Deloitte Touche Tohmatsu Limited
- PricewaterhouseCoopers International Limited
- Ernst & Young Global Limited
- McKinsey & Company, Inc.
- Boston Consulting Group, Inc.
- Bain & Company, Inc.
- Capgemini SE
- KPMG International Cooperative
- Tata Consultancy Services Limited
- Cognizant Technology Solutions Corporation
- Wipro Limited
- HCL Technologies Limited
- NTT DATA Corporation
- Avanade Inc.
- ServiceNow, Inc.
- Salesforce, Inc.
- UiPath, Inc.
- EPAM Systems, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Enterprise Demand for Autonomous Workflow Transformation
- 4.2.2 Rising Complexity of Multi-Agent Enterprise Deployments
- 4.2.3 Growing Need for AI Governance and Sovereign AI Readiness
- 4.2.4 Shortage of Specialized Agentic AI Engineering and Change-Management Talent
- 4.2.5 Expansion of Agentic AI Use Cases Across Regulated Industries
- 4.2.6 Shift Toward Outcome-Based Agentic AI Transformation Programs
- 4.3 Market Restraints
- 4.3.1 Unclear Return on Investment for High-Autonomy Workflows
- 4.3.2 Fragmented Agent Interoperability and Evaluation Standards
- 4.3.3 Rising Compute, Inference, and AgentOps Costs
- 4.3.4 Accountability Gaps in Autonomous Decision-Making
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Strategy and Readiness Consulting
- 5.1.2 Agent Architecture and Solution Design
- 5.1.3 Data, Cloud, and Infrastructure Consulting
- 5.1.4 Implementation and Systems Integration Consulting
- 5.1.5 Governance, Risk, and Compliance Consulting
- 5.1.6 Change Management and Workforce Enablement
- 5.1.7 AgentOps Optimization and Managed Services
- 5.1.8 Other Service Type
- 5.2 By Deployment
- 5.2.1 Cloud Deployment
- 5.2.2 On-Premises Deployment
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-Sized Enterprises
- 5.4 By End User
- 5.4.1 BFSI
- 5.4.2 Healthcare and Life Sciences
- 5.4.3 Information Technology and Telecommunications
- 5.4.4 Retail and E-Commerce
- 5.4.5 Government and Public Sector
- 5.4.6 Automotive
- 5.4.7 Energy and Utilities
- 5.4.8 Logistics and Transportation
- 5.4.9 Media and Entertainment
- 5.4.10 Education
- 5.4.11 Real Estate
- 5.4.12 Other End Users
- 5.5 By Application
- 5.5.1 Predictive Analytics and Decision Support
- 5.5.2 Customer Experience and Contact Center Transformation
- 5.5.3 RPA Integration and Process Orchestration
- 5.5.4 Software Development and Testing
- 5.5.5 Cybersecurity Operations
- 5.5.6 Finance and Accounting Operations
- 5.5.7 Supply Chain and Procurement
- 5.5.8 Human Resources and Workforce Operations
- 5.5.9 Regulatory Compliance and Risk Management
- 5.5.10 Other Applications
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Qatar
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Nigeria
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 International Business Machines Corporation
- 6.4.3 Deloitte Touche Tohmatsu Limited
- 6.4.4 PricewaterhouseCoopers International Limited
- 6.4.5 Ernst & Young Global Limited
- 6.4.6 McKinsey & Company, Inc.
- 6.4.7 Boston Consulting Group, Inc.
- 6.4.8 Bain & Company, Inc.
- 6.4.9 Capgemini SE
- 6.4.10 KPMG International Cooperative
- 6.4.11 Tata Consultancy Services Limited
- 6.4.12 Cognizant Technology Solutions Corporation
- 6.4.13 Wipro Limited
- 6.4.14 HCL Technologies Limited
- 6.4.15 NTT DATA Corporation
- 6.4.16 Avanade Inc.
- 6.4.17 ServiceNow, Inc.
- 6.4.18 Salesforce, Inc.
- 6.4.19 UiPath, Inc.
- 6.4.20 EPAM Systems, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2026年全球基於代理的人工智慧工具市場報告
 學習支援技術市場規模、佔有率和趨勢分析報告:按產品類型、應用、最終用途、地區和細分市場預測(2026-2033 年)
 智慧體人工智慧管理服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 全球基於代理的人工智慧市場(至 2033 年):按產品類別(開發平台、編配和運行時平台、流程自動化平台、現成的基於代理的人工智慧應用)和應用(客戶服務與支援、營收營運、IT 營運、商業智慧與分析)分類美國基於代理的AI安全市場規模、佔有率和趨勢分析報告:按組件、部署模式、組織規模、最終用途、地區和細分市場預測(2026-2033年)美國基於代理的人工智慧市場規模、佔有率和趨勢分析報告:按組件、應用、最終用途和細分市場預測(2026-2033 年)基於代理的人工智慧市場規模、佔有率和趨勢分析報告:按組件、應用、最終用途、地區和細分市場分類(2026-2033 年)基於代理的人工智慧安全市場規模、佔有率和趨勢分析報告:按組件、部署模式、組織規模、最終用途、地區和細分市場預測(2026-2033 年)B2B自主商務軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 全球代理商務市場:按產品、交易類型、通路、應用程式、最終用戶和地區分類-市場規模、產業動態、機會分析和預測(2026-2035 年)