


 |
市場調查報告書
商品編碼
2154272
菲律賓履帶式土木工程機具:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Philippines Crawler Earthmoving Machines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
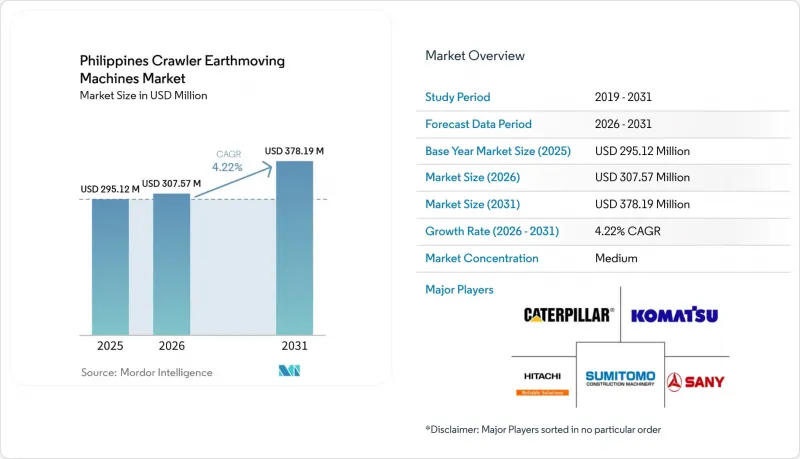
據 Mordor Intelligence 稱,菲律賓履帶式土木機械市場在 2025 年的價值為 2.9512 億美元,預計到 2026 年將達到 3.0757 億美元,到 2031 年將達到 3.7819 億美元,預計 2026 年至 2031 年將達到 3.7819 億美元,預計 2026 年至 2031 年的複合年成長率為 222%。
菲律賓履帶式土木機械市場趨勢與洞察
政府主導的「建設更美好、更多(BBM)」基礎建設計劃
數十座大型橋樑、高速公路和防洪設施的建設推動了履帶式土木工程機具的持續運作,尤其是在地基開挖和路堤施工方面。儘管多邊融資緩解了國內預算削減的影響,但資金支付的延遲可能導致部分完工的工地上的機械閒置,從而降低設備運轉率。由於承包商在等待開工通知里程碑期間更傾向於簽訂成本柔軟性的契約,租賃公司從中受益。持續的都市區化進程保證了農村地區道路改善項目的按計劃進行,即使大型企劃停滯不前,也能確保對設備的長期穩定需求。
棉蘭老島大型採礦和採石計畫的復興
蘇里高北省大規模銅金礦專案的運作,由於露天採礦週期嚴苛,導致履帶式挖土機的更換需求持續多年。惡劣的紅土地質加速了底盤磨損,迫使業主縮短維護週期。儘管全球鎳價的不確定性加劇了採購的謹慎,但強制性維修保證要求營運商保持高效的設備生產。與礦業物流相關的當地道路維修進一步推動了區域建築需求,從而產生了對中型挖土機的次要需求。
高初始資本投入與信貸緊縮
中檔挖掘機動輒六位數的價格,加上更嚴格的貸款價值比(LTV),迫使許多承包商依賴租賃。儘管貨幣寬鬆政策降低了名目利率,但抵押品要求依然很高,這對小規模的建築公司構成了挑戰。租賃提供了表外融資方案,但實際利率仍會進一步擠壓專案本已微薄的利潤空間。在流動性狀況改善之前,資產最小化的商業模式仍將佔據主導地位,經銷商的收入來源也將轉向零件和服務。
細分市場分析
預計2025年,履帶式挖土機將佔據菲律賓履帶式土木工程機具市場55.12%的佔有率。這反映了它們無需頻繁更換附件即可完成挖掘、平整和拆除作業的能力。小型履帶裝載機和滑移裝載機預計將以4.93%的複合年成長率成長。這是因為面積小、機動性高的機械在空間有限的都市區工地中具有優勢。建築公司將挖土機視為一種多功能的「核心」資產,這使他們能夠最大限度地減少擁有的設備數量。與快換接頭的兼容性減少了停機時間,並確保了可預測的日常運轉率。因此,原始設備製造商(OEM)正在優先考慮挖土機的升級,包括引入數位化監控和低排放氣體選項。
隨著城市改造將大型重型機械從擁擠的商業區移除,對小型履帶裝載機的需求日益成長。租賃公司擴大儲備這類裝載機,以確保在空間有限、無法部署全尺寸履帶式機械的短期專案中獲得用工。同時,挖土機在橋樑基礎工程和明挖回填排水工程中仍然佔據主導地位,因為其他履帶式機械無法提供與之匹敵的作業範圍和穩定性。經銷商在銷售新挖土機時,會將破碎錘和抓斗等附件作為套裝的一部分進行銷售,以強調挖土機平台的通用性。這兩個領域表明,菲律賓的採購決策不僅受產量驅動,也受柔軟性。
預計到2025年,在菲律賓履帶式土木工程機具市場,內燃機履帶式機械仍將佔據96.91%的市場佔有率,這得益於覆蓋全國的柴油燃料供應網路和機械師的專業技術。隨著建築公司在即將實施的歐5/V排放標準前試用低排放氣體替代方案,電動和混合模式預計將以22.02%的複合年成長率快速成長。由於即使在偏遠工地也能找到加油設施,車隊管理人員仍然傾向於選擇柴油機械。然而,混合動力系統因其在頻繁啟動停止的作業循環中能顯著降低燃料成本,正吸引著注重成本的競標的目光。法規的明確化降低了顆粒物排放限值的合規不確定性,進一步促進了混合動力機械的普及。
經銷商服務團隊正在加強對混合動力汽車維修服務需求的培訓投入,以應對混合動力汽車維修需求的逐步成長。融資合作夥伴也在製定租賃方案,將混合動力汽車的高昂成本分攤到更長的合約期間。在需要全天候運轉、運作損失嚴重的項目中,柴油車仍然是主流選擇。然而,早期採用混合動力汽車的公司可以在優先考慮環保標準的政府競標中獲得聲譽優勢。隨著時間的推移,這些軟性優勢可能會逐漸削弱柴油車長期以來的主導地位,儘管柴油車在物流方面具有優勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府支持的「建設更美好、更多(BBM)」基礎建設計劃
- 棉蘭老島大規模採礦和採石計畫的復興
- 加速更換老舊履帶式車輛,以提高安全性和效率。
- 鼓勵電氣化和第五階段排放氣體法規的獎勵
- 透過數位孿生和遠端資訊處理降低營運成本
- 拆除和循環拆除工程激增。
- 市場限制因素
- 大額初始資本投資與信貸緊縮
- 原料和零件供應的波動
- 重量超過20噸的履帶式車輛缺乏快速充電基礎設施
- 柴油發電機組中與環境、社會及治理(ESG)相關的最終用途成本
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依設備類型
- 履帶式挖土機
- 履帶式推土機
- 履帶式裝載機
- 履帶式起重機和舖管機
- 小型履帶式裝載機和滑移式裝載機
- 其他(挖溝機、鑽孔機等)
- 透過推進力
- 內燃機(ICE)
- 電動車和混合動力汽車
- 按引擎輸出
- 不足100馬力
- 100~200 HP
- 201~400 HP
- 400馬力或以上
- 透過使用
- 建造
- 採礦和採石
- 農業和林業
- 其他
- 透過分銷管道
- 直接OEM銷售
- 授權零售商
- 租賃公司
第6章 競爭情勢
- 市場集中度
- 策略舉措和夥伴關係
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery Co., Ltd.
- Volvo Construction Equipment AB
- Liebherr-International AG
- Sumitomo Construction Machinery
- Kobelco Construction Machinery
- SANY Group
- XCMG Group
- HD Hyundai Construction Equipment
- CNH Industrial-CASE CE
第7章 市場機會與未來展望
According to Mordor Intelligence, the Philippines crawler earthmoving machines market size was valued at USD 295.12 million in 2025 and is expected to reach USD 307.57 million in 2026 and USD 378.19 million by 2031, registering a 4.22% CAGR between 2026 and 2031.
Philippines Crawler Earthmoving Machines Market Trends and Insights
Government-backed Build Better More (BBM) Infrastructure Pipeline
Dozens of flagship bridges, expressways, and flood-control assets drive continuous crawler deployment cycles, especially around foundation excavation and embankment works. Multilateral financing cushions domestic budget cuts, but slower disbursement can leave machines idle at partially completed sites, reducing fleet utilization. Rental firms benefit because contractors prefer cost-flexible agreements while awaiting notice-to-proceed milestones. Steady urban migration ensures that secondary-city road upgrades remain on the docket, cementing long-run equipment demand even if mega-projects stagger.
Revival of Large-Scale Mining and Quarrying Projects in Mindanao
The commissioning of a major copper-gold project in Surigao del Norte opened a multi-year crawler-replacement pipeline tied to demanding open-pit cycles. Harsh laterite conditions accelerate undercarriage wear, compelling owners to budget for shorter rebuild intervals. Uncertainties around global nickel pricing heighten procurement caution, yet mandated rehabilitation bonds bind operators to maintaining productive fleets. Provincial road upgrades linked to mine logistics further lift localized construction demand, creating a secondary pull for mid-range excavators.
High Upfront CAPEX and Tightening Credit
6-figure price tags for mid-range excavators collide with stricter loan-to-value ratios, forcing many contractors to turn to rentals. Monetary easing trims headline interest rates, but collateral requirements stay high, challenging small builders. Leasing provides an off-balance-sheet option, though effective rates still erode thin project margins. Until liquidity conditions improve, asset-light operating models continue to gain ground, reshaping dealer revenue toward parts and service.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Replacement of Aging Crawler Fleets for Safety and Efficiency
- Electrification Incentives and Stage V Emission Mandates
- Raw-Material and Component Supply Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crawler excavators accounted for 55.12% of the Philippines crawler earthmoving machine market share in 2025, reflecting their ability to handle digging, grading, and demolition without frequent tool changes. Compact tracked loaders and skid-steers are projected to post the fastest 4.93% CAGR because tight urban job sites reward machines with small footprints and high maneuverability. Contractors value excavators as multipurpose "anchor" assets that keep fleet sizes lean. Their compatibility with quick-attach couplers reduces downtime, resulting in predictable daily utilization. OEMs therefore prioritize excavator upgrades when introducing digital monitoring or low-emission options.
Demand for compact tracked loaders rises when redevelopment displaces large equipment from congested business districts. Rental firms increasingly stock these loaders to court short-term projects that lack room for full-sized crawlers. Meanwhile, excavators maintain dominance in bridge foundations and open-cut drainage because no other crawler variant offers comparable reach and stability. Dealers bundle attachments such as breakers and grapples with new excavator purchases to underscore the platform's versatility. Together, the two segments illustrate how flexibility, rather than raw power, shapes procurement choices in the Philippines.
Internal-combustion crawlers retained a commanding 96.91% market share in the Philippines crawler earthmoving machines market in 2025, supported by the nationwide diesel supply chain and mechanics' familiarity. Electric and hybrid models are anticipated to register a rapid 22.02% CAGR as contractors test lower-emission alternatives ahead of the incoming Euro 5/V rules. Fleet managers continue to favor diesel because refueling infrastructure is available even at remote job sites. However, hybrid drivetrains deliver tangible fuel savings during stop-and-go cycles, attracting interest among cost-sensitive bidders. Regulatory clarity gives hybrids an extra push by reducing compliance uncertainty around particulate limits.
Dealer service teams invest in high-voltage training to prepare for a gradual rise in hybrid maintenance calls. Financing partners also craft leasing packages that spread the premium on hybrid units over longer contracts. Diesel platforms remain standard on projects with round-the-clock duty cycles where downtime penalties are steep. Even so, early adopters of hybrids gain reputational benefits in government tenders that score highly on environmental criteria. Over time, those soft advantages may erode diesel's historic lock-in despite its logistical edge.
Complete Report Scope:
- By Equipment Type
- Crawler Excavators
- Crawler Bulldozers
- Crawler Loaders
- Crawler Cranes and Pipe-layers
- Compact Tracked Loaders and Skid-steers
- Others (Trencher, Drill Rig, etc.)
- By Propulsion
- Internal Combustion Engine (ICE)
- Electric and Hybrid
- By Engine Power Output
- Below 100 HP
- 100 to 200 HP
- 201 to 400 HP
- Above 400 HP
- By Application
- Construction
- Mining and Quarrying
- Agriculture and Forestry
- Others
- By Distribution Channel
- Direct OEM Sales
- Authorized Dealers
- Rental and Leasing Firms
List of Companies Covered in this Report:
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery Co., Ltd.
- Volvo Construction Equipment AB
- Liebherr-International AG
- Sumitomo Construction Machinery
- Kobelco Construction Machinery
- SANY Group
- XCMG Group
- HD Hyundai Construction Equipment
- CNH Industrial - CASE CE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-Backed Build Better More (BBM) Infrastructure Pipeline
- 4.2.2 Revival of Large-Scale Mining and Quarrying Projects in Mindanao
- 4.2.3 Accelerated Replacement of Aging Crawler Fleets for Safety and Efficiency
- 4.2.4 Electrification Incentives and Stage V Emission Mandates
- 4.2.5 Digital Twins and Telematics-Driven OPEX Savings
- 4.2.6 Surge in Deconstruction and Circular-Demolition Projects
- 4.3 Market Restraints
- 4.3.1 High Upfront CAPEX and Tightening Credit
- 4.3.2 Raw-Material and Component Supply Volatility
- 4.3.3 Scarcity of Fast-Charging Infrastructure for Above 20-T Crawlers
- 4.3.4 ESG-Linked Cost of Ownership for Diesel Units
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) & Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Crawler Excavators
- 5.1.2 Crawler Bulldozers
- 5.1.3 Crawler Loaders
- 5.1.4 Crawler Cranes and Pipe-layers
- 5.1.5 Compact Tracked Loaders and Skid-steers
- 5.1.6 Others (Trencher, Drill Rig, etc.)
- 5.2 By Propulsion
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Electric and Hybrid
- 5.3 By Engine Power Output
- 5.3.1 Below 100 HP
- 5.3.2 100 to 200 HP
- 5.3.3 201 to 400 HP
- 5.3.4 Above 400 HP
- 5.4 By Application
- 5.4.1 Construction
- 5.4.2 Mining and Quarrying
- 5.4.3 Agriculture and Forestry
- 5.4.4 Others
- 5.5 By Distribution Channel
- 5.5.1 Direct OEM Sales
- 5.5.2 Authorized Dealers
- 5.5.3 Rental and Leasing Firms
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves & Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Hitachi Construction Machinery Co., Ltd.
- 6.4.4 Volvo Construction Equipment AB
- 6.4.5 Liebherr-International AG
- 6.4.6 Sumitomo Construction Machinery
- 6.4.7 Kobelco Construction Machinery
- 6.4.8 SANY Group
- 6.4.9 XCMG Group
- 6.4.10 HD Hyundai Construction Equipment
- 6.4.11 CNH Industrial - CASE CE
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 搭乘用式旋轉耙草機市場:全球市場預測,2026-2032年拖曳式旋轉耙草機市場:全球市場預測,2026-2032年鑿式耕耘機市場:全球市場預測,2026-2032年乾草和飼料機械市場:全球市場預測,2026-2032年乾肥料儲存設備市場:全球市場預測,2026-2032年
 美國履帶式土木工程機具:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印尼履帶式土木工程機具:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)軟性室內筒倉市場:依材料、容量、配置、安裝類型和最終用途產業分類-全球預測,2026-2032年單螺旋式糧食運輸車市場按容量範圍、最終用戶、糧食類型和分銷管道分類,全球預測(2026-2032年)糧食螺旋輸送車市場按產品類型、動力來源、最終用途和銷售管道分類-2026-2032年全球預測