


 |
市場調查報告書
商品編碼
2154269
美國履帶式土木工程機具:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)US Crawler Earthmoving Machines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
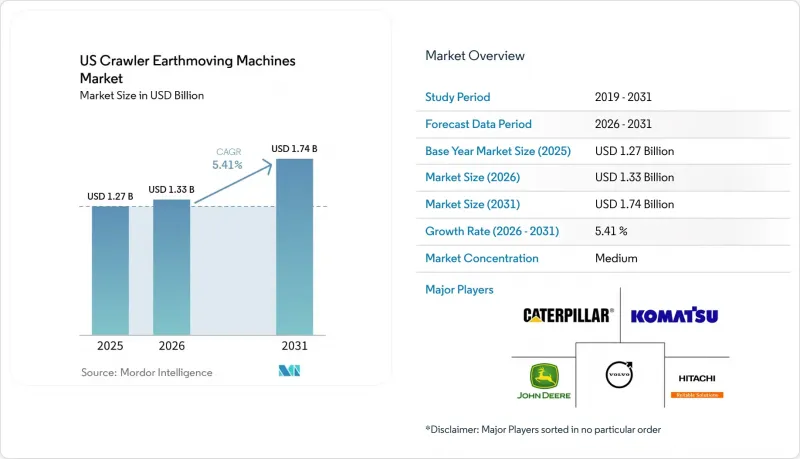
根據 Mordor Intelligence 的數據顯示,2025 年美國履帶式土木機械市場價值為 12.7 億美元,預計 2026 年將達到 13.3 億美元。預計在預測期(2026-2031 年)內,該市場將以 5.41% 的複合年成長率成長,到 2031 年將達到 17.4 億美元。
美國履帶式土木機械市場趨勢與洞察
聯邦政府基礎建設資金激增(IIJA,IRA)
聯邦政府的撥款制度確保了公路建設的年度巨額投資。然而,截至2026年初,已批准的撥款中仍有相當一部分尚未使用。這種情況不僅為總承包商提供了穩健的多年專案前景,也使美國履帶式土木機械市場備受關注。為了補充這項資金基礎,「BUILD」和「RAISE」津貼計畫正在為位於地方城市的多模態提供資金。這項措施正在擴大小型挖土機和裝載機的市場。同時,支出義務週期的延遲導致機械訂單集中在有限的時間內。這一趨勢不僅加劇了季度出貨量的波動,也持續推高了需求,租賃公司正為此做好準備。此外,公共部門的負責人越來越傾向於租賃而非直接購買。這種策略避免了市政資產負債表上的資產折舊免稅額負擔,從而促進了租賃方式的普及。對此,原始設備製造商正在策略性地將庫存部署在運輸部(DOT) 主要轄區附近,以確保能夠可靠地滿足最後一刻的訂單。
人手不足正在推動施工機械租賃的普及。
預計到下一個十年末,建築業勞動力將大幅減少,這將使承包商難以找到熟練的操作人員(BLS.GOV)。為了彌補這一技能缺口,租賃公司目前提供將操作人員培訓與遠端資訊處理儀錶板結合的打包服務,從而簡化機器操作和合規流程。利率上升使得信用度中等的申請人租賃成本越來越高,導致租賃而非購買的趨勢愈發明顯。這種轉變在無法取得自有融資管道的中小型企業中尤其顯著。有鑑於這些趨勢,美國租賃協會(ARA)預測,未來幾年租賃使用率將達到歷史新高,與該通路在預測期內的穩定成長軌跡相符。
2023年起,資本融資利率將大幅上升。
到了2023年中期,聯準會大幅提高政策利率,實際上使借貸成本比幾年前加倍。這一成長顯著增加了履帶式挖土機等昂貴設備的每月租賃費用。信用合格不高的中小型承包商如今面臨更高的租賃報價,迫使他們要么選擇短期租賃,要么推遲設備升級。設備租賃與金融協會(ELFA)報告稱,2025年上半年新契約數量大幅下降,也反映了這一趨勢。同時,原始設備製造商(OEM)針對緊湊型車型推出了0%利率促銷活動,並將持續到2025年下半年。雖然這提振了銷量,但也給經銷商的利潤率帶來了壓力,並引發了人們對利率補貼結束後長期永續性的擔憂。
細分市場分析
履帶式挖土機憑藉其在溝槽挖掘、大規模開挖和拆除作業方面的多功能性,在2025年佔據了美國履帶式土木機械市場67.73%的銷售額。同時,小型履帶式裝載機預計在2026年至2031年間將以6.43%的複合年成長率成長。這反映了市場結構向填充式住宅和城市更新的轉變,在這些項目中,面積小、對草坪友好的底盤更受歡迎。
重型推土機領域車輛更新換代造成的市場需求缺口,帶動了挖掘機用平地控制附件銷量的成長,而原始設備製造商(OEM)正透過其專有的3D機器控制軟體,抓住這一提升銷售機會獲利。此外,與BEAD專案相關的通訊溝槽工程也推動了「其他」類別的成長,其中,424.5億美元的農村寬頻部署專案帶動了對專用機械和附件的需求增加。
儘管預計到2025年內燃機仍將保持83.31%的市場佔有率,但電動和混合模式預計到2031年將以6.45%的複合年成長率成長,穩步擴大其在美國履帶式土木工程機具市場的佔有率。沃爾沃的五款混合動力工程機械產品線可節省20%的燃油,而日本小松公司的再生式迴轉機構可將生產率提高15%,這使得混合動力機械儘管初始成本較高,但從運營成本的角度來看更具優勢。加州將於2024年生效的零排放採購法規正在加速沿海地區的普及,而內陸各州則在等待更完善的充電網路建成後再全面推進車輛電氣化。
在採石和長距離土方工程領域,柴油引擎憑藉其卓越的能量密度和便捷的加油方式仍然佔據主導地位,Tier 4車型比Tier 3車型燃油效率提高了3%至6%。然而,電池組的模組化和電芯成本的下降正在以比預期更快的速度縮小經濟差距。這一趨勢在6噸以下的小型挖土機領域尤其明顯,因為這類挖土機的每日運作時間很少超過8小時。隨著混合動力汽車的日益普及,原始設備製造商(OEM)可以透過開發最佳化功率分配演算法和電池健康監測的軟體來獲得持續的收入來源,從而增強整個美國履帶式土木工程機具市場的售後服務客戶留存率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 聯邦政府基礎建設資金激增(IIJA,IRA)
- 人手不足正在推動設備租賃的普及。
- 電動和混合動力挖土機的興起
- 加速美國二線城市的都市更新項目
- 現場管理數位化和遠端資訊處理整合
- 減少野火的獎勵(美國林務局)
- 市場限制因素
- 2023年起,設備融資利率將大幅上升。
- 鋼材價格波動正在影響OEM廠商的利潤率。
- OEM廠商遵守嚴格的Tier 4排放氣體法規的成本。
- 液壓元件供應鏈中的脆弱性
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依設備類型
- 履帶式挖土機
- 履帶式推土機
- 履帶式裝載機
- 履帶式起重機和舖管機
- 小型履帶式裝載機和滑移式裝載機
- 其他(挖溝機、鑽孔機等)
- 透過推進力
- 內燃機(ICE)
- 電動車和混合動力汽車
- 按引擎輸出
- 不足100馬力
- 100~200 HP
- 201~400 HP
- 400馬力或以上
- 透過使用
- 建造
- 採礦和採石
- 農業和林業
- 其他
- 透過分銷管道
- 直接OEM銷售
- 授權零售商
- 租賃公司
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- Komatsu Ltd.
- John Deere
- Volvo CE
- Hitachi Construction Machinery
- Doosan Bobcat Inc.
- SANY America
- Kobelco USA
- CASE Construction Equipment(CNH Industrial)
- Takeuchi US
- Kubota Tractor Corp.
- JCB North America
- LiuGong North America
- Hyundai CE Americas
- Yanmar CE
- Liebherr Corporation
- Wacker Neuson
- XCMG North America
- Sunward USA
- Mecalac North America
第7章 市場機會與未來展望
According to Mordor Intelligence, the US crawler earthmoving machines market size was valued at USD 1.27 billion in 2025, is estimated at USD 1.33 billion in 2026, and is projected to reach USD 1.74 billion by 2031, at a CAGR of 5.41% during the forecast period (2026-2031).
US Crawler Earthmoving Machines Market Trends and Insights
Boom in Federal Infrastructure Funding (IIJA, IRA)
Federal formula allocations are channeling significant annual investments into highway spending. However, as of early 2026, a substantial portion of this total authorization remains untouched. This scenario not only locks in multi-year visibility for prime contractors but also casts a spotlight on the US crawler earthmoving machine market. Complementing this financial foundation, the BUILD and RAISE grant schemes are directing funds into multimodal hubs situated in secondary cities. This initiative broadens the market for compact excavators and loaders. Meanwhile, delayed obligation cycles are squeezing machine orders into tight timeframes. This trend not only heightens quarterly shipment volatility but also maintains surges in demand, which rental fleets are poised to meet. In a shift, public-sector buyers are leaning towards leasing rather than outright purchases. This strategy helps them sidestep the burden of depreciating assets on municipal balance sheets, consequently boosting rental penetration. In response, OEMs are strategically positioning their inventory close to major DOT districts, ensuring they're ready for last-minute orders.
Labor Scarcity Driving Equipment-Rental Penetration
By the end of the decade, a significant portion of the construction workforce is expected to retire, leaving contractors in search of skilled operators. BLS.GOV. To address this skills gap, rental companies are now offering bundled services that combine operator training with telematics dashboards, making machine control and compliance more straightforward. With rising interest rates, mid-tier credit applicants are seeing lease quotes becoming increasingly expensive-the balance is tipping towards renting rather than buying. This shift is particularly pronounced among smaller firms that don't have access to captive finance programs. In light of these trends, the American Rental Association is predicting record-high rental penetration in the coming years, aligning with the channel's steady growth trajectory over the forecast period .
Steep Increases in Equipment-Financing Rates Post-2023
By mid-2023, the Federal Reserve raised its benchmark rate significantly, effectively doubling borrowing costs compared to a couple of years prior. This increase added substantial costs to the monthly lease of high-value equipment like crawler excavators. Small contractors, lacking investment-grade credit, now face higher lease quotes, making short-term rentals a more viable option or forcing delays in fleet upgrades. This trend is reflected in a notable decline in new-business volume reported by the Equipment Leasing and Finance Association during the first half of 2025. Meanwhile, OEMs introduced zero-percent promotions on compact models, extending through late 2025. While this approach supports sales volumes, it puts pressure on dealer margins and raises concerns about its long-term viability once rate subsidies are removed.
Other drivers and restraints analyzed in the detailed report include:
- Rise of Electrified and Hybrid Excavator Models
- Accelerated Urban-Renewal Projects in Tier-2 US Cities
- Volatile Steel Prices Impacting OEM Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crawler excavators generated 67.73% of 2025 revenue in the US crawler earthmoving machine market, supported by their utility in trenching, mass excavation, and demolition. Compact tracked loaders, however, are on course for a 6.43% CAGR between 2026 and 2031, reflecting a structural pivot toward infill housing and urban renewal that favors smaller footprints and turf-friendly undercarriages.
Vacuum from fleet turnover in the heavy-duty bulldozer arena funnels incremental sales to excavator-mounted grade-control attachments, an upsell path that OEMs monetize through proprietary 3D machine-control software. Telecommunications trenching tied to the BEAD program also buttresses the "Others" category, where specialty machines and attachments see a demand uptick amid the USD 42.45 billion rural broadband rollout.
Internal combustion engines retained 83.31% share in 2025, yet electric and hybrid models are forecast to post a 6.45% CAGR through 2031, steadily enlarging their slice of the US crawler earthmoving machine market. Volvo CE's five-model hybrid line delivers 20% fuel savings, while Komatsu's regenerative swing harness lifts productivity 15%, tilting operating-expense math in favor of hybrids despite upfront price premiums. California's zero-emission procurement rule, effective 2024, fast-tracks coastal adoption, whereas heartland states await broader charging networks before committing to fleet-wide electrification.
Diesel machines still dominate quarrying and long-haul earthmoving due to superior energy density and refueling convenience, and Tier-4 hardware bumps fuel efficiency 3%-6% compared with Tier 3. Nevertheless, battery-pack modularity and falling cell costs are closing the economics gap faster than previously modeled, especially in the sub-6-ton mini-excavator class, where daily duty cycles rarely exceed eight hours. As hybrid penetration rises, OEMs gain a recurring revenue stream from software unlocks that optimize power-split algorithms and battery health monitoring, reinforcing after-sales stickiness across the US crawler earthmoving machine market.
Complete Report Scope:
- By Equipment Type
- Crawler Excavators
- Crawler Bulldozers
- Crawler Loaders
- Crawler Cranes and Pipe-layers
- Compact Tracked Loaders and Skid-steers
- Others (Trencher, Drill Rig, etc.)
- By Propulsion
- Internal Combustion Engine (ICE)
- Electric and Hybrid
- By Engine Power Output
- Below 100 HP
- 100-200 HP
- 201-400 HP
- Above 400 HP
- By Application
- Construction
- Mining and Quarrying
- Agriculture and Forestry
- Others
- By Distribution Channel
- Direct OEM Sales
- Authorized Dealers
- Rental and Leasing Firms
List of Companies Covered in this Report:
- Caterpillar Inc.
- Komatsu Ltd.
- John Deere
- Volvo CE
- Hitachi Construction Machinery
- Doosan Bobcat Inc.
- SANY America
- Kobelco USA
- CASE Construction Equipment (CNH Industrial)
- Takeuchi US
- Kubota Tractor Corp.
- JCB North America
- LiuGong North America
- Hyundai CE Americas
- Yanmar CE
- Liebherr Corporation
- Wacker Neuson
- XCMG North America
- Sunward USA
- Mecalac North America
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Boom in federal infrastructure funding (IIJA, IRA)
- 4.2.2 Labor scarcity driving equipment-rental penetration
- 4.2.3 Rise of electrified and hybrid excavator models
- 4.2.4 Accelerated urban-renewal projects in Tier-2 US cities
- 4.2.5 Digitized job-site management and telematics integration
- 4.2.6 Forestry wildfire-mitigation incentives (USFS)
- 4.3 Market Restraints
- 4.3.1 Steep increases in equipment-financing rates post-2023
- 4.3.2 Volatile steel prices impacting OEM margins
- 4.3.3 Tight Tier-4 emission-compliance costs for OEMs
- 4.3.4 Supply-chain fragility for hydraulic components
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Crawler Excavators
- 5.1.2 Crawler Bulldozers
- 5.1.3 Crawler Loaders
- 5.1.4 Crawler Cranes and Pipe-layers
- 5.1.5 Compact Tracked Loaders and Skid-steers
- 5.1.6 Others (Trencher, Drill Rig, etc.)
- 5.2 By Propulsion
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Electric and Hybrid
- 5.3 By Engine Power Output
- 5.3.1 Below 100 HP
- 5.3.2 100-200 HP
- 5.3.3 201-400 HP
- 5.3.4 Above 400 HP
- 5.4 By Application
- 5.4.1 Construction
- 5.4.2 Mining and Quarrying
- 5.4.3 Agriculture and Forestry
- 5.4.4 Others
- 5.5 By Distribution Channel
- 5.5.1 Direct OEM Sales
- 5.5.2 Authorized Dealers
- 5.5.3 Rental and Leasing Firms
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 John Deere
- 6.4.4 Volvo CE
- 6.4.5 Hitachi Construction Machinery
- 6.4.6 Doosan Bobcat Inc.
- 6.4.7 SANY America
- 6.4.8 Kobelco USA
- 6.4.9 CASE Construction Equipment (CNH Industrial)
- 6.4.10 Takeuchi US
- 6.4.11 Kubota Tractor Corp.
- 6.4.12 JCB North America
- 6.4.13 LiuGong North America
- 6.4.14 Hyundai CE Americas
- 6.4.15 Yanmar CE
- 6.4.16 Liebherr Corporation
- 6.4.17 Wacker Neuson
- 6.4.18 XCMG North America
- 6.4.19 Sunward USA
- 6.4.20 Mecalac North America
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 搭乘用式旋轉耙草機市場:全球市場預測,2026-2032年拖曳式旋轉耙草機市場:全球市場預測,2026-2032年鑿式耕耘機市場:全球市場預測,2026-2032年乾草和飼料機械市場:全球市場預測,2026-2032年乾肥料儲存設備市場:全球市場預測,2026-2032年
 菲律賓履帶式土木工程機具:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)印尼履帶式土木工程機具:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)軟性室內筒倉市場:依材料、容量、配置、安裝類型和最終用途產業分類-全球預測,2026-2032年單螺旋式糧食運輸車市場按容量範圍、最終用戶、糧食類型和分銷管道分類,全球預測(2026-2032年)糧食螺旋輸送車市場按產品類型、動力來源、最終用途和銷售管道分類-2026-2032年全球預測