


 |
市場調查報告書
商品編碼
2154244
歐洲二手施工機械:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Europe Used Construction Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
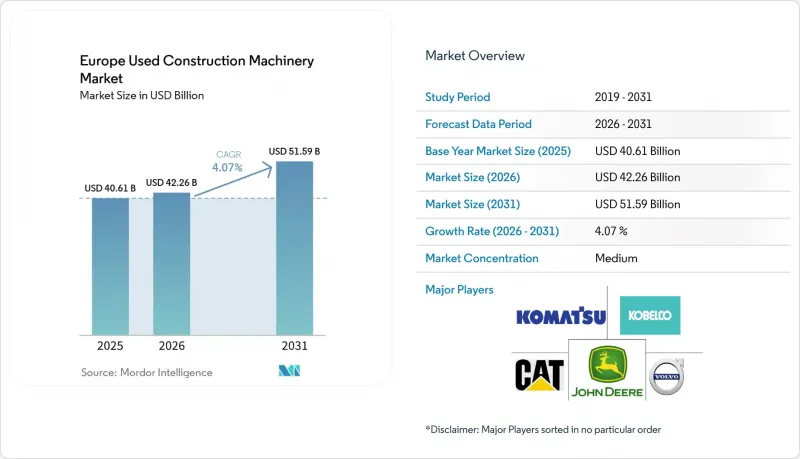
據 Mordor Intelligence 稱,2025 年歐洲二手施工機械市場價值為 406.1 億美元,預計 2026 年將達到 422.6 億美元,預計到 2031 年將達到 515.9 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.07%。
歐洲二手施工機械市場趨勢與洞察
歐盟基礎設施獎勵策略正在加速推進。
歐盟的「下一代歐盟」(NextGenerationEU)計畫和修訂後的泛歐交通網路(TEN-T)指南正為鐵路隧道、港口和高速公路項目撥出大量資金,從而推動了對二手運作時挖掘機和鉸接式推土機的需求。波蘭的「復甦與韌性基金(RRF)」預算正在加速喀爾巴阡山脈公路的建設,導致二手推土機的需求激增。在西班牙,鐵路現代化改造計畫正在推動小型挖土機在都市區車站維修的應用。公共工程承包商傾向於選擇符合第四階段排放標準的機械設備以滿足採購限制。這種選擇不僅能維持機械設備的殘值,還能提高車隊的更新換代頻率。由於預計專案儲備穩定,二手價格保持穩定,這促使設備所有者儘早出售資產。
過渡到符合第五階段排放標準的車隊
第五階段非道路排放標準的實施迫使租賃公司和大型建築公司逐步淘汰符合第三階段和第四階段臨時標準的設備,以避免罰款。這些法規要求將顆粒物排放量限制在特定閾值以下,並降低超過一定功率輸出的引擎的氮氧化物排放量。沃爾沃建築設備公司透露,交付的大部分設備均符合第五階段排放標準。然而,許多不符合第五階段排放標準的車型仍在運作,預計未來幾年將轉售。符合第五階段排放標準的設備在競標會上的價格顯著高於不符合標準的設備,而不符合標準的柴油設備則流入法規較為寬鬆的出口市場,凸顯了市場兩極化的趨勢。此外,由於買家對引擎運作小時數和排放氣體系統歷史記錄的需求,遠端資訊處理技術的應用正在加速發展。
高利率下的建設與資本投資波動
在歐洲央行大幅收緊貨幣政策後,主要市場的抵押貸款利率在房屋抵押貸款,主因是住宅市場低迷。經銷商面臨庫存增加的困境,導致中價位殘值承壓。義大利和希臘等國正努力應對政府債券利差擴大、基礎設施競標延遲以及續約週期延長等問題。租賃公司已將其車隊轉向物流和倉儲項目,但這種設備組合的變化僅部分緩解了土木工程行業的低迷。在電動車市場,租賃公司正日益重視在其車隊中增加電動車,以符合永續性目標和不斷變化的消費者偏好。
細分市場分析
2025年,挖土機在歐洲二手施工機械市場佔有35.92%的佔有率。這反映了其在土木工程、拆除和公共產業等廣泛領域的卓越性能和多功能性。車隊所有者利用挖土機實現最高的轉售流動性,從而能夠以穩定的價格定期更換設備。緊隨其後的是裝載機,其市場佔有率較大,主要用於採石場和物料輸送作業。而起重機和平土機的市佔率則維持在個位數中段。
自動卸貨卡車是成長最快的細分市場,預計到2031年將以4.59%的複合年成長率成長。這主要歸功於建築工人對鉸接式自卸卡車的青睞,這類卡車能夠穿越斯堪地那維亞半島的峽灣和阿爾卑斯山的陡峭山坡。 VolvoA45G是一款六輪驅動的自卸卡車,在經歷了幾個租賃週期後,終於出現在二手市場。即使大幅降價,它仍然展現出卓越的負載容量效率。隨著鉸接式卡車市場的成長,其殘值曲線也在改變。為了因應這項變化,德國和比利時的競標已開始在其季度拍賣會上增設專門的運輸車輛拍賣環節。
即使到了2025年,內燃機動力傳動系統預計仍將保持89.16%的市場佔有率,這表明柴油在多班次採石作業中使用的重型機械中具有卓越的能量密度。然而,混合動力和電池驅動車型正以每年6.78%的速度成長,其中小型挖土機尤為突出,它們只需一夜充電即可運作一整天。在歐洲的試驗中,Caterpillar的D6 XE柴油-電力混合動力推土機展現了顯著的燃油成本優勢。然而,其高昂的初始成本限制了其應用範圍,目前僅限於那些優先考慮永續性的大規模建築公司。
電動機械的普及率正在迅速提升,尤其是在小型挖土機和滑移裝載機領域。沃爾沃的「ECR25 Electric」在競標會上拍出了高價,這主要是因為如果這些機型的運作時間較短,都市區建設公司就可以避免繳納排放氣體相關的收費。買家通常會對充電循環次數較高的電動機械進行折扣,因為他們預計這些機械可能需要更換電池組,但定價過程變得越來越複雜。這主要是由於遠端資訊處理資料揭露的日益標準化,充電狀態和循環歷史記錄現在通常都會在競標會上揭露。
預計到2025年,重量超過11噸的大型機車將佔交易總量的46.23%,主要得益於連接德國和丹麥的費馬恩海峽隧道等大型基礎建設項目。同時,重量低於6噸的小型機車預計將實現最高的成長率,年複合成長率將達到4.69%,這主要受都市區改造和維修需求的推動。
租賃公司通常會定期更新其小型機械設備。這種做法導致大量運作使用時數的Takeuchi TB216和Bobcat E10e挖土機湧入競標市場。同時,在重型設備領域,利勃海爾R 980 SME礦用挖土機在採石場長期使用後也出現在二手市場。儘管二手價格低於新機零售價,但市場對這些挖土機的需求依然強勁,尤其是在波蘭和葡萄牙,這些業者需要鏟鬥容量超過6立方公尺的機型。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟加速基礎設施獎勵策略(下一代基礎建設、泛歐交通運輸網路)
- 向符合第五階段排放標準的車輛過渡是推動升級的主要因素。
- 數位競標平台提升流動性
- 節能維修熱潮(歐盟綠色交易)
- 來自中東和非洲的買家正利用歐元疲軟的機會透過線上競標。
- OEM翻新產品 + 遠端資訊處理訂閱
- 市場限制因素
- 高利率環境下建築與資本投資的波動性
- 超低排放氣體區正在降低老舊柴油車的價值。
- 出口運費上漲給利潤率帶來壓力。
- 中國製造的低成本播放設備大量湧入市場。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依設備類型
- 挖土機
- 裝載機
- 移動式起重機
- 平土機機
- 推土機
- 壓路機
- 自動卸貨卡車
- 其他
- 依推進類型
- 內燃機
- 油電混合/電池式電動車
- 氫燃料電池
- 按設備尺寸
- 大型(11噸或以上)
- 中等大小(6-11噸)
- 小型/迷你型(6噸以下)
- 依輸出類型
- 250馬力或以下
- 250~500 HP
- 500馬力或以上
- 透過使用
- 基礎設施
- 住宅/商業建築
- 採礦和採石
- 石油和天然氣管道
- 工業和製造業
- 其他
- 按設備壽命
- 不到5年
- 5-10年
- 10-15年
- 超過15年
- 按銷售管道
- 交易商/仲介
- 競標
- 線上平台
- 國家
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 瑞典
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- Volvo Construction Equipment
- Liebherr-International Deutschland GmbH
- Komatsu Ltd.
- JCB Ltd.
- Hitachi Construction Machinery
- Deere & Company
- Kobelco Construction Machinery
- CNH Industrial(CASE)
- Wacker Neuson SE
- Kubota Corp.
- Doosan Infracore
- Hyundai Construction Equipment
- SANY Group
- Manitou Group
- Terex Corporation
- Yanmar CE
- Atlas GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the European used construction machinery market size was valued at USD 40.61 billion in 2025, is estimated at USD 42.26 billion in 2026, and is projected to reach USD 51.59 billion by 2031, growing at a CAGR of 4.07% from 2026 to 2031.
Europe Used Construction Machinery Market Trends and Insights
Accelerated EU Infrastructure Stimulus
The EU's NextGenerationEU and updated TEN-T guidelines allocate substantial funding to rail tunnels, ports, and highways, favoring high-hour excavators and articulated haulers sourced from the secondary market . Poland's Recovery & Resilience Facility budget has fast-tracked contracts for the Via Carpatia highway, leading to a surge in demand for pre-owned dozers. In Spain, a railway modernization package is driving the acquisition of compact excavators for upgrades at urban stations. Public contractors, navigating procurement limits, are gravitating towards Stage IV machines. This choice not only safeguards the machines' residual value but also encourages more frequent fleet turnover. With a steady project pipeline in sight, resale prices have stabilized, motivating owners to auction off their assets sooner.
Shift to Stage V-Compliant Fleets
The enforcement of Stage V off-road regulations compelled rental firms and major contractors to phase out Tier 3 and Tier 4 interim equipment to sidestep penalties. These regulations limit particulate emissions to below a specific threshold and reduce NOx emissions for engines exceeding a certain power output. Volvo CE revealed that the majority of its deliveries were Stage V machines . However, many pre-Stage V units still operate and are set for resale in the coming years. Stage V units command a significant premium at auctions, while non-compliant diesel units find their way to export markets with more lenient regulations, highlighting a distinct two-tier market. Furthermore, the push for telematics is on the rise, driven by buyers' demands for documented histories of engine hours and emission systems.
Construction-Capex Volatility Amid High Rates
The European Central Bank held its deposit rate steady after significant tightening, leading mortgage rates to surpass levels seen in major markets. Eurostat highlighted a decline in eurozone construction output, driven primarily by falls in the residential sector . Dealers, facing higher inventories, exert downward pressure on mid-tier residual values. Countries like Italy and Greece grapple with widening sovereign-debt spreads, postponed infrastructure tenders, and extended replacement cycles. While rental firms shifted their fleets toward logistics and warehouse projects, the change in equipment mix only partially mitigated the downturn in civil works. In the electric vehicle market, rental firms are increasingly focusing on integrating EVs into their fleets to align with sustainability goals and evolving consumer preferences.
Other drivers and restraints analyzed in the detailed report include:
- Digital Auction Platforms Deepen Liquidity
- Energy-Efficient Renovation Boom
- Ultra-Low-Emission Zones Depress Older-Diesel Values
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The excavator category captured 35.92% of the European used construction equipment market in 2025, reflecting a broad installed base and versatility across civil works, demolition, and utilities. Fleet owners capitalized on excavators, achieving the highest resale liquidity. This allowed them to rotate units periodically at robust prices. Following excavators and loaders, the category of loaders captured a significant share, primarily serving quarries and material-handling tasks. Meanwhile, cranes and graders occupied mid-single-digit market positions.
Dump trucks are the fastest-growing segment, with a 4.59% CAGR to 2031, as contractors favor articulated haulers that navigate Scandinavian fjord terrain and Alpine gradients. Volvo's A45G, boasting a six-wheel drive, makes its debut on the secondary market after several rental cycles. Even with a significant discount, it still delivers notable payload productivity. As the articulated segment grows, it's reshaping residual-value curves. This change has prompted auctioneers in Germany and Belgium to launch dedicated hauler rings in their quarterly events.
Internal-combustion powertrains retained 89.16% market share in 2025, underscoring diesel's superior energy density for heavy machines deployed on multi-shift quarry operations. However, the hybrid-and-battery cohort is expanding at 6.78% per year, led by compact excavators where overnight charging suffices for daily duty cycles. In European trials, Caterpillar's diesel-electric D6 XE dozer showcased significant fuel savings. However, its steeper upfront price tag has confined its adoption primarily to larger contractors with a sustainability focus.
Electric adoption is surging, particularly in mini-excavators and skid-steers. Volvo's ECR25 Electric is fetching premium prices at auctions, largely because its low-hour units allow urban contractors to sidestep emissions-related fees. While buyers typically discount electrics with higher charge cycles to account for potential battery-pack replacements, the pricing process is becoming more refined. This is largely due to the increasing standardization of telematics data disclosures, which now commonly include state-of-charge and cycle history at auctions.
Heavy units above 11 tonnes accounted for 46.23% of 2025 transactions, owing to large-scale infrastructure projects such as the Fehmarnbelt Tunnel between Germany and Denmark, while sub-6-tonne compacts will post the fastest 4.69% CAGR on urban-infill and renovation demand.
Rental companies typically refresh their compact fleets on regular cycles. This routine results in a significant influx of low-hour Takeuchi TB216 and Bobcat E10e units entering auction channels. Meanwhile, in the heavy machinery segment, Liebherr's R 980 SME mining excavator, after extended use at quarry sites, makes its debut in the secondary market. Despite trading at a discount to its new list price, the excavator continues to see robust demand, particularly from Polish and Portuguese operators seeking bucket capacities exceeding 6 m3.
Complete Report Scope:
- By Equipment Type
- Excavator
- Loader
- Mobile Cranes
- Motor Graders
- Bulldozers
- Road Rollers
- Dump Trucks
- Others
- By Propulsion Type
- Internal Combustion
- Hybrid / Battery-Electric
- Hydrogen Fuel-Cell
- By Equipment Size
- Heavy (Above 11 t)
- Medium (6-11 t)
- Compact / Mini (Below 6 t)
- By Power Output
- Up to 250 HP
- 250 - 500 HP
- Above 500 HP
- By Application
- Infrastructure
- Residential and Commercial Construction
- Mining and Quarrying
- Oil and Gas / Pipelines
- Industrial and Manufacturing
- Others
- By Equipment Age
- Below 5 Years
- 5 - 10 Years
- 10 - 15 Years
- Above 15 Years
- By Sales Channel
- Dealer / Broker
- Auction
- Online Platforms
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Sweden
- Rest of Europe
List of Companies Covered in this Report:
- Caterpillar Inc.
- Volvo Construction Equipment
- Liebherr-International Deutschland GmbH
- Komatsu Ltd.
- JCB Ltd.
- Hitachi Construction Machinery
- Deere & Company
- Kobelco Construction Machinery
- CNH Industrial (CASE)
- Wacker Neuson SE
- Kubota Corp.
- Doosan Infracore
- Hyundai Construction Equipment
- SANY Group
- Manitou Group
- Terex Corporation
- Yanmar CE
- Atlas GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated EU Infrastructure Stimulus (NextGen, TEN-T)
- 4.2.2 Shift To Stage V-Compliant Fleets Drives Renewal
- 4.2.3 Digital Auction Platforms Deepen Liquidity
- 4.2.4 Energy-Efficient Renovation Boom (EU Green Deal)
- 4.2.5 MEA Buyers Exploiting Weak Euro Via Online Bids
- 4.2.6 OEM Refurbishment + Telematics Subscriptions
- 4.3 Market Restraints
- 4.3.1 Construction-Capex Volatility Amid High Rates
- 4.3.2 Ultra-Low-Emission Zones Hurt Older Diesel Values
- 4.3.3 Export Freight-Rate Spikes Squeeze Margins
- 4.3.4 Influx of Low-Cost Rebuilt Chinese Equipment
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD), Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Excavator
- 5.1.2 Loader
- 5.1.3 Mobile Cranes
- 5.1.4 Motor Graders
- 5.1.5 Bulldozers
- 5.1.6 Road Rollers
- 5.1.7 Dump Trucks
- 5.1.8 Others
- 5.2 By Propulsion Type
- 5.2.1 Internal Combustion
- 5.2.2 Hybrid / Battery-Electric
- 5.2.3 Hydrogen Fuel-Cell
- 5.3 By Equipment Size
- 5.3.1 Heavy (Above 11 t)
- 5.3.2 Medium (6-11 t)
- 5.3.3 Compact / Mini (Below 6 t)
- 5.4 By Power Output
- 5.4.1 Up to 250 HP
- 5.4.2 250 - 500 HP
- 5.4.3 Above 500 HP
- 5.5 By Application
- 5.5.1 Infrastructure
- 5.5.2 Residential and Commercial Construction
- 5.5.3 Mining and Quarrying
- 5.5.4 Oil and Gas / Pipelines
- 5.5.5 Industrial and Manufacturing
- 5.5.6 Others
- 5.6 By Equipment Age
- 5.6.1 Below 5 Years
- 5.6.2 5 - 10 Years
- 5.6.3 10 - 15 Years
- 5.6.4 Above 15 Years
- 5.7 By Sales Channel
- 5.7.1 Dealer / Broker
- 5.7.2 Auction
- 5.7.3 Online Platforms
- 5.8 By Country
- 5.8.1 Germany
- 5.8.2 United Kingdom
- 5.8.3 France
- 5.8.4 Italy
- 5.8.5 Spain
- 5.8.6 Sweden
- 5.8.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Caterpillar Inc.
- 6.4.2 Volvo Construction Equipment
- 6.4.3 Liebherr-International Deutschland GmbH
- 6.4.4 Komatsu Ltd.
- 6.4.5 JCB Ltd.
- 6.4.6 Hitachi Construction Machinery
- 6.4.7 Deere & Company
- 6.4.8 Kobelco Construction Machinery
- 6.4.9 CNH Industrial (CASE)
- 6.4.10 Wacker Neuson SE
- 6.4.11 Kubota Corp.
- 6.4.12 Doosan Infracore
- 6.4.13 Hyundai Construction Equipment
- 6.4.14 SANY Group
- 6.4.15 Manitou Group
- 6.4.16 Terex Corporation
- 6.4.17 Yanmar CE
- 6.4.18 Atlas GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


