


 |
市場調查報告書
商品編碼
2124876
專業音訊:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Professional Audio - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年專業音訊市場價值為 125 億美元,預計到 2031 年將從 2026 年的 132.6 億美元成長至 178.2 億美元,預測期(2026-2031 年)複合年成長率為 6.1%。
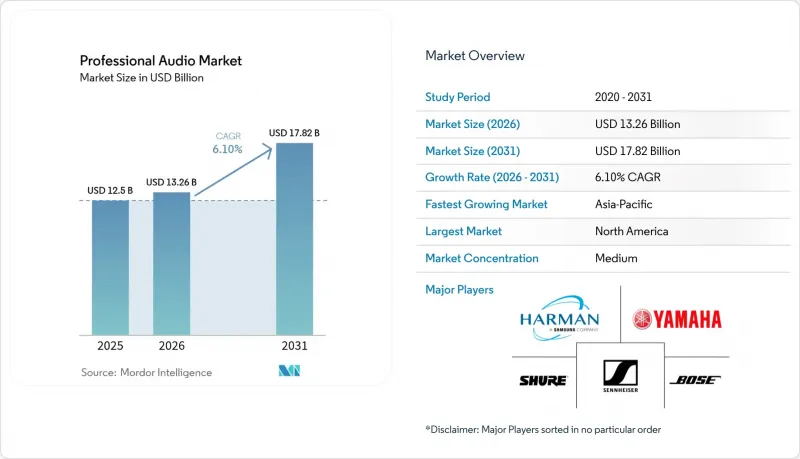
本報告按產品(揚聲器、功率放大器、混音主機、麥克風、耳機及其他)、連接方式(有線、無線)、最終用戶(企業、場館/活動、零售/酒店、媒體/娛樂及其他)、應用領域(現場擴聲、錄音棚及其他)和地區進行細分。市場預測以美元計價。
全球專業音訊市場趨勢與洞察
實況活動和體驗式行銷的快速擴張
2024年,大型演唱會門票銷量年增26%,促使租賃公司和場館運營商用心形指向子陣列系統替換老舊的揚聲器陣列,以在滿足更嚴格的噪音法規的同時,保持強勁的音效。音樂節主辦單位正透過高級音響區域獲利,將體驗式行銷與贊助收入結合,例如2025年的Ultra音樂節。混合型企業活動需要現場觀眾和虛擬觀眾之間實現低延遲連接,這推動了高可擴展性數位主機的銷售。 Sphere Entertainment公司安裝的16.7萬個揚聲器展示了身臨其境型架構如何增強品牌互動。因此,專業音訊市場對靈活的揚聲器配置和高密度無線通道的需求日益成長,這些配置和通道能夠簡化演出快速切換。
在創作者經濟中,對專業錄音室級設備的需求正在激增。
根據統計,2024年中國線上音訊用戶將達7.47億,市場規模達688.6億美元。這凸顯了個人內容創作者對專業採購決策的巨大影響力。同年,全球播客收入突破300億美元,促使麥克風製造商推出兼具便利性和擴充性的USB-XLR混合產品。品牌視覺美感也至關重要。大型廣播級麥克風提升了攝影機的可靠性,並推動了舒爾MV7i等整合即時音訊處理功能的產品的流行。中型製造商正透過將軟體插件與硬體捆綁銷售來抓住這一機遇,將新用戶轉化為訂閱用戶。這些因素正在將終端用戶群體擴展到傳統錄音室之外,從而擴大專業音訊市場的潛在規模。
半導體供應鏈的持續波動
DSP核心和RF收發器的前置作業時間超過60週,迫使設計團隊要麼認證替代元件,要麼移除一些進階功能。由於關稅上漲推高了運輸成本,美國半導體進口額在2024年達到1,390億美元。中小型音訊品牌被迫與大型科技公司競爭晶圓配額,往往需要支付附加費或減少產量。組件過時速度加快,一些供應商正在逐步淘汰數位產品SKU,轉而發展晶片數量更少的類比產品線。因此,在晶圓廠產能滿足需求之前,專業音響市場的利潤率預計將持續走低。
細分市場分析
預計到2025年,揚聲器將佔專業音訊市場的38.02%,鞏固其在巡迴、固定安裝和混合型場館中的核心地位。疫情導致的運作期過後,揚聲器的更新換代速度加快,許多場館採用了心形指向性子陣列揚聲器,這種揚聲器既能提高低頻指向性,又能符合市政噪音法規。同時,受頻段重新分配的監管措施推動,無線麥克風正以7.45%的複合年成長率快速成長,迫使用戶停止使用類比UHF設備。製造商正在積極應對,推出能夠適應頻段變窄並即使在射頻高度擁擠的環境中也能保持效能的加密數位平台。
在揚聲器領域,高附加價值需求正推動著擴大機、吊掛和控制軟體的成長,這些軟體透過基於有限脈衝響應 (FIR) 的波束控制來提升系統性能。供應商正在部署支援預測模組的軟體訂閱服務,將一次性硬體銷售轉化為持續收入。麥克風製造商正在探索基於無線麥克風存取系統 (WMAS) 的生態系統,例如森海塞爾的 Spectera,它在單一 6MHz 頻段內提供 64 個通道,展示了先進的調製技術如何解決頻段限制問題。 Dante 分線盒和支援 PoE 供電的舞台介面箱等配件正在填補整合空白,並進一步擴大供應商在專業音訊市場的佔有率。
到2025年,有線解決方案仍將佔據專業音訊市場56.85%的佔有率,這主要得益於政府機構和廣播演播室等對射頻風險具有較高容忍度的關鍵任務應用。 Cat6a線纜和冗餘環形拓撲結構可將延遲降至接近零,並支援PoE++供電。然而,隨著Wi-Fi 7開放6GHz頻段通道並改善確定性調度,預計到2031年,無線設備的複合年成長率將達到7.22%。早期基於Wi-Fi的Dante原型已展現出低於5毫秒的延遲,縮小了與乙太網路的效能差距。
電池技術的創新使可攜式擴聲箱在中等聲壓級下的運作時間延長至 40 小時,從而拓展了其在戶外環境中的應用。基於雲端的資料庫管理和調節應用程式簡化了部署,降低了容錯移轉運作的門檻。雖然假冒射頻模組使情況更加複雜,但行業宣傳活動正透過標準化的掃描協議來減少干擾。整合商正在設計有線和無線故障轉移架構,以確保有線和無線生態系統能夠共存,並使專業音訊市場同時滿足可靠性和柔軟性方面的要求。
區域分析
到2025年,北美將佔據專業音訊市場33.12%的佔有率。這主要得益於北美地區擁有全球最密集的體育館、大型教堂和廣播設施,這些設施需要持續的技術更新。儘管美國聯邦通訊委員會(FCC)的頻段重新分配迫使無線設備進行更新換代,但無障礙法規正在推動場館內助聽發送器的普及。企業房地產部門正優先考慮會議室的現代化改造,以透過AES67網路整合場館內和遠端音訊。加州和伊利諾伊州的區域製造群正在透過縮短全球供應鏈中斷期間的前置作業時間來增強區域韌性。
亞太地區正經歷最快成長,預計到2031年將以7.22%的複合年成長率成長。這主要歸功於中國和印度國家體育場館建設項目在設計階段就採用了Dante原生公共廣播系統。中國的「耳部經濟」正在塑造採購趨勢,將高階音響作為消費者設施的競爭優勢。印度整合商受益於政府的激勵措施,這些措施鼓勵本地化組裝並降低進口組件的關稅。該地區創新階層的崛起推動了對價格適中的錄音室介面的需求,並擴大了零工經濟中音樂家和播客等專業音訊市場的用戶群。儘管外匯波動仍然是預期風險,但製造商正盡可能以美元結算來規避此風險。
在歐洲,文化機構和企業園區對專業音訊設備的需求持續穩定。在歷史劇院的維修中,可回收的音箱箱體和低功率擴大機優先考慮,以符合歐盟的永續性目標。儘管英國脫歐增加了雙重認證的成本,但歐洲大陸的經銷商仍被敦促保持庫存緩衝,以確保供應的連續性。德國的Prolight+Sound等行業展會正在提升產品的知名度,而英國廣播業也正在加速採用符合ST 2110標準的主機。因此,歐洲專業音響市場的變革並非依賴大規模的產能擴張,而是依賴合規性和環保設計。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 實況活動和體驗式行銷的快速發展。
- 在創作者經濟中,對專業錄音室級設備的需求正在激增。
- 網路化音視訊與AES67/Dante互通性的發展
- 過渡到身臨其境型和空間音訊格式(杜比全景聲、MPEG-H)
- 企業對高保真音訊領域混合型工作方式的投資
- 政府撥款用於智慧城市公共廣播系統升級。
- 市場限制因素
- 半導體供應鏈的持續波動
- 旅遊系統總擁有成本高
- 假冒仿冒品和平行輸入商品氾濫成災
- 由於對電子廢棄物的監管更加嚴格,合規成本增加。
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 依產品
- 揚聲器
- 功率放大器
- 混音主機
- 麥克風
- 耳機
- 配件及其他物品
- 透過連接方式
- 有線
- 無線的
- 最終用戶
- 公司
- 場地/活動
- 零售和酒店
- 媒體與娛樂
- 教育機構及宗教場所
- 透過使用
- 現場擴聲
- 錄音棚
- 廣播和串流媒體
- 固定音響系統與公共廣播
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 智利
- 阿根廷
- 南美洲其他地區
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 新加坡
- 澳洲
- 馬來西亞
- 亞太其他地區
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Shure Incorporated
- Sennheiser electronic GmbH & Co. KG
- Harman International Industries Inc.(JBL Professional)
- Yamaha Corporation
- Bose Corporation
- QSC LLC
- Audio-Technica Corporation
- LEWITT GmbH
- RCF Group SpA
- Music Tribe(Global Brands Ltd.)
- PreSonus Audio Electronics Inc.
- Mackie(LOUD Audio LLC)
- Allen and Heath Limited
- DiGiCo UK Ltd.
- Focusrite plc
- Avid Technology Inc.
- Powersoft SpA
- d&b audIoTechnik GmbH
- L-Acoustics Group
- Meyer Sound Laboratories Inc.
- Electro-Voice(Bosch Security Systems Inc.)
- Crown International(Harman)
- TASCAM(TEAC Corporation)
- Rode Microphones(Free-fly Pty Ltd)
- Zoom Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the professional audio market size was valued at USD 12.50 billion in 2025 and estimated to grow from USD 13.26 billion in 2026 to reach USD 17.82 billion by 2031, at a CAGR of 6.1% during the forecast period (2026-2031).
This report is Segmented by Product (Loudspeakers, Power Amplifiers, Mixing Consoles, Microphones, Headphones, and More), Connectivity (Wired, Wireless), End-User (Corporate, Venues and Events, Retail and Hospitality, Media and Entertainment, and More), Application (Live Sound Reinforcement, Recording Studios, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Professional Audio Market Trends and Insights
Rapid Expansion of Live-Events and Experiential Marketing
Ticket volumes at major concerts increased 26% year over year in 2024, spurring rental firms and venues to replace aging arrays with cardioid sub-array systems that meet stricter noise ordinances while preserving punch. Festival operators monetize premium sound zones that tie experiential marketing to sponsorship revenue, as seen at Ultra Music Festival 2025. Hybrid corporate shows need low-latency bridging between onsite and virtual audiences, driving sales of scalable digital consoles. Sphere Entertainment's 167,000-speaker install illustrates how immersive architecture elevates brand engagement. The professional audio market therefore sees elevated demand for flexible loudspeaker configurations and high-density wireless channels that streamline quick show turnovers.
Surging Creator-Economy Demand for Studio-Grade Gear
China logged 747 million online audio users in 2024, generating a sector worth USD 68.86 billion, underlining how individual content creators influence professional purchasing decisions. Global podcast revenue surpassed USD 30 billion the same year, pushing microphone makers to launch USB-XLR hybrids that combine convenience with expandability. Visual brand aesthetics matter; larger broadcast-style microphones improve on-camera credibility, boosting uptake of units such as Shure's MV7i that integrate real-time voice processing. Mid-tier manufacturers capitalize by bundling software plug-ins alongside hardware, converting first-time buyers into subscription clients. This driver enlarges the addressable professional audio market by expanding the end-user base beyond traditional studios.
Persistent Semiconductor Supply-Chain Volatility
Lead times for DSP cores and RF transceivers extend past 60 weeks, forcing design teams to qualify substitute parts or strip advanced features. U.S. semiconductor imports reached USD 139 billion in 2024 amid tariff hikes that raised landed costs. Smaller audio brands compete against large tech firms for wafer allocation, often paying premiums or shrinking production runs. Component obsolescence accelerates, leading some vendors to sunset digital SKUs in favor of analog lines requiring fewer chips. The professional audio market thus faces margin compression until fab capacity aligns with demand.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Networked-AV and AES67/Dante Interoperability
- Shift to Immersive and Spatial-Audio Formats
- High Total Cost of Ownership for Tour-Grade Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Loudspeakers contributed 38.02% of the professional audio market size in 2025, confirming their centrality across touring, fixed install, and hybrid venues. Replacement cycles accelerated after pandemic-era downtime, with many arenas adopting cardioid sub-arrays that improve low-frequency directionality while complying with municipal noise codes. Meanwhile, wireless microphones advance at an 7.45% CAGR on the back of regulatory spectrum reallocations that compel users to retire analog UHF units. Manufacturers answer with encrypted digital platforms that fit within shrinking frequency bands, safeguarding performance in congested RF environments.
The loudspeaker segment drives value-added demand for amplification, rigging, and control software that elevate system performance through FIR-based beam steering. Vendors unlock software subscriptions that activate prediction modules, converting one-time hardware sales into recurring revenue. Microphone makers explore WMAS-based ecosystems, such as Sennheiser's Spectera, which delivers 64 channels inside a single 6 MHz block and illustrates how advanced modulation counters spectrum scarcity. Accessories like Dante breakout boxes and PoE-powered stage boxes fill integration gaps, rounding out wallet share captured by vendors inside the professional audio market.
Wired solutions retained 56.85% share of the professional audio market size in 2025 thanks to mission-critical applications that resist RF risk, including government chambers and broadcast studios. Cat6a cable and redundant ring topologies guarantee near-zero latency and facilitate power distribution through PoE++. Yet wireless units are forecast to post a 7.22% CAGR to 2031 as Wi-Fi 7 unlocks 6 GHz channels and improves deterministic scheduling. Early Dante-over-Wi-Fi prototypes demonstrate sub-5 ms latency, narrowing the performance gap against Ethernet.
Battery innovation extends runtime to 40 hours at moderate SPL for portable PA boxes, widening addressable outdoor use cases. Managed-frequency coordination apps powered by cloud databases simplify deployment, lowering expertise barriers for volunteer operators. Despite counterfeit RF modules adding complexity, educational initiatives by industry bodies help mitigate interference through standardized scanning protocols. Wired and wireless ecosystems coexist as integrators design fail-over architectures that blend both, ensuring the professional audio market satisfies reliability and flexibility expectations simultaneously.
Complete Report Scope:
- By Product
- Loudspeakers
- Power Amplifiers
- Mixing Consoles
- Microphones
- Headphones
- Accessories and Others
- By Connectivity
- Wired
- Wireless
- By End-User
- Corporate
- Venues and Events
- Retail and Hospitality
- Media and Entertainment
- Education and Houses-of-Worship
- By Application
- Live Sound Reinforcement
- Recording Studios
- Broadcast and Streaming
- Installed Sound / Public-Address
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Chile
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Singapore
- Australia
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 33.12% of the professional audio market in 2025, backed by the world's densest concentration of arenas, megachurches, and broadcast facilities requiring rolling technology refreshes. FCC spectrum reallocation compels wireless replacements, while accessibility laws push venues to adopt assistive-listening transmitters. Corporate real-estate teams prioritize conference-room modernization that unifies in-room and remote voices via AES67 networks. Regional resilience is reinforced by local manufacturing clusters in California and Illinois that shorten lead times during global supply disruptions.
Asia-Pacific records the fastest pace, advancing at a 7.22% CAGR through 2031 as national stadium programs in China and India embed Dante-native public-address systems from blueprint stages. China's "ear economy" shapes procurement by requiring consumer-facing venues to adopt premium audio as a competitive differentiator. Indian integrators benefit from government incentives that localize assembly, lowering tariffs on imported components. The region's creative-class boom fuels demand for affordable studio interfaces, expanding the professional audio market base among gig-economy musicians and podcasters. Currency fluctuations remain a planning risk, yet manufacturers hedge by denominating contracts in USD where possible.
Europe demonstrates stable demand across cultural institutions and corporate campuses. Renovation of heritage theaters prioritizes recyclable loudspeaker cabinets and low-power amplifiers to align with EU sustainability targets. Brexit spurs dual-certification costs but also motivates continental distributors to hold buffer stock, maintaining supply continuity. German trade fairs like Prolight + Sound drive product visibility, while the United Kingdom broadcast sector accelerates adoption of ST 2110-compatible consoles. The professional audio market in Europe thus evolves through regulatory compliance and green design, rather than large-scale capacity increases.
- Shure Incorporated
- Sennheiser electronic GmbH & Co. KG
- Harman International Industries Inc. (JBL Professional)
- Yamaha Corporation
- Bose Corporation
- QSC LLC
- Audio-Technica Corporation
- LEWITT GmbH
- RCF Group S.p.A
- Music Tribe (Global Brands Ltd.)
- PreSonus Audio Electronics Inc.
- Mackie (LOUD Audio LLC)
- Allen and Heath Limited
- DiGiCo UK Ltd.
- Focusrite plc
- Avid Technology Inc.
- Powersoft S.p.A
- d&b audiotechnik GmbH
- L-Acoustics Group
- Meyer Sound Laboratories Inc.
- Electro-Voice (Bosch Security Systems Inc.)
- Crown International (Harman)
- TASCAM (TEAC Corporation)
- Rode Microphones (Free-fly Pty Ltd)
- Zoom Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid expansion of live-events and experiential marketing
- 4.2.2 Surging creator-economy demand for studio-grade gear
- 4.2.3 Growth of networked-AV and AES67/Dante interoperability
- 4.2.4 Shift to immersive and spatial-audio formats (Dolby Atmos, MPEG-H)
- 4.2.5 Corporate hybrid-work investments in high-fidelity audio
- 4.2.6 Government funding for smart-city public-address upgrades
- 4.3 Market Restraints
- 4.3.1 Persistent semiconductor supply-chain volatility
- 4.3.2 High total-cost-of-ownership for tour-grade systems
- 4.3.3 Proliferation of counterfeit/grey-market components
- 4.3.4 Rising e-waste regulations increasing compliance costs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Loudspeakers
- 5.1.2 Power Amplifiers
- 5.1.3 Mixing Consoles
- 5.1.4 Microphones
- 5.1.5 Headphones
- 5.1.6 Accessories and Others
- 5.2 By Connectivity
- 5.2.1 Wired
- 5.2.2 Wireless
- 5.3 By End-User
- 5.3.1 Corporate
- 5.3.2 Venues and Events
- 5.3.3 Retail and Hospitality
- 5.3.4 Media and Entertainment
- 5.3.5 Education and Houses-of-Worship
- 5.4 By Application
- 5.4.1 Live Sound Reinforcement
- 5.4.2 Recording Studios
- 5.4.3 Broadcast and Streaming
- 5.4.4 Installed Sound / Public-Address
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Chile
- 5.5.2.3 Argentina
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Singapore
- 5.5.4.5 Australia
- 5.5.4.6 Malaysia
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Shure Incorporated
- 6.4.2 Sennheiser electronic GmbH & Co. KG
- 6.4.3 Harman International Industries Inc. (JBL Professional)
- 6.4.4 Yamaha Corporation
- 6.4.5 Bose Corporation
- 6.4.6 QSC LLC
- 6.4.7 Audio-Technica Corporation
- 6.4.8 LEWITT GmbH
- 6.4.9 RCF Group S.p.A
- 6.4.10 Music Tribe (Global Brands Ltd.)
- 6.4.11 PreSonus Audio Electronics Inc.
- 6.4.12 Mackie (LOUD Audio LLC)
- 6.4.13 Allen and Heath Limited
- 6.4.14 DiGiCo UK Ltd.
- 6.4.15 Focusrite plc
- 6.4.16 Avid Technology Inc.
- 6.4.17 Powersoft S.p.A
- 6.4.18 d&b audiotechnik GmbH
- 6.4.19 L-Acoustics Group
- 6.4.20 Meyer Sound Laboratories Inc.
- 6.4.21 Electro-Voice (Bosch Security Systems Inc.)
- 6.4.22 Crown International (Harman)
- 6.4.23 TASCAM (TEAC Corporation)
- 6.4.24 Rode Microphones (Free-fly Pty Ltd)
- 6.4.25 Zoom Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 亞太地區專業視聽系統:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)專業視聽系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026-2030 年全球專業視音頻市場
 2026年網際網路協定媒體體驗(IPMX)專業影音(AV)串流媒體全球市場報告
 全球專業影音市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 專業音影片解決方案市場規模、佔有率和成長分析:按產品類型、技術、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 KVM 和專業影音市場:按類型、最終用戶和地區分類2026 年專業影像(Pro AV) 全球市場報告2026年高等教育專業視聽(Pro AV)全球市場報告2026年全球專業影像(AV)系統市場報告