


 |
市場調查報告書
商品編碼
2124646
非洲電信塔及相關設備市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)Africa Telecom Towers And Allied - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,非洲電信塔及相關設備市場預計到 2026 年價值 40.3 億美元,高於 2025 年的 39 億美元,預計到 2031 年將達到 47.5 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 3.35%。
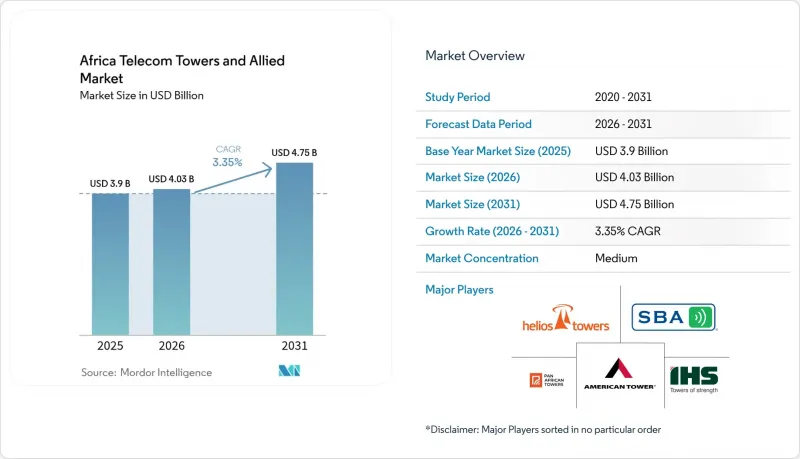
本報告按所有權類型(電信業者擁有、獨立鐵塔公司、其他)、安裝類型(屋頂、地面)、燃料類型(可再生能源、電網/柴油混合燃料)、鐵塔類型(單極塔、格構塔、拉線塔、隱藏式/暗裝塔)和國家細分。市場預測以價值(美元)和數量(已安裝單元數)表示。
非洲電信塔及相關設備市場的趨勢與洞察
加速非洲行動網路營運商的 4G/5G 部署
2024年及2025年初,非洲各地的行動網路業者新增了數百個5G基地台,推動撒哈拉以南非洲地區的5G用戶總數在2030年接近愛立信預測的4.2億。光是MTN集團就將其5G覆蓋範圍擴展至3000多個地點,推動了非洲電信鐵塔市場對共址託管的需求激增。在拉各斯、內羅畢和約翰尼斯堡,基地台密度特別迫切,因為這些地區使用5G中頻段需要更緊密的基地台間距。獨立鐵塔公司正利用這項迫切需求,提供承包製化建設方案,以加速營運商從傳統4G網路過渡到5G網路的上市速度。突尼斯近期推出商用5G服務進一步鞏固了這一發展勢頭,凸顯了全部區域對下一代連接技術的堅定承諾。
數據消費量和智慧型手機普及率的成長
在影片串流、社群媒體和行動支付的推動下,北非和西非的單一用戶資料使用量已飆升至兩位數GB。不斷成長的年輕人口和低價智慧型手機的進口進一步刺激了這一需求,迫使電信業者以超出最初預算的速度擴容。資料通訊流量的成長導致每個站點可租賃天線的數量增加,使得非洲主要都市地區的電信塔市場租戶比例從1.5倍提高到2倍。因此,隨著資料密集型服務的獎勵建立具有更高承載能力和光纖回程回程傳輸的未來型設施,以確保收入成長。
外匯波動和高主權風險
儘管大部分收入以該地貨幣計價,但債務和資本支出仍與美元掛鉤,這使得鐵塔業者在貨幣貶值期間面臨重大外匯損失的風險。 IHS Towers報告稱,2024年非洲多個市場將面臨顯著的外匯逆風,凸顯了貨幣對宏觀經濟週期的高度敏感性。主權評級等下調可能導致利率上升,可能削弱新建設的可行性或延緩再融資進程。電信業者和鐵塔公司正日益尋求自然對沖工具,例如與美元指數掛鉤的租金遞增條款,但由於外幣計費的監管上限,這些工具的應用仍然有限。
細分市場分析
預計到2025年,獨立鐵塔公司將佔據非洲電信鐵塔市場45.18%的佔有率,並在2031年之前以6.53%的複合年成長率成長。如此強勁的投資回報歸功於高達92.4%的運轉率以及多元化的國家投資組合,從而有效降低了外匯和監管風險。儘管在基礎設施共用受限的市場中,電信業者仍擁有資產,但隨著資產負債表精簡策略的日益成熟,將這些資產變現的壓力也越來越大。如果目前的資產出售按計畫進行,到2031年,非洲獨立鐵塔公司的電信鐵塔市場規模(以年租賃收入計)可能超過20.7億美元。
在網路控制至關重要的政治敏感地區,行動網路營運商(MNO)擁有的基地台仍然至關重要,但融資不佳的營運商越來越傾向於採用售後回租協議來資金籌措5G頻率使用費。合資鐵塔公司提供了一個折衷方案,競爭對手可以在不犧牲主動層差異化的前提下,共同投資於被動設施。美國鐵塔公司(American Tower)的選擇性參與策略凸顯了全球專業公司在複雜大都會圈所享有的利潤率優勢,而這一趨勢可能會加速非洲電信鐵塔產業的整合。
到2025年,地面基地台將佔非洲電信塔市場76.20%的佔有率,證明其在郊區和農村地區實現宏觀覆蓋方面具有成本效益。屋頂基地台雖然面積較小,但由於人口密集的商業區需要更密集的網格間距來容納5G中頻段頻率,其年複合成長率(CAGR)正以7.34%的速度成長。受市政景觀規劃和地價飆升的影響,在內羅畢、卡薩布蘭卡和約翰尼斯堡等城市中心,屋頂基地台是唯一可行的選擇。
地面塔架由於天線負載能力強且易於維修為可再生能源系統,因此每個站點的絕對效益較高。另一方面,屋頂塔架的許可核准速度更快,土木工程成本更低,使塔架業者能夠在現有覆蓋區域內創造額外收入。這種站點類型的巧妙組合將使非洲通訊塔架市場即使在數據流量模式變化的情況下也能保持柔軟性。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
- 分類學
第2章:調查方法
第3章執行摘要
- 電信鐵塔數量預測(單位:台,2023-2030 年)
- 電信鐵塔租賃收入預測(美元,2023-2030 年)
- 電信塔建設收入預測(美元,2023-2030 年)
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 非洲各地的行動通訊業者(MNO) 正在加速部署 4G/5G 網路。
- 數據消耗量增加和智慧型手機普及率上升
- 政府主導的農村通訊網路發展義務和普及服務基金
- 行動網路營運商 (MNO) 採取的輕資產網路策略正在推動通訊塔維護的外包。
- 為升級改造設施使用可再生能源提供綠色金融獎勵措施
- 對中立託管的室內DAS和小型基地台回程傳輸。
- 市場限制因素
- 外匯波動和高主權風險
- 長期存在許可證辦理和土地收購方面的瓶頸。
- 柴油供應中斷導致離網設施的營運成本增加。
- 區域城市光纖回程傳輸短缺阻礙了租戶租金的成長。
- 生態系分析
- 電信基礎設施監管狀況
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 依所有權類型
- 企業所有
- 獨立鐵塔公司
- 合資塔樓公司
- MNO 直銷
- 按安裝類型
- 屋頂
- 地面安裝
- 按燃料類型
- 可再生能源
- 電網/柴油混合動力
- 塔式
- 單極子
- 晶格型
- 支線類型
- 隱蔽/隱藏
- 國家
- 阿爾及利亞
- 肯亞
- 摩洛哥
- 南非
- 奈及利亞
- 迦納
- 埃及
- 坦尚尼亞
- 其他非洲國家(突尼斯、烏干達、尚比亞、塞內加爾等)
第6章 競爭情勢
- 市場集中度
- 重大併購詳情
- 主要供應商市佔率分析
- 公司簡介
- TowerCos
- American Tower Corporation
- IHS Towers(IHS Holding Limited)
- Helios Towers Plc
- SBA Communications Corporation
- Pan African Towers
- Atlas Tower Group Limited
- Eastcastle Infrastructure
- Paradigm Infrastructure Limited
- Hotspot Network Ltd
- Mobile Network Operator
- MTN Group
- Vodacom Group
- Airtel Africa plc
- Orange Middle East and Africa
- e& misr company
- Safaricom PLC
- Telkom SA SOC Limited
- Globacom Limited(Glo)
- Maroc Telecom SA
- WE(Telecom Egypt)
- Unitel Angola(Unitel SA)
- Econet Wireless Zimbabwe Ltd.
- Ethio Telecom
- Movitel Mozambique(Movitel SA)
- Moov Africa
- Sonatel Senegal(Sonatel SA)
- Yas Madagascar
- TowerCos
第7章 市場機會與未來展望
According to Mordor Intelligence, the Africa telecom towers and allied market size in 2026 is estimated at USD 4.03 billion, growing from 2025 value of USD 3.9 billion with 2031 projections showing USD 4.75 billion, growing at 3.35% CAGR over 2026-2031.
This report is Segmented by Ownership (Operator-Owned, Independent TowerCo, and More), Installation (Rooftop, Ground-Based), Fuel Type (Renewable-Powered, Grid/Diesel Hybrid), Tower Type (Monopole, Lattice, Guyed, Stealth/Concealed), and Country. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Installed Base).
Africa Telecom Towers And Allied Market Trends and Insights
Accelerated 4G/5G rollout by pan-African MNOs
Pan-African mobile network operators added hundreds of 5G sites in 2024 and early 2025, lifting total 5G subscriptions in Sub-Saharan Africa toward Ericsson's 420 million projection for 2030 . MTN Group alone expanded its 5G footprint to more than 3,000 sites, prompting a surge in colocation requests across the Africa telecom tower market . The densification imperative is especially acute in Lagos, Nairobi, and Johannesburg, where 5G mid-band spectrum requires closer site spacing. Independent TowerCos capitalize on this urgency by offering turnkey build-to-suit programs that shorten time-to-market for operators migrating from legacy 4G networks. The momentum is reinforced by the recent commercial 5G launch in Tunisia, underscoring the broad regional commitment to next-generation connectivity .
Rising data consumption and smartphone penetration
Video streaming, social media, and mobile payments are elevating per-subscriber data use into double-digit gigabyte ranges across North and West Africa. Young demographics and low-cost smartphone imports sustain this demand curve, compelling operators to add capacity faster than originally budgeted. Higher data volumes translate into larger leaseable antenna counts per site, pushing tenancy ratios across the Africa telecom tower market from 1.5x toward 2x in core metros. TowerCos are therefore incentivized to future-proof structures with stronger load capacities and fiber-ready backhaul, ensuring revenue upside as data-heavy services proliferate.
Volatile foreign-exchange and high sovereign risk
Revenue is largely denominated in local currencies, but debt and capex remain USD-linked, exposing TowerCos to material conversion losses during currency depreciations. IHS Towers reported notable FX headwinds in several African markets during 2024, underscoring sensitivity to macroeconomic cycles. Sovereign credit downgrades trigger higher interest rates that can render new builds unviable or slow refinancing efforts. Operators and TowerCos are increasingly exploring natural hedges such as USD-indexed lease escalators, but uptake remains limited by regulatory caps on foreign-currency billing.
Other drivers and restraints analyzed in the detailed report include:
- Government-led rural coverage mandates and universal service funds
- Asset-light network strategies by MNOs boosting tower outsourcing
- Lengthy permitting and land-acquisition bottlenecks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Independent TowerCos commanded 45.18% of the Africa telecom tower market share in 2025 and are on track for a 6.53% CAGR through 2031. The superior returns stem from 92.4% utilization rates and diversified country portfolios that smooth FX and regulatory risk. Operator-owned assets persist in markets with infrastructure-sharing constraints, but monetization pressure is rising as balance-sheet light strategies take hold. The Africa telecom tower market size for Independent TowerCos could exceed USD 2.07 billion in annual lease revenue by 2031 if current divestiture pipelines close on schedule.
MNO captive sites remain critical in politically sensitive geographies where network control is paramount; however, cash-strapped operators increasingly favor sale-leasebacks to fund 5G spectrum fees. Joint-venture TowerCos offer a middle path, letting rivals co-invest in passive plant without sacrificing active-layer differentiation. American Tower's selective entry strategy validates the margin advantage enjoyed by global specialists in complex metros, a dynamic likely to accelerate consolidation across the Africa telecom tower industry.
Ground-based towers held 76.20% of the Africa telecom tower market size in 2025, proving cost-effective for suburban and rural macro coverage. Rooftop installations, though smaller in absolute footprint, are gaining a 7.34% CAGR as 5G mid-band frequencies demand tighter grid spacing in densely populated business districts. Municipal aesthetic guidelines and mounting land prices make rooftops the only viable option in central Nairobi, Casablanca, and Johannesburg.
Ground-based towers still deliver higher absolute revenue per site thanks to greater antenna load capacity and ease of renewable-power retrofits. Yet rooftops promise faster permitting and reduced civil works expenditure, allowing TowerCos to capture incremental revenue within established coverage zones. This nuanced mix of site types ensures the Africa telecom tower market remains flexible as data-traffic patterns evolve.
Complete Report Scope:
- By Ownership
- Operator-owned
- Independent TowerCo
- Joint-Venture TowerCo
- MNO Captive
- By Installation
- Rooftop
- Ground-based
- By Fuel Type
- Renewable-powered
- Grid/Diesel Hybrid
- By Tower Type
- Monopole
- Lattice
- Guyed
- Stealth / Concealed
- By Country
- Algeria
- Kenya
- Morocco
- South Africa
- Nigeria
- Ghana
- Egypt
- Tanzania
- Rest of Africa (Tunisia, Uganda, Zambia, Senegal, and Others)
List of Companies Covered in this Report:
- TowerCos
- Mobile Network Operator
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- 1.3 Taxonomy
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
- 3.1 Telecom Tower Volume Estimates (Units, 2023-2030)
- 3.2 Telecom Tower Leasing Revenue Estimates (USD, 2023-2030)
- 3.3 Telecom Tower Construction Revenue Estimates (USD, 2023-2030)
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated 4G/5G rollout by pan-African MNOs
- 4.2.2 Rising data consumption and smartphone penetration
- 4.2.3 Government-led rural coverage mandates and universal service funds
- 4.2.4 Asset-light network strategies by MNOs boosting tower outsourcing
- 4.2.5 Green financing incentives for renewable power retrofits
- 4.2.6 Expansion of neutral-host indoor DAS and small-cell backhaul demand
- 4.3 Market Restraints
- 4.3.1 Volatile foreign-exchange and high sovereign risk
- 4.3.2 Lengthy permitting and land-acquisition bottlenecks
- 4.3.3 Diesel supply disruptions raising opex at off-grid sites
- 4.3.4 Fiber backhaul deficits limiting tenancy ratios in secondary cities
- 4.4 Ecosystem Analysis
- 4.5 Regulatory Landscape Related to Telecom Infrastructure
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Ownership
- 5.1.1 Operator-owned
- 5.1.2 Independent TowerCo
- 5.1.3 Joint-Venture TowerCo
- 5.1.4 MNO Captive
- 5.2 By Installation
- 5.2.1 Rooftop
- 5.2.2 Ground-based
- 5.3 By Fuel Type
- 5.3.1 Renewable-powered
- 5.3.2 Grid/Diesel Hybrid
- 5.4 By Tower Type
- 5.4.1 Monopole
- 5.4.2 Lattice
- 5.4.3 Guyed
- 5.4.4 Stealth / Concealed
- 5.5 By Country
- 5.5.1 Algeria
- 5.5.2 Kenya
- 5.5.3 Morocco
- 5.5.4 South Africa
- 5.5.5 Nigeria
- 5.5.6 Ghana
- 5.5.7 Egypt
- 5.5.8 Tanzania
- 5.5.9 Rest of Africa (Tunisia, Uganda, Zambia, Senegal, and Others)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Details of Major Mergers and Acquisitions
- 6.3 Market Share Analysis for top vendors
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 TowerCos
- 6.4.1.1 American Tower Corporation
- 6.4.1.2 IHS Towers (IHS Holding Limited)
- 6.4.1.3 Helios Towers Plc
- 6.4.1.4 SBA Communications Corporation
- 6.4.1.5 Pan African Towers
- 6.4.1.6 Atlas Tower Group Limited
- 6.4.1.7 Eastcastle Infrastructure
- 6.4.1.8 Paradigm Infrastructure Limited
- 6.4.1.9 Hotspot Network Ltd
- 6.4.2 Mobile Network Operator
- 6.4.2.1 MTN Group
- 6.4.2.2 Vodacom Group
- 6.4.2.3 Airtel Africa plc
- 6.4.2.4 Orange Middle East and Africa
- 6.4.2.5 e& misr company
- 6.4.2.6 Safaricom PLC
- 6.4.2.7 Telkom SA SOC Limited
- 6.4.2.8 Globacom Limited (Glo)
- 6.4.2.9 Maroc Telecom SA
- 6.4.2.10 WE (Telecom Egypt)
- 6.4.2.11 Unitel Angola (Unitel SA)
- 6.4.2.12 Econet Wireless Zimbabwe Ltd.
- 6.4.2.13 Ethio Telecom
- 6.4.2.14 Movitel Mozambique (Movitel S.A.)
- 6.4.2.15 Moov Africa
- 6.4.2.16 Sonatel Senegal (Sonatel SA)
- 6.4.2.17 Yas Madagascar
- 6.4.1 TowerCos
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment
- 7.2 Investment Analysis
- 7.3 Analyst Suggestions and Recommendations

 美國電信塔:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)電信塔:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 通訊塔市場預測至2034年-按塔型、安裝方式、所有權方式、燃料類型、應用和地區分類的全球分析
 塔架管理軟體市場:依部署類型、塔架類型、最終用戶、功能和地區分類通訊塔市場:依部署方式、塔型、安裝方式、應用程式和區域分類
 通訊塔市場規模、佔有率、趨勢和預測:按塔型、燃料類型、安裝方式、所有權方式和地區分類,2026-2034 年
 隱蔽通訊塔市場規模、佔有率和成長分析:按偽裝設計/類型、塔架結構、頻率/頻段相容性、安裝位置和地區分類-2026-2033年產業預測
 行動電話基地台管理市場:依接取技術、塔型、安裝方式、服務類型、高度等級、組件類型及最終用戶產業分類-2026-2032年全球市場預測
 2026年全球數位雙胞胎市場報告
 2026-2030年全球電信塔市場