


 |
市場調查報告書
商品編碼
2121384
電信塔:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Telecom Towers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年通訊塔市場價值為 292.9 億美元,預計到 2031 年將達到 343 億美元,而 2026 年為 300.7 億美元,預測期(2026-2031 年)的複合年成長率為 2.67%。
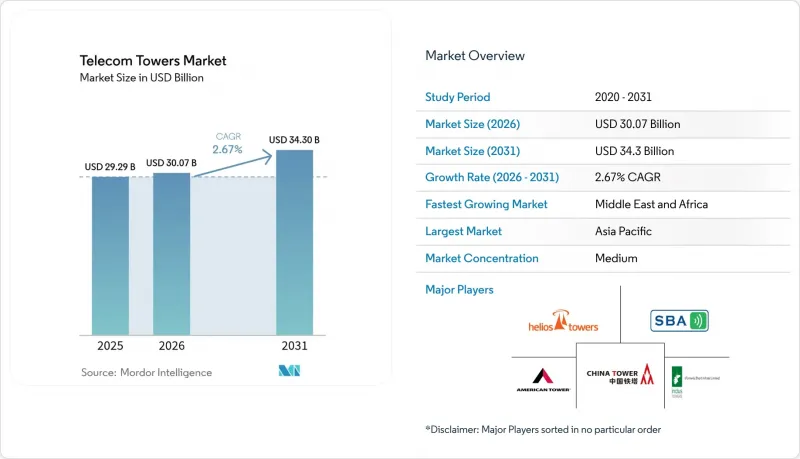
本報告按燃料類型(可再生、不可可再生)、塔架類型(格子形杆塔、拉線塔、單極塔、隱形塔)、安裝方式(屋頂、地面)、所有權(營運商擁有、合資企業、私人企業、行動網路營運商專屬式)和地區(北美、歐洲、亞太、中東和非洲、南美)進行細分。市場預測以美元計價。
全球通訊塔市場趨勢與洞察
5G網路的部署將加速基礎架構整合。
為了實現5G的低延遲目標,電信業者需要將基地台密度提高到4G的三到五倍,尤其是在高頻寬的毫米波頻譜。光是在拉丁美洲,預計到2030年5G連線用戶將達到4.25億,這既需要傳統的宏基地台,也需要數量不斷成長的小型基地台。監管機構正在積極應對這項挑戰。加拿大廣播通訊委員會(CRTC)簡化了安裝法規,允許營運商在現有設施中加裝5G無線電設備,無需繁瑣的許可程序。這些政策調整縮短了引進週期,並推動了主要城市走廊沿線新建和升級基地台的需求穩定成長。
行動數據使用量的增加給網路容量帶來了壓力。
2024年,影片串流、雲端遊戲和企業行動化的興起導致美國無線數據消耗量增加了36%。這迫使包括Crown Castle租戶在內的電信業者提高都市區的基地台密度,並擴大農村地區的覆蓋範圍。隨著價格親民的智慧型手機日益普及,新興市場也出現了類似的成長。儘管載波聚合和大規模MIMO等技術可以更有效地利用頻寬,但實體基礎設施仍然是瓶頸。因此,電信鐵塔市場仍在緩慢但穩定地擴張,營運商正依靠鐵塔公司來加速解決容量短缺問題。
共用基地台的飽和限制了成熟市場的成長潛力。
北美和西歐的託管費率仍維持在每座塔約2.7個租戶,限制了租賃收入的進一步成長。結構上的限制使得升級到更重的5G設備變得困難,需要花費大量資金來加固,進而對收入造成壓力。雖然新興市場獲取新租戶的前景仍然強勁,但成熟地區的市場飽和正在阻礙成長,全球電信鐵塔市場正朝著更平衡的擴張模式轉變。
細分市場分析
2025年,非可再生能源仍將主導電信鐵塔市場,佔據72.88%的市場佔有率,主要原因是大型基地台站的電網供電和柴油發電機。然而,隨著電信業者轉向太陽能-電池混合系統,大幅降低偏遠地區的營運成本,可再生能源正經歷最快成長,複合年成長率達5.22%。在電力供應不穩定且柴油燃料物流成本高的地區,可再生能源的採用尤其顯著。德國電信(Telefónica Germany)的能源自給自足型5G鐵塔證明了其在溫帶氣候下的可行性。混合系統也有助於減少碳排放,幫助基礎設施供應商滿足日益嚴格的ESG(環境、社會和治理)要求,並吸引綠色金融資本進入電信鐵塔市場。
領先的鐵塔公司目前正將「能源即服務 (EaaS)」合約打包出售,使行動通訊業者(MNO) 能夠將站點管理和電力管理外包。隨著智慧控制器和人工智慧驅動的電池分析技術最佳化能耗曲線,通訊鐵塔產業正從能源消費者轉變為本地能源生產者。這種轉變正在擴大盈利機會,實現收入來源多元化,並加強該行業在永續連接方面的作用。
2025年,格子形杆塔憑藉其組裝鋼結構,能夠以經濟的成本支撐重型多頻段有效載荷,維持了55.62%的市佔率。它們仍然是亞太地區和非洲廣闊農村地區廣域覆蓋的基礎。同時,單柱塔在都市區展現最高的成長率,複合年成長率達4.12%。其單柱結構減少了選址所需的空間,並加快了授權流程,避免了對景觀的影響。 2024年推出的碳纖維單柱塔,重量是鋼製單柱塔的12倍,抗張強度也是鋼製單柱塔的12倍,降低了運輸和基礎建設成本,並延長了資產的使用壽命。
隱形塔和拉線塔正在拓展我們的產品線。隱形塔符合歷史街區的規劃法規,而拉線塔則適用於土地資源密集地區的超高層建築。這些多樣化的設計方案結合,有助於通訊塔市場在不影響經濟效益的前提下,既滿足高密度都市區的需求,又能擴展對農村地區的通訊服務。
區域分析
亞太地區仍然是全球成長的驅動力。這主要得益於中國204萬個基地台的規模,以及印度雄心勃勃的5G目標——到2030年新增數十萬用戶。政府政策也提供了支持,例如在頻率競標中優先考慮網路覆蓋,並透過對農村地區的補貼來縮小商業可行性差距。在日本和韓國,將小型基地台堆疊在宏電網上的超高密度架構正日趨成熟;而在東南亞,人們正在探索鐵塔共用模式,以加快部署速度並控制成本。這些趨勢鞏固了亞太地區作為通訊鐵塔市場規模最大、成長最快的地區的地位。
北美地區已處於成熟且技術先進的階段。廣泛的資源共享限制了新建設,但5G升級和邊緣資料中心計劃正在支撐租賃需求。諸如「農村5G基金」等聯邦計畫正在解決人口稀少地區的經濟挑戰,並促進服務不足社區的逐步發展。地方政府層級出現了一些監管方面的阻力,例如分區規劃和景觀方面的異議可能會延誤專案進度,但聯邦政府的優先考慮正在縮小地方政府否決的空間。
歐洲的兩極化趨勢十分明顯。西歐市場面臨飽和和嚴格的環境法規,迫使鐵塔公司採取創新方法,例如可再生能源供電的基地台和採用符合環保法規的隱藏式設計。相較之下,東歐和巴爾幹半島尚處於5G部署的早期階段,頻譜競標和歐盟互聯互通基金支持待開發區項目,推動了全部區域的發展動能。同時,中東正經歷產業重組,鐵塔公司佔據了超過44%的市場佔有率,這得益於STC的「TAWAL」和Zain的「TASC」等平台的支持。拉丁美洲受惠於美洲移動在巴西77億美元的投資以及不斷擴大的5G頻譜競標。另一方面,非洲的長期潛力取決於政府的數位化計劃,這些計劃應結合衛星回程傳輸、農村補貼和普遍服務義務。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 5G網路部署
- 行動資料通訊和智慧型手機使用量的增加
- 農村地區的通訊基礎設施發展項目
- 行動網路業者將鐵塔資產貨幣化
- 對邊緣資料中心的託管需求
- 混合可再生能源系統的引入
- 市場限制因素
- 塔樓共用空間已飽和。
- 關於環境和土地利用區域的規定
- 高抗張強度鋼和複合材料的供應限制
- 低地球軌道衛星局部區域覆蓋的替代方案
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按燃料類型
- 可再生
- 不可可再生
- 塔式
- 格子形杆塔
- 分支型塔
- 單極塔
- 隱形塔
- 透過安裝
- 屋頂
- 地面以上
- 所有權
- 企業所有
- 合資
- 私人
- MNO專屬式
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞洲國家
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- American Tower Corporation
- Cellnex Telecom SA
- China Tower Corporation Limited
- SBA Communications Corporation
- Indus Towers Limited
- Helios Towers PLC
- IHS Holding Limited
- Vantage Towers AG
- Deutsche Funkturm GmbH
- TAWAL Company Ltd.
- Telxius Telecom SA
- Telesites SAB de CV
- AT&T Inc.
- T-Mobile US, Inc.
- GTL Infrastructure Limited
- Orange SA
- Telenor ASA
- PT Dayamitra Telekomunikasi Tbk(Mitratel)
- Ooredoo QPSC
- Zong Pakistan(CMPak Limited)
第7章 市場機會與未來展望
According to Mordor Intelligence, the telecom towers market size was valued at USD 29.29 billion in 2025 and estimated to grow from USD 30.07 billion in 2026 to reach USD 34.3 billion by 2031, at a CAGR of 2.67% during the forecast period (2026-2031).
This report is Segmented by Fuel Type (Renewable, Non-Renewable), Type of Tower (Lattice Tower, Guyed Tower, Monopole Tower, Stealth Tower), Installation (Rooftop, Ground-Based), Ownership (Operator-Owned, Joint Venture, Private-Owned, MNO Captive), and Geography (North America, Europe, Asia-Pacific, Middle East, Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Telecom Towers Market Trends and Insights
5G Network Rollouts Drive Infrastructure Densification
Operators must increase site density by three to five times compared with 4G to deliver 5G's low-latency targets, especially in high-band millimetre-wave spectrum. Latin America alone is expected to reach 425 million 5G connections by 2030, necessitating both traditional macro towers and growing layers of small cells. Regulatory bodies are responding: the Canadian Radio-television and Telecommunications Commission (CRTC) streamlined attachment rules so carriers can add 5G radios on existing structures without lengthy permissions. These policy shifts shorten deployment cycles and support consistent upward demand for new and upgraded tower sites across major urban corridors.
Rising Mobile Data Usage Pressures Network Capacity
U.S. wireless data consumption climbed 36% during 2024 as video streaming, cloud gaming, and enterprise mobility took hold, forcing carriers such as Crown Castle's tenants to densify urban footprints and expand rural coverage. Emerging markets mirror this surge as affordable smartphones proliferate. Techniques like carrier aggregation and massive-MIMO can stretch the spectrum, yet physical infrastructure remains the gating factor. As a result, the telecom towers market continues to exhibit incremental but durable expansion, with operators relying on tower companies to accelerate capacity meets.
Tower-Sharing Saturation Limits Mature-Market Upside
Co-location ratios in North America and Western Europe hover around 2.7 tenants per tower, leaving limited headroom for incremental leasing revenue. Structural limits complicate upgrades for heavier 5G equipment, prompting costly reinforcements that erode returns. While new tenancy pipelines remain healthy in emerging economies, saturation tempers growth in established regions, nudging the global telecom towers market toward a more balanced expansion profile.
Other drivers and restraints analyzed in the detailed report include:
- Rural Connectivity Programs Unlock New Market Opportunities
- MNO Tower-Asset Monetization Accelerates Industry Restructuring
- Environmental and Zoning Restrictions Complicate Deployment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-renewable sources dominated with 72.88% telecom towers market share in 2025, anchored by grid electricity and diesel generators for macro-cell sites. However, renewables deliver the fastest growth at a 5.22% CAGR as operators pivot to solar-battery hybrids that slash operating expense in remote areas. Renewable adoption is most pronounced in regions with erratic grid supply and high diesel logistics costs; Telefonica Germany's energy self-sufficient 5G tower demonstrates viability in temperate climates. Hybrid systems also curb carbon output, aligning infrastructure providers with tightening ESG mandates and drawing green-finance capital toward the telecom towers market.
Progressive tower companies now bundle energy-as-a-service contracts, allowing MNOs to outsource both site and power management. As smart controllers and AI-driven battery analytics optimize consumption curves, the telecom towers industry is transitioning from energy consumer to localized producer. That evolution widens margin opportunity, diversifies revenue, and reinforces the sector's role in sustainable connectivity.
Lattice towers retained a 55.62% share in 2025 because their triangulated-steel design supports heavy multi-band payloads at economical cost. They remain the backbone for wide-area coverage across rural expanses of Asia-Pacific and Africa. Monopoles, though, exhibit the highest growth at 4.12% CAGR in urban corridors. Their single-column form factors reduce right-of-way and skirt aesthetic objections, enabling faster permitting cycles. Carbon-fiber monopoles introduced in 2024 weigh one-twelfth of steel yet deliver twelve times the tensile strength, curbing transport and foundation expense while extending asset life.
Stealth and guyed variants round out the portfolio: stealth solutions satisfy zoning mandates in heritage districts, while guyed towers address ultra-tall applications where land is abundant. Collectively, diversified designs help the telecom towers market serve both densification and rural outreach targets without compromising economics.
Complete Report Scope:
- By Fuel Type
- Renewable
- Non-Renewable
- By Type of Tower
- Lattice Tower
- Guyed Tower
- Monopole Tower
- Stealth Tower
- By Installation
- Rooftop
- Ground-based
- By Ownership
- Operator-owned
- Joint Venture
- Private-owned
- MNO Captive
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific remains the engine of global growth, backed by China's 2.04 million-site footprint and India's aggressive 5G targets that will add hundreds of thousands of new tenancies by 2030. Government policy is supportive: spectrum auctions prioritize coverage, and rural subsidies narrow viability gaps. Japan and South Korea refine ultra-dense architectures that layer small cells onto macro grids, while Southeast Asian markets pursue tower-sharing frameworks to accelerate rollout and contain costs. These dynamics solidify Asia-Pacific's status as both the largest and fastest-growing slice of the telecom towers market.
North America presents a mature but technologically advanced landscape. Extensive co-location has tempered new-build volumes, yet 5G upgrades and edge-data-center initiatives sustain leasing demand. Federal programs such as the Rural 5G Fund bridge the economics of sparsely populated territories, steering incremental growth toward underserved communities. Regulatory headwinds arise at the municipal level, where zoning inertia and aesthetic opposition can extend project timelines, but federal pre-emption measures are narrowing the window for local vetoes.
Europe shows a two-speed pattern. Western markets face saturation and stringent environmental scrutiny, prompting tower companies to innovate with renewable-powered sites and stealth designs that satisfy eco-centric regulations. Eastern Europe and the Balkans, in contrast, are earlier in the 5G curve; spectrum auctions and EU connectivity funds support green-field construction that lifts overall regional momentum. Meanwhile, the Middle East advances consolidation, with TowerCo share surpassing 44% on the back of STC's TAWAL and Zain's TASC platforms. Latin America benefits from America Movil's USD 7.7 billion Brazil commitment and expanding 5G auctions, while Africa's long-term potential rests on government digitization plans that combine satellite backhaul, rural subsidies, and universal-service mandates.
- American Tower Corporation
- Cellnex Telecom S.A.
- China Tower Corporation Limited
- SBA Communications Corporation
- Indus Towers Limited
- Helios Towers PLC
- IHS Holding Limited
- Vantage Towers AG
- Deutsche Funkturm GmbH
- TAWAL Company Ltd.
- Telxius Telecom S.A.
- Telesites S.A.B. de C.V.
- AT&T Inc.
- T-Mobile US, Inc.
- GTL Infrastructure Limited
- Orange S.A.
- Telenor ASA
- PT Dayamitra Telekomunikasi Tbk (Mitratel)
- Ooredoo Q.P.S.C.
- Zong Pakistan (CMPak Limited)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G network roll-outs
- 4.2.2 Rising mobile data and smartphone usage
- 4.2.3 Rural connectivity programmes
- 4.2.4 MNO tower-asset monetisation
- 4.2.5 Edge data-centre co-location demand
- 4.2.6 Hybrid renewable power systems adoption
- 4.3 Market Restraints
- 4.3.1 Tower-sharing saturation
- 4.3.2 Environmental and zoning restrictions
- 4.3.3 High-strength steel and composite supply constraints
- 4.3.4 LEO-satellite rural coverage substitution
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Fuel Type
- 5.1.1 Renewable
- 5.1.2 Non-Renewable
- 5.2 By Type of Tower
- 5.2.1 Lattice Tower
- 5.2.2 Guyed Tower
- 5.2.3 Monopole Tower
- 5.2.4 Stealth Tower
- 5.3 By Installation
- 5.3.1 Rooftop
- 5.3.2 Ground-based
- 5.4 By Ownership
- 5.4.1 Operator-owned
- 5.4.2 Joint Venture
- 5.4.3 Private-owned
- 5.4.4 MNO Captive
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia
- 5.5.4 Middle East
- 5.5.4.1 Israel
- 5.5.4.2 Saudi Arabia
- 5.5.4.3 United Arab Emirates
- 5.5.4.4 Turkey
- 5.5.4.5 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Egypt
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 American Tower Corporation
- 6.4.2 Cellnex Telecom S.A.
- 6.4.3 China Tower Corporation Limited
- 6.4.4 SBA Communications Corporation
- 6.4.5 Indus Towers Limited
- 6.4.6 Helios Towers PLC
- 6.4.7 IHS Holding Limited
- 6.4.8 Vantage Towers AG
- 6.4.9 Deutsche Funkturm GmbH
- 6.4.10 TAWAL Company Ltd.
- 6.4.11 Telxius Telecom S.A.
- 6.4.12 Telesites S.A.B. de C.V.
- 6.4.13 AT&T Inc.
- 6.4.14 T-Mobile US, Inc.
- 6.4.15 GTL Infrastructure Limited
- 6.4.16 Orange S.A.
- 6.4.17 Telenor ASA
- 6.4.18 PT Dayamitra Telekomunikasi Tbk (Mitratel)
- 6.4.19 Ooredoo Q.P.S.C.
- 6.4.20 Zong Pakistan (CMPak Limited)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 美國電信塔:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)非洲電信塔及相關設備市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 通訊塔市場預測至2034年-按塔型、安裝方式、所有權方式、燃料類型、應用和地區分類的全球分析
 塔架管理軟體市場:依部署類型、塔架類型、最終用戶、功能和地區分類通訊塔市場:依部署方式、塔型、安裝方式、應用程式和區域分類
 通訊塔市場規模、佔有率、趨勢和預測:按塔型、燃料類型、安裝方式、所有權方式和地區分類,2026-2034 年
 隱蔽通訊塔市場規模、佔有率和成長分析:按偽裝設計/類型、塔架結構、頻率/頻段相容性、安裝位置和地區分類-2026-2033年產業預測
 行動電話基地台管理市場:依接取技術、塔型、安裝方式、服務類型、高度等級、組件類型及最終用戶產業分類-2026-2032年全球市場預測
 2026年全球數位雙胞胎市場報告
 2026-2030年全球電信塔市場