


 |
市場調查報告書
商品編碼
2124299
印度付款閘道:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)India Payment Gateway - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年印度付款閘道市場價值 20.7 億美元,預計到 2031 年將從 2026 年的 23.1 億美元成長至 40.1 億美元,預測期(2026-2031 年)的複合年成長率為 11.66%。
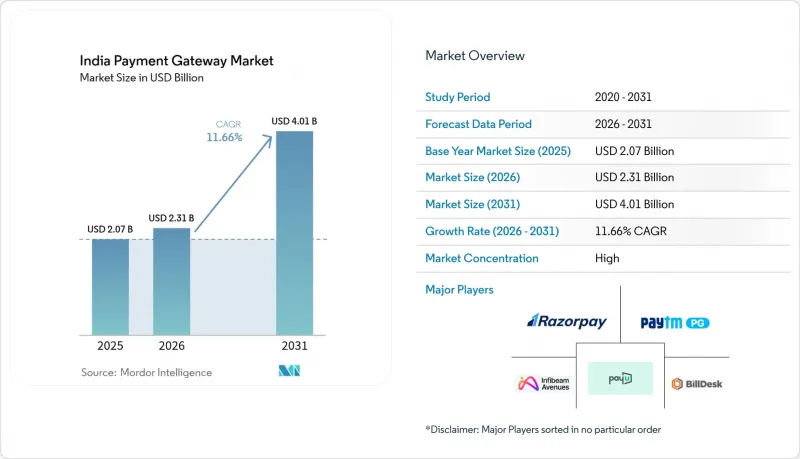
本報告按支付方式(UPI、銀行卡、電子錢包等)、公司規模(中小企業和大型企業)、部署類型(雲端、本地部署、混合部署)、終端用戶行業(零售/快速消費品、銀行、金融服務和保險以及金融科技平台、醫療保健/製藥、教育/教育科技等)和地區進行細分。市場預測以美元計價。
印度付款閘道市場的趨勢與洞察
UPI的爆炸性成長和國際擴張
光是2025年9月,UPI就將處理超過140億筆交易,約佔全球即時支付總量的50%。 UPI與PayNow等雙邊合作項目實現了不到一分鐘的跨境即時匯款至新加坡,並顯著降低了手續費,從而促進了與主要匯款服務商的閘道器合作。印度國家支付公司(NPCI)的「UPI Circle」功能允許主帳戶用戶將支付委託給最多五個子帳戶,從而將即時支付網路擴展到服務不足的群體和新的商家類別。
政府支持的數位公共基礎設施
API Setu託管著超過6000個運作中的政府API,DigiLocker支援4.3億用戶錢包。這建構了一個標準化的KYC層,將商家在支付閘道器的註冊週期縮短至幾分鐘。公共財政管理系統(PFMS)每月處理數十億筆撥款支付,並正在推動與認證閘道器的直接撥款工作流程進行大規模整合。
由於缺乏MDR,門戶網站面臨經濟壓力。
印度儲備銀行(RBI)強制規定統一支付介面(UPI)交易的商家折扣率(MDR)為零,這使得支付聚合商失去了傳統的基於交易額的收入來源。 2024年,私人付款閘道新創企業的資金籌措大幅縮減,迫使服務提供者優先發展以訂閱為基礎的分析服務、跨境收款和貸款夥伴關係,以維持營運。
細分市場分析
到2025年,UPI將佔據印度付款閘道市場63.85%的佔有率,其即時支付網路每年處理超過2,400億美元的交易。銀行卡仍將主導高價值零售消費,其中信用卡交易,尤其是與RuPay網路關聯的交易,將逐年翻倍。 「先買後付」(BNPL)與UPI的信貸功能和帳戶聚合數據管道緊密整合,預計將實現11.75%的複合年成長率,成為所有支付方式中成長率最高的。雖然網路銀行在透過NEFT和RTGS進行的企業大量支付中仍然發揮著重要作用,但隨著UPI互通性的日益普及,獨立電子錢包的使用正在下降。
隨著「UPI Circle」的推出,每個關聯用戶每月消費限額為15,000印度盧比,預計印度委託UPI支付的付款閘道市場將快速成長。同時,印度國家支付公司(NPCI)計劃將RuPay和Credit-on-UPI分拆為專門的子公司,這表明其策略重點在於建立一個能夠處理跨境資金流動的專業支付網路。
到2025年,大型企業將佔據印度付款閘道市場57.40%的佔有率,因為銀行、保險公司和跨國公司都在尋求多通路整合。然而,在ONDC標準化目錄、PIDF硬體補貼以及AA無紙化註冊的推動下,預計到2031年,中小企業(SME)的採用率將以12.58%的複合年成長率(CAGR)快速成長。 2024年初,隨著QR碼支付在第三線及以下城市普及,BharatPe的商家數量較上季成長了77%。
目前,中小企業的付款閘道正在整合匹配的儀錶板和即時支付功能,以應對營運資金挑戰。因此,預計印度雜貨店(Kirana stores)的混合雲端付款閘道市場佔有率將顯著成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務和D2C交易激增
- UPI的爆炸性成長和國際擴張
- 政府主導的數位公共基礎設施
- 促進微企業數位轉型的措施(PIDF、ONDC)
- API優先的開放金融和嵌入式支付
- UPI和BNPL的信貸業務快速成長
- 市場限制因素
- 零 MDR 帶來的經濟壓力和門戶影響
- RBI合規成本和PA許可成本正在增加。
- 詐欺、網路風險和系統宕機事件日益增多
- 主要UPI應用程式中的商家集中度
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素的影響
- 波特五力分析
第5章 市場規模與成長預測
- 透過付款方式
- UPI
- 卡片
- 網路銀行
- 錢包
- BNPL
- 按組織規模
- 小型企業
- 大公司
- 部署模式
- 基於雲端的
- 現場
- 混合
- 按最終用戶行業分類
- 電子商務市場
- 零售和快速消費品
- 銀行、金融服務與金融科技平台
- 醫療和藥品
- 教育和教育技術
- 旅遊與飯店
- 按地區
- 印度北部
- 西印度群島
- 南印度
- 印度東部和東北部
- 印度中部
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- PayU Payments Private Limited
- Razorpay Software Private Limited
- One 97 Communications Limited(Paytm Payments Gateway)
- CCAvenue-Infibeam Avenues Limited
- IndiaIdeas.com Limited(BillDesk)
- PayPal Payments Private Limited
- Instamojo Technologies Private Limited
- One MobiKwik Systems Limited
- Cashfree Payments India Private Limited
- Pine Labs Private Limited(Plural by Pine Labs)
- Stripe India Private Limited
- Worldline ePayments India Private Limited
- Google India Digital Services Private Limited(Google Pay for Merchants)
- Amazon Pay India Private Limited
- BharatPe(Resilient Innovations Private Limited)
- Juspay Technologies Private Limited
- PayG Solutions Private Limited
- Fiserv India Private Limited(IMSL-Fiserv)
- Adyen India Private Limited
- Payoneer India Private Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the India payment gateway market size was valued at USD 2.07 billion in 2025 and estimated to grow from USD 2.31 billion in 2026 to reach USD 4.01 billion by 2031, at a CAGR of 11.66% during the forecast period (2026-2031).
This report is Segmented by Payment Mode (UPI, Cards, Wallets, and More), Organization Size (Small and Medium Enterprises, and Large Enterprises), Deployment Mode (Cloud-Based, On-Premise, and Hybrid), End-User Industry (Retail and FMCG, BFSI and FinTech Platforms, Healthcare and Pharmaceuticals, Education and Ed-Tech, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
India Payment Gateway Market Trends and Insights
Explosive UPI Adoption and International Expansion
UPI processed more than 14 billion transactions in September 2025 alone, equal to roughly 50% of all real-time payments executed worldwide. Bilateral linkages such as UPI-PayNow enable instant cross-border transfers to Singapore at sub-minute settlement windows and materially lower fees, attracting gateway partnerships with major remittance providers. NPCI's "UPI Circle" feature now permits a primary user to delegate payments to up to five secondary profiles, extending real-time rails into underserved demographic cohorts and new merchant categories.
Government-Backed Digital Public Infrastructure
API Setu hosts more than 6,000 live government APIs, while DigiLocker supports 43 crore user wallets, creating standardized KYC layers that compress merchant onboarding cycles for gateways to a few minutes. The Public Financial Management System clears billions of subsidy payments monthly, pushing certified gateways to integrate at scale with direct benefit workflows.
Zero-MDR Economics Pressure on Gateways
The RBI-mandated zero-merchant discount rate for UPI transactions eliminates the traditional ad-valorem revenue line for payment aggregators. Funding to private payment gateway startups contracted sharply in 2024, forcing providers to prioritize subscription-based analytics, cross-border collections, and lending partnerships to remain solvent.
Other drivers and restraints analyzed in the detailed report include:
- MSME Digital Onboarding Incentives (PIDF, ONDC)
- API-First Open Finance and Embedded Payments
- Intensifying RBI Compliance and PA Licensing Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
UPI accounted for 63.85% of India payment gateway market share in 2025, clearing over 240 billion USD-equivalent annually via real-time rails. Cards continue to dominate high-value retail outlays, particularly credit cards linked to RuPay rails that have doubled transaction value year-on-year. Buy-now-pay-later, tightly coupled with credit-on-UPI and Account Aggregator data pipes, is projected to deliver a 11.75% CAGR, the fastest among all modes. Net-banking retains significance for corporate bulk disbursements through NEFT and RTGS, whereas standalone wallet usage is receding as UPI interoperability becomes ubiquitous.
The India payment gateway market size tied to delegated UPI payments is set to grow sharply because "UPI Circle" allows limits of INR 15,000 per linked user each month. Simultaneously, NPCI's plan to spin RuPay and Credit-on-UPI into dedicated subsidiaries signals a strategic focus on specialized rails that can accommodate cross-border flows.
Large organizations made up 57.40% of the India payment gateway market size in 2025 as banks, insurers, and multinationals sought multi-rail orchestration. However, SME adoption is surging at a forecast 12.58% CAGR through 2031, fuelled by ONDC's standardized catalogs, PIDF hardware subsidies, and AA-enabled zero-paper onboarding. BharatPe's merchant base grew 77% month-on-month in early 2024 as Tier-III and beyond cities embraced QR-based acceptance.
Payment gateways serving SMEs now bundle reconciliation dashboards and instant settlement to tackle working-capital pain points. The India payment gateway market share held by hybrid cloud dashboards catering to kirana stores is therefore expected to widen markedly.
Complete Report Scope:
- By Payment Mode
- UPI
- Cards
- Net-Banking
- Wallets
- BNPL
- By Organization Size
- Small and Medium Enterprises
- Large Enterprises
- By Deployment Mode
- Cloud-Based
- On-Premise
- Hybrid
- By End-User Industry
- E-Commerce and Marketplaces
- Retail and FMCG
- BFSI and FinTech Platforms
- Healthcare and Pharmaceuticals
- Education and Ed-Tech
- Travel and Hospitality
- By Region
- North India
- West India
- South India
- East and Northeast India
- Central India
List of Companies Covered in this Report:
- PayU Payments Private Limited
- Razorpay Software Private Limited
- One 97 Communications Limited (Paytm Payments Gateway)
- CCAvenue - Infibeam Avenues Limited
- IndiaIdeas.com Limited (BillDesk)
- PayPal Payments Private Limited
- Instamojo Technologies Private Limited
- One MobiKwik Systems Limited
- Cashfree Payments India Private Limited
- Pine Labs Private Limited (Plural by Pine Labs)
- Stripe India Private Limited
- Worldline ePayments India Private Limited
- Google India Digital Services Private Limited (Google Pay for Merchants)
- Amazon Pay India Private Limited
- BharatPe (Resilient Innovations Private Limited)
- Juspay Technologies Private Limited
- PayG Solutions Private Limited
- Fiserv India Private Limited (IMSL-Fiserv)
- Adyen India Private Limited
- Payoneer India Private Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in E-Commerce and D2C Transactions
- 4.2.2 Explosive UPI Adoption and International Expansion
- 4.2.3 Government-Backed Digital Public Infrastructure
- 4.2.4 MSME Digital On-Boarding Incentives (PIDF, ONDC)
- 4.2.5 API-First Open Finance and Embedded Payments
- 4.2.6 Rapid Growth of Credit-on-UPI and BNPL
- 4.3 Market Restraints
- 4.3.1 Zero-MDR Economics Pressure on Gateways
- 4.3.2 Intensifying RBI Compliance and PA Licensing Costs
- 4.3.3 Rising Fraud, Cyber-Risk and Outage Incidents
- 4.3.4 Merchant Concentration Among Top UPI Apps
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Payment Mode
- 5.1.1 UPI
- 5.1.2 Cards
- 5.1.3 Net-Banking
- 5.1.4 Wallets
- 5.1.5 BNPL
- 5.2 By Organization Size
- 5.2.1 Small and Medium Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Deployment Mode
- 5.3.1 Cloud-Based
- 5.3.2 On-Premise
- 5.3.3 Hybrid
- 5.4 By End-User Industry
- 5.4.1 E-Commerce and Marketplaces
- 5.4.2 Retail and FMCG
- 5.4.3 BFSI and FinTech Platforms
- 5.4.4 Healthcare and Pharmaceuticals
- 5.4.5 Education and Ed-Tech
- 5.4.6 Travel and Hospitality
- 5.5 By Region
- 5.5.1 North India
- 5.5.2 West India
- 5.5.3 South India
- 5.5.4 East and Northeast India
- 5.5.5 Central India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 PayU Payments Private Limited
- 6.4.2 Razorpay Software Private Limited
- 6.4.3 One 97 Communications Limited (Paytm Payments Gateway)
- 6.4.4 CCAvenue - Infibeam Avenues Limited
- 6.4.5 IndiaIdeas.com Limited (BillDesk)
- 6.4.6 PayPal Payments Private Limited
- 6.4.7 Instamojo Technologies Private Limited
- 6.4.8 One MobiKwik Systems Limited
- 6.4.9 Cashfree Payments India Private Limited
- 6.4.10 Pine Labs Private Limited (Plural by Pine Labs)
- 6.4.11 Stripe India Private Limited
- 6.4.12 Worldline ePayments India Private Limited
- 6.4.13 Google India Digital Services Private Limited (Google Pay for Merchants)
- 6.4.14 Amazon Pay India Private Limited
- 6.4.15 BharatPe (Resilient Innovations Private Limited)
- 6.4.16 Juspay Technologies Private Limited
- 6.4.17 PayG Solutions Private Limited
- 6.4.18 Fiserv India Private Limited (IMSL-Fiserv)
- 6.4.19 Adyen India Private Limited
- 6.4.20 Payoneer India Private Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 付款閘道:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 付款閘道市場:2026-2032年全球市場預測(付款閘道類型、支付方式、支付格式、部署類型、產業和組織規模分類)西班牙付款閘道:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026年全球收據式優惠市場報告中國付款閘道:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 付款閘道市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、最終用途、企業規模、地區和競爭格局分類,2021-2031 年
 付款閘道市場機會、成長要素、產業趨勢分析及2026-2035年預測
 付款閘道市場規模、佔有率和成長分析:按類型、企業規模、最終用戶和地區分類-2026-2033年產業預測
 付款閘道市場報告:按應用程式、互動方式和地區分類(2026-2034 年)
 付款閘道市場規模、佔有率和趨勢分析報告:按類型、企業規模、最終用途、地區和細分市場預測(2026-2033 年)