


 |
市場調查報告書
商品編碼
2124166
歐洲休閒車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Europe Recreational Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
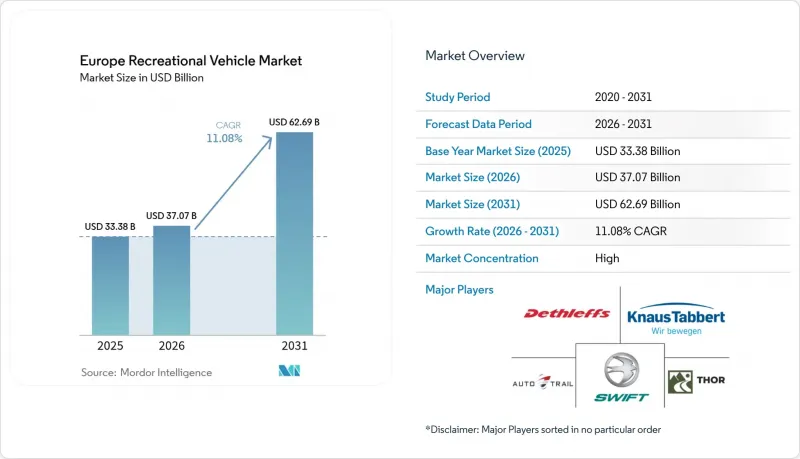
根據 Mordor Intelligence 預測,歐洲休閒車 (RV) 市場規模將從 2025 年的 333.8 億美元成長到 2026 年的 370.7 億美元,然後在 2031 年達到 626.9 億美元,2026 年至 2031 年的複合成長率為 11.08%。
本報告按類型(拖曳式房車、旅居車)、動力系統和燃料(柴油內燃機、汽油內燃機、混合動力、純電動)、所有權類型(個人車主、租賃和共享車隊)、銷售管道(OEM特許經銷商等)以及國家(德國、英國等)進行細分。市場預測以價值(美元)和銷售量(輛)表示。
歐洲休閒車市場的趨勢與洞察
疫情後,國內和歐洲內部旅遊業激增
歐洲的露營活動已達到前所未有的水平,預計到2024年,德國的露營夜數將達到4,290萬住宿,比疫情前的2019年成長19.9%。國內旅遊的持續成長反映了歐洲休閒偏好的根本性轉變,本地旅行已從疫情期間的必需品轉變為一種更受歡迎的生活方式選擇。這一趨勢並非德國獨有;挪威的住宿入住率也在上升,實現了顯著的同比成長。露營活動在2025年仍將保持高位,顯示這並非疫情期間的暫時性行為,而是一種結構性需求。尤其值得注意的是,與歷史水準相比,露營在德國住宿中所佔的比例大幅上升。旅遊業的這種結構性變化持續推動了房車需求的成長,涵蓋了從適合探索郊區的緊湊型露營車到適合長途國內旅行的大型旅居車等所有車型。
房車共享和租賃平台的快速擴張
歐洲房車共享生態系統正迅速成熟。 Roadsurfer 於 2025 年 4 月成功獲得 Avellinia Capital 3000 萬歐元的資金籌措,這充分體現了該行業的加速成長。 Roadsurfer 將主要利用這筆資金將其車隊規模從 8500 輛擴大到 10,000 輛。這項投資反映了機構投資者對 P2P(點對點)房車平台的認可,他們認知到 P2P 房車平台已經克服了最初的信任障礙,並且正在擴大規模。尤其值得注意的是該平台向東歐的擴張。 Ruuts 透過 API 整合瞄準東歐市場,透過在歐洲主要國家提供房車租賃服務,填補了先前服務不足的地區。共享經濟模式滲透到房車所有權模式中,正在產生兩種市場效應:一是讓首次使用者更容易獲得房車,二是為個人車主創造基於使用量的收入來源,從而有效地將潛在市場擴展到傳統所有權模式之外。
高昂的初始購買成本和保險成本
歐洲房車價格飆升,加重了所有細分市場的購車負擔。價格上漲源自於價值鏈中斷、底盤短缺以及製造商為因應疫情帶來的需求而漲價。由於需要特殊維修,不斷上漲的更換成本和保險費用進一步加劇了購車者的財務負擔。雖然中收入購車者擴大選擇二手車或租賃,但年輕購車者和首次購車者仍面臨許多准入門檻,儘管需求強勁,卻限制了市場成長。即使庫存有所調整,持續高企的價格仍然凸顯了結構性成本上漲,因此,提高收入和採用其他所有權模式對於維持房車市場至關重要。
細分市場分析
2025年,旅居車繼續保持其主導地位,佔據歐洲休閒車市場53.72%的佔有率。這反映出歐洲消費者偏好設施齊全、無需依賴外部服務的自主型行動居住解決方案。 55至75歲的富裕人群優先考慮舒適性和便利性,而非行動限制,支撐了房車市場的主導地位。同時,露營車預計將成為成長最快的車型,到2031年複合年成長率將達到11.62%,這主要得益於年輕一代對「房車生活」文化的追捧以及都市區白領對靈活工作旅行解決方案的需求。拖曳式房車和第五輪拖曳式房車佔據了一個規模較小但穩定的細分市場,受到那些希望擁有獨立牽引車用於日常使用的消費者的青睞。彈出式和折疊式露營車則構成了一個入門級市場,吸引對價格敏感的買家和季節性用戶。
法規環境也在推動這種細分市場的演變。歐盟2018/858號法規下的型式認證架構為多階段車輛認證提供了明確的路徑,既方便了露營車的改裝,又能確保安全標準。 A級旅居車價格較高,但受到都市區低排放氣體區法規的限制;而B級露營車則享有進入都市區更便利、停車更柔軟性的優勢。
到2025年,柴油內燃機(ICE)動力傳動系統將佔據歐洲休閒車市場91.10%的佔有率,這反映了該細分市場長期以來對柴油引擎卓越扭力特性和燃油效率的依賴,尤其是在重型車輛應用領域。汽油內燃機(ICE)車型的市佔率將保持相對較低,主要應用於輕型露營車,因為重量限制使得汽油引擎更為合適。然而,在歐盟更嚴格的排放氣體法規和不斷完善的充電基礎設施的推動下,電池式電動車(BEV)車型預計將在2031年之前以36.91%的複合年成長率快速成長。排放氣體則處於過渡階段,既能滿足關注續航里程的消費者的需求,又能減少都市區的排放。
挪威在電氣化轉型方面處於領先地位,純電動車(BEV)佔其乘用車市場的96%,這一趨勢正對商用車和休閒車領域產生連鎖反應。製造商們正大力投資電動解決方案,而Truma公司任命博世電氣解決方案部門的Joachim Weckwerth博士擔任產品開發負責人,則清晰地展現了其對電氣化的戰略承諾。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 疫情後,國內和歐洲內部旅遊業激增
- 房車共享和租賃平台的快速擴張
- 人口老化,特別是55歲至75歲富裕人群的老化,正在推動對高階產品的需求。
- 歐盟境內超過 3000 個露營地已升級至「互聯住宿」標準。
- 歐盟B類駕照的重量限制已提高到4.25噸,允許更大的樓層平面圖。
- 廂型車改裝的興起,讓數位遊牧者能夠「隨時隨地工作」。
- 市場限制因素
- 高昂的初始購買成本和保險成本
- 由於利率波動,資金籌措變得困難
- 2021-2022會計年度期間,因庫存過剩導致價格下降。
- 都市區的低排放區限制柴油房車通行。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 拖曳式房車
- 旅行拖車
- 第五輪拖車
- 彈出式/折疊式露營車
- 旅居車
- A級
- B級(露營車)
- C級
- 拖曳式房車
- 透過推進系統和燃料
- 柴油內燃機
- 汽油內燃機
- 油電混合
- 電池式電動車
- 自有車型
- 個人所有者
- 租賃和共享車輛
- 按銷售管道
- OEM/特許經銷商
- 直接在線上銷售給消費者
- 租車代理網路
- 國家
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 挪威
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Erwin Hymer Group(Thor Industries)
- Trigano SA
- Auto Trail VR LTD
- Knaus Tabbert AG
- Hobby-Fendt Caravan GmbH
- Swift Group Ltd.
- Rapido Group
- Adria Mobil doo
- Dethleffs GmbH & Co. KG
- Rimor Motorhomes
- Eura Mobil GmbH
- Burstner GmbH
- Laika Caravans SpA
- Westfalia Mobil GmbH
- Globe-Traveller RV Sp. z Oo
- Malibu GmbH & Co. KG
- Benimar SL
- Challenger(Trigano)
- Possl Group
- Pilote Groupe
According to Mordor Intelligence, the Europe recreational vehicle market size is expected to grow from USD 33.38 billion in 2025 to USD 37.07 billion in 2026 and is forecast to reach USD 62.69 billion by 2031 at 11.08% CAGR over 2026-2031.
This report is Segmented by Type (Towable RVs, Motorhomes), Propulsion and Fuel (Diesel ICE, Petrol ICE, Hybrid-Electric, Battery-Electric), Ownership Model (Private Owners, Rental and Sharing Fleets), Sales Channel (OEM-Franchised Dealers, and More), and Country (Germany, United Kingdom, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Europe Recreational Vehicle Market Trends and Insights
Post-pandemic Surge in Domestic and Intra-Europe Tourism
European camping activity has reached unprecedented levels, with Germany recording 42.9 million camping overnight stays in 2024, representing a 19.9% increase compared to 2019 pre-pandemic levels. This sustained elevation in domestic tourism reflects a fundamental shift in European leisure preferences, where proximity-based travel has evolved from pandemic necessity to preferred lifestyle choice. The trend extends beyond Germany, with Norway's camping sites witnessing a rise in guest nights, marking significant year-over-year growth. The persistence of elevated camping activity well into 2025 suggests this represents structural demand rather than temporary pandemic-driven behavior, particularly as camping accounts for most German guest overnight stays compared to historical levels. This tourism reorientation creates sustained tailwinds for RV demand across vehicle segments, from compact campervans enabling urban-adjacent exploration to larger motorhomes supporting extended domestic touring.
Rapid Expansion of RV-sharing and Rental Platforms
The European RV-sharing ecosystem has matured rapidly. The sector's growth acceleration is evidenced by Roadsurfer securing EUR 30 million from Avellinia Capital in April 2025, specifically for fleet expansion from 8,500 to 10,000 vehicles. This capital deployment reflects institutional recognition that peer-to-peer RV platforms have overcome initial trust barriers and achieved operational scale. Notably, platforms are expanding eastward, with Ruuts targeting Eastern European markets through API integrations, providing access to major European RVs, and addressing previously underserved regions. The sharing economy's penetration into RV ownership patterns creates dual market effects: democratizing access for first-time users while generating utilization-based revenue streams for private owners, effectively expanding the addressable market beyond traditional ownership models.
High Upfront Purchase and Insurance Costs
European RV prices have surged, straining affordability across market segments. This increase stems from supply chain disruptions, chassis shortages, and manufacturers leveraging pandemic-driven demand. Rising insurance premiums, driven by higher replacement values and specialized repair needs, add to the financial burden. Middle-market buyers increasingly opt for used vehicles or rentals, while younger and first-time buyers face barriers, limiting market growth despite strong demand. Even with inventory corrections, persistent high prices highlight structural cost inflation, necessitating income growth or alternative ownership models to sustain accessibility.
Other drivers and restraints analyzed in the detailed report include:
- Ageing but Affluent 55 to 75 Cohort Boosting Premium Demand
- EU B-license Weight Limit Rising to 4.25 t Enabling Larger Floorplans
- Volatile Interest-rate-driven Financing Squeeze
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Motorhomes maintained their dominant position with a 53.72% share of the Europe recreational vehicle market in 2025, reflecting European consumers' preference for self-contained mobile living solutions that provide comprehensive amenities without external dependencies. The segment's leadership stems from its appeal to the affluent 55-75 demographic, prioritizing comfort and convenience over mobility constraints. However, campervans are experiencing the fastest growth at 11.62% CAGR through 2031, driven by younger demographics embracing van life culture and urban professionals seeking flexible work-travel solutions. Travel and fifth-wheel trailers occupy smaller but stable niches, appealing to consumers who prefer to maintain separate towing vehicles for daily use. Pop-up and folding campers represent the entry-level segment, attracting price-sensitive buyers and seasonal users.
The regulatory environment supports this segmentation evolution, with EU type-approval frameworks under Regulation 2018/858 providing clear pathways for multi-stage vehicle approvals that facilitate campervan conversions while maintaining safety standards. Class A motorhomes command premium pricing but face headwinds from urban low-emission zone restrictions, while Class B campervans benefit from improved urban accessibility and parking flexibility.
Diesel ICE powertrains command 91.10% share of the Europe recreational vehicle market in 2025, reflecting the segment's traditional reliance on diesel's superior torque characteristics and fuel efficiency for heavy vehicle applications. Petrol ICE variants maintain a smaller presence, primarily in lighter campervan applications where weight considerations favor gasoline engines. However, battery-electric variants are surging at a 36.91% CAGR through 2031, driven by tightening EU emission regulations and expanding charging infrastructure. Hybrid-electric solutions occupy a transitional position, offering compromise solutions for range-anxious consumers while providing emission benefits for urban access.
Norway leads electric adoption with 96% BEV share in passenger cars, creating spillover effects into commercial and recreational vehicle segments. Manufacturers are investing heavily in electric solutions, with Truma appointing Dr. Joachim Weckwerth from Bosch's Electric Solutions division to lead product development, signaling a strategic commitment to electrification.
Complete Report Scope:
- By Type
- Towable RVs
- Travel Trailers
- Fifth-Wheel Trailers
- Pop-up/Folding Campers
- Motorhomes
- Class A
- Class B (Campervans)
- Class C
- Towable RVs
- By Propulsion and Fuel
- Diesel Internal Combustion Engine
- Petrol Internal Combustion Engine
- Hybrid-Electric
- Battery-Electric
- By Ownership Model
- Private Owners
- Rental and Sharing Fleets
- By Sales Channel
- OEM-Franchised Dealers
- Direct-to-Consumer Online
- Rental Agency Networks
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Norway
- Rest of Europe
List of Companies Covered in this Report:
- Erwin Hymer Group (Thor Industries)
- Trigano SA
- Auto Trail VR LTD
- Knaus Tabbert AG
- Hobby-Fendt Caravan GmbH
- Swift Group Ltd.
- Rapido Group
- Adria Mobil d.o.o.
- Dethleffs GmbH & Co. KG
- Rimor Motorhomes
- Eura Mobil GmbH
- Burstner GmbH
- Laika Caravans S.p.A.
- Westfalia Mobil GmbH
- Globe-Traveller RV Sp. z O.o.
- Malibu GmbH & Co. KG
- Benimar SL
- Challenger (Trigano)
- Possl Group
- Pilote Groupe
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-Pandemic Surge In Domestic And Intra-Europe Tourism
- 4.2.2 Rapid Expansion Of RV-Sharing And Rental Platforms
- 4.2.3 Ageing But Affluent 55 to 75 Cohort Boosting Premium Demand
- 4.2.4 Upgrade Of More Than 3,000 EU Campsites To "Connected-Stay" Standards
- 4.2.5 EU B-License Weight Limit Rising To 4.25 t Enabling Larger Floorplans
- 4.2.6 Emergence Of "Work-From-Anywhere" Digital-Nomad Van Conversions
- 4.3 Market Restraints
- 4.3.1 High Upfront Purchase And Insurance Costs
- 4.3.2 Volatile Interest-Rate-Driven Financing Squeeze
- 4.3.3 Oversupply-Led Price Depreciation Of 2021-22 Inventory
- 4.3.4 Urban Low-Emission Zones Curbing Diesel RV Access
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecast (Value (USD) and Volume (Units))
- 5.1 By Type
- 5.1.1 Towable RVs
- 5.1.1.1 Travel Trailers
- 5.1.1.2 Fifth-Wheel Trailers
- 5.1.1.3 Pop-up/Folding Campers
- 5.1.2 Motorhomes
- 5.1.2.1 Class A
- 5.1.2.2 Class B (Campervans)
- 5.1.2.3 Class C
- 5.1.1 Towable RVs
- 5.2 By Propulsion and Fuel
- 5.2.1 Diesel Internal Combustion Engine
- 5.2.2 Petrol Internal Combustion Engine
- 5.2.3 Hybrid-Electric
- 5.2.4 Battery-Electric
- 5.3 By Ownership Model
- 5.3.1 Private Owners
- 5.3.2 Rental and Sharing Fleets
- 5.4 By Sales Channel
- 5.4.1 OEM-Franchised Dealers
- 5.4.2 Direct-to-Consumer Online
- 5.4.3 Rental Agency Networks
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Norway
- 5.5.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Erwin Hymer Group (Thor Industries)
- 6.4.2 Trigano SA
- 6.4.3 Auto Trail VR LTD
- 6.4.4 Knaus Tabbert AG
- 6.4.5 Hobby-Fendt Caravan GmbH
- 6.4.6 Swift Group Ltd.
- 6.4.7 Rapido Group
- 6.4.8 Adria Mobil d.o.o.
- 6.4.9 Dethleffs GmbH & Co. KG
- 6.4.10 Rimor Motorhomes
- 6.4.11 Eura Mobil GmbH
- 6.4.12 Burstner GmbH
- 6.4.13 Laika Caravans S.p.A.
- 6.4.14 Westfalia Mobil GmbH
- 6.4.15 Globe-Traveller RV Sp. z O.o.
- 6.4.16 Malibu GmbH & Co. KG
- 6.4.17 Benimar SL
- 6.4.18 Challenger (Trigano)
- 6.4.19 Possl Group
- 6.4.20 Pilote Groupe

 拖曳式房車市場:全球市場預測,2026-2032年
 北美休閒車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)休閒車市場-2026-2032年全球市場預測
 2026-2030年全球休閒車(RV)市場
 休閒車市場規模、佔有率和成長分析(按地區分類)-2026-2033年產業預測
 全球休閒車市場:依類型、應用和地區劃分 - 市場規模、行業趨勢、機會分析和預測(2025-2033 年)
 休閒車複合板的全球市場。
 2025-2029年全球休閒車(RV)租賃市場
 2030 年休閒車市場預測:按車輛類型、燃料類型、價格分佈、應用、最終用戶和地區進行的全球分析
 全球休閒車 (RV) 市場:按產品類型、按組件、按 RV 外觀、按 RV 內飾、按生活方式配件、按應用、按地區、範圍和預測