


 |
市場調查報告書
商品編碼
2121216
北美休閒車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)North America Recreational Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年北美休閒車市值為 217.7 億美元,預計到 2031 年將達到 350.3 億美元,而 2026 年為 235.7 億美元,預測期(2026-2031 年)的複合年成長率為 8.25%。
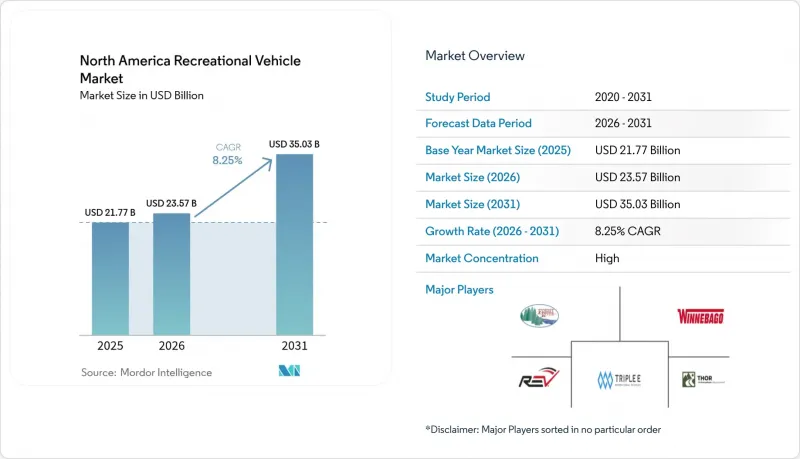
本報告按類型(拖掛式房車和旅居車)、用途(個人和商業)、燃料類型(汽油、柴油、混合動力和純電動)、配銷通路(新車和二手車銷售)以及地區(美國、加拿大和其他北美國家)進行分類。市場預測以貨幣價值(美元)和銷售(輛)兩種形式呈現。
北美休閒車市場趨勢與洞察
房車電氣化和混合動力車型的成長
電池式電動車和混合動力傳動系統代表了北美休閒車市場目前正在發生的最具突破性的產品變化。 Thor Industries公司推出了一款A級混合動力房車,配備140度電池組和汽油增程器,總續航里程可達500英里。這種設計不僅消除了續航里程的擔憂,也滿足了新推出的低排放氣體法規的要求。電力扭力提升了爬坡能力,而更安靜的駕駛體驗則增強了露營舒適度。製造商正透過將高容量電池組與車頂太陽能板結合,強調其離網功能,使其在停放時也能作為住宅電源使用。這種永續性訊息與Thor自2019年以來在範圍1和範圍2排放方面取得的減排成果相一致,進一步提升了該品牌對環保意識強的消費者的吸引力。隨著充電基礎設施的不斷完善,擁有電動房車的門檻也持續降低。
新冠疫情後國內自駕遊旅遊增加
即使邊境限制放寬,國內公路旅行仍然是比國際旅行更受歡迎的選擇。大約有810萬美國家庭擁有房車,預計未來五年這一數字將達到1690萬。房車的年均使用天數已從2021年的20天激增至2025年的30天,顯示房車已進一步融入人們的生活方式。目前50歲以下的年輕一代是新購屋者的主要驅動力,支撐著持續的長期更換需求。消費者對品牌的忠誠度很高,超過80%的疫情期間購車者表示有意再次購買同一品牌,這為主要汽車製造商帶來了可預測的重複銷售。即使旅遊業整體正在恢復正常,人們對在地化體驗和社交距離的偏好休閒了持續的需求。
燃油價格波動推高了行程成本。
預計到2023年,美國平均汽油價格將下降20美分,至2024年的每加侖3.30美元。 A級旅居車每行駛6-10英里消耗1加侖汽油,這意味著為期兩週的旅行需要1000美元的燃油費用,因此旅行決策極易受到汽油價格波動的影響。柴油車的價格波動模式與汽油車不同,這使得商用車預算更加複雜。持續高昂的成本促使消費者重新關注燃油效率高的混合動力系統和輕質複合材料。電氣化提供了一種結構性風險對沖方案,但由於需要投資建設充電基礎設施,預計其廣泛普及還需要數年時間。
細分市場分析
預計到2025年,拖曳式房車將佔北美休閒車市場的63.52%。同時,旅居車預計將以12.93%的複合年成長率成長,成為北美休閒車市場的主要成長引擎。高階A型車型擁有住宅般的內裝、拓展艙和混合動力傳動系統,可減少排放氣體並延長續航里程。 B型露營車的目標客群是注重操控性和隱密露營的都市區白領。 C型車型則兼顧價格和生活空間,更受家庭青睞。製造商正在採用模組化生產模式,以實現不同車型之間的靈活生產,滿足多樣化的需求,同時保持規模經濟效益。
由於購置成本較低且皮卡拖曳式房車普及,拖曳式房車仍佔據重要地位。旅行拖車憑藉其多樣化的佈局和經濟實惠的維護成本,在該類別中脫穎而出。第五輪拖曳式房車則採用多層佈局,並配備住宅,適合季節性「候鳥式」旅行。折疊式露營拖車和皮卡車露營車分別迎合入門預算市場和越野利基市場。這種多樣性使得拖曳式房車的銷售量保持強勁,即便富裕消費者正轉向自走式車輛。
到2025年,個人用途將佔北美休閒車市場佔有率的69.48%,這反映了該細分市場的休閒用途起源。同時,預計到2031年,商業用途將以9.22%的複合年成長率成長,成長率高於北美休閒車市場的整體成長速度。企業正在使用客製化房車作為移動指揮中心、臨時展示室或偏遠專案的員工臨時住宿設施。醫療機構正在利用自主型的診所將服務範圍擴展到農村地區。飯店公司正在為其設施配備豪華房車,以提供價格不菲的豪華露營體驗。
隨著商務旅行和休閒旅行之間的界線日益模糊,兩用車輛越來越普遍,車主可以將支出分為個人預算和商用預算。某些州提供的稅收優惠進一步促進了商用車輛的普及。如今,汽車製造商提供休閒安裝的辦公艙、衛星通訊功能和發電機組,以滿足企業的特定需求。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 房車電氣化和混合動力車型的成長
- 新冠疫情後國內自駕遊旅遊增加
- 遠距辦公的普及使長期房車生活成為現實。
- 透過先進的連結性和物聯網技術提升使用者體驗
- 房車共享P2P平台的擴展
- 州政府對房車所有權的稅收優惠
- 市場限制因素
- 燃油價格波動導致運輸成本上升
- 利率上升對資金籌措能力的影響
- 由於露營地容量不足,使用受到限制
- 房車租賃平台激增
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 拖曳式房車
- 旅行拖車
- 第五輪拖車
- 折疊式露營拖車
- 卡車露營車
- 旅居車
- A型
- B型
- C型
- 拖曳式房車
- 透過使用
- 個人
- 商業的
- 按燃料類型
- 汽油
- 柴油引擎
- 混合
- 電池供電
- 透過分銷管道
- 新房車銷售
- 二手房車銷售
- 國家
- 美國
- 加拿大
- 其他北方
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Thor Industries Inc.
- Forest River Inc.
- Winnebago Industries Inc.
- REV Group
- Tiffin Motorhomes Inc.
- Entegra Coach Inc.
- NeXus RV
- Cruiser RV
- Triple E Recreational Vehicles
- Newmar Corporation
- Jayco Inc.
- Airstream Inc.
- Lance Camper Manufacturing Corp.
- Pleasure-Way Industries
- Keystone RV Company
- Coachmen RV
- Grand Design RV
- Roadtrek Inc.
- Fleetwood RV
- Holiday Rambler
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America rV market size was valued at USD 21.77 billion in 2025 and estimated to grow from USD 23.57 billion in 2026 to reach USD 35.03 billion by 2031, at a CAGR of 8.25% during the forecast period (2026-2031).
This report is Segmented by Type (Towable RVs and Motorhomes), Application (Private and Commercial), Fuel Type (Gasoline, Diesel, Hybrid, and Battery-Electric), Sales Channel (New RV Sales and Used RV Sales), and Geography (United States, Canada, and Rest of North America). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
North America Recreational Vehicle Market Trends and Insights
Growth in Electrified & Hybrid RV Models
Battery-electric and hybrid powertrains represent the most disruptive product shift underway in the North America recreational vehicle market. Thor Industries unveiled a hybrid Class A coach featuring a 140-kWh battery pack and a gasoline range extender that delivers a 500-mile total range. The design answers range anxiety and qualifies for emerging low-emission regulations. Electric torque improves hill-climbing performance, while silent operation raises campsite comfort. Manufacturers highlight off-grid capability by pairing large battery packs with roof solar arrays, enabling auxiliary power for residential needs when parked. Sustainability messaging aligns with the Scope 1 and 2 emissions cut Thor achieved since 2019, sharpening brand appeal to eco-conscious buyers. As charging infrastructure grows, electric RV ownership barriers continue to fall.
Increased Domestic Road-Trip Tourism Post-COVID
Domestic road travel remains the preferred alternative to international trips even after border restrictions eased. Approximately 8.1 million American households own an RV, and 16.9 million are expected to own an RV in the coming five years. Average annual usage days jumped from 20 in 2021 to 30 in 2025, signaling deeper lifestyle integration. Younger cohorts under 50 now dominate new purchases, reinforcing a long replacement-demand runway. With high brand loyalty, more than 80% of pandemic-era buyers intend to repurchase the same marque, which creates predictable repeat sales for leading OEMs. The shift toward localized experiences and socially distanced recreation underpins persistent demand even as broader tourism normalizes.
Volatile Fuel Prices Increasing Trip Costs
Average U.S. gasoline prices averaged USD 3.30 per gallon in 2024, down 20 cents from 2023. Class A motorhomes consume 1 gallon every 6-10 miles, so a two-week tour can require USD 1,000 in fuel, making travel decisions sensitive to pump swings. Diesel variants face separate volatility patterns that complicate budgeting for commercial fleets. Persistently high costs have revived consumer interest in hybrid drivetrains and lighter composite materials that improve mileage. Electrification provides a structural hedge but will take years to scale due to charging-site investments.
Other drivers and restraints analyzed in the detailed report include:
- Rising Popularity of Remote Work Enabling Long-Term RV Living
- Advanced Connectivity & IoT Enhancing User Experience
- Rising Interest Rates Impacting Financing Affordability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Towable RVs held 63.52% of the North American Recreational Vehicle market share in 2025, while Motorhomes are forecast to log a 12.93% CAGR, positioning it as the principal growth engine for the North America RV market. Premium Type A models add residential finishes, slide-outs, and hybrid powertrains that reduce emissions and extend range. Type B camper vans target urban professionals who value maneuverability and stealth camping. Type C units balance price and livable space, widening appeal to families. Manufacturers deploy modular production that flexes between classes, preserving scale advantages while accommodating varied demand.
Towables retain relevance due to lower acquisition costs and the widespread availability of pickup trucks capable of towing. Travel trailers lead the category thanks to versatile floorplans and modest maintenance needs. Fifth-wheels add multi-level layouts and residential appliances suited for seasonal snowbird migration. Folding campers and truck campers serve entry-level budgets and off-road niches, respectively. This diversity keeps towable volume robust even as affluent cohorts shift into motorized products.
Private use captured 69.48% of the North American Recreational Vehicle market share in 2025, reflecting the recreational origins of the sector. Commercial usage, however, is forecast to compound at a 9.22% CAGR through 2031, outpacing the overall North America RV market size. Corporations deploy customized RVs as mobile command centers, pop-up showrooms, or temporary workforce housing on remote projects. Healthcare systems leverage self-contained clinics to expand rural reach. Hospitality firms outfit luxury units for glamping sites that command premium nightly rates.
The blurring of business and leisure travel fuels dual-use purchasing, allowing owners to classify expenses across personal and professional budgets. Tax advantages available in certain states further encourage commercial fleet formation. OEMs now offer factory-installed office pods, satellite connectivity, and generator packages that meet enterprise specifications.
Complete Report Scope:
- By Type
- Towable RVs
- Travel Trailers
- Fifth Wheel Trailers
- Folding Camp Trailers
- Truck Campers
- Motorhomes
- Type A
- Type B
- Type C
- Towable RVs
- By Application
- Private
- Commercial
- By Fuel Type
- Gasoline
- Diesel
- Hybrid
- Battery-Electric
- By Sales Channel
- New RV Sales
- Used RV Sales
- By Country
- United States
- Canada
- Rest of North America
List of Companies Covered in this Report:
- Thor Industries Inc.
- Forest River Inc.
- Winnebago Industries Inc.
- REV Group
- Tiffin Motorhomes Inc.
- Entegra Coach Inc.
- NeXus RV
- Cruiser RV
- Triple E Recreational Vehicles
- Newmar Corporation
- Jayco Inc.
- Airstream Inc.
- Lance Camper Manufacturing Corp.
- Pleasure-Way Industries
- Keystone RV Company
- Coachmen RV
- Grand Design RV
- Roadtrek Inc.
- Fleetwood RV
- Holiday Rambler
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth In Electrified and Hybrid RV Models
- 4.2.2 Increased Domestic Road-Trip Tourism Post-COVID
- 4.2.3 Rising Popularity Of Remote Work Enabling Long-Term RV Living
- 4.2.4 Advanced Connectivity and IoT Enhancing User Experience
- 4.2.5 Expansion Of RV-Sharing Peer-To-Peer Platforms
- 4.2.6 Favorable State Tax Incentives For Motorhome Ownership
- 4.3 Market Restraints
- 4.3.1 Volatile Fuel Prices Increasing Trip Costs
- 4.3.2 Rising Interest Rates Impacting Financing Affordability
- 4.3.3 Campground Capacity Shortages Limiting Usage
- 4.3.4 Proliferation Of RV Rental Platforms
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Type
- 5.1.1 Towable RVs
- 5.1.1.1 Travel Trailers
- 5.1.1.2 Fifth Wheel Trailers
- 5.1.1.3 Folding Camp Trailers
- 5.1.1.4 Truck Campers
- 5.1.2 Motorhomes
- 5.1.2.1 Type A
- 5.1.2.2 Type B
- 5.1.2.3 Type C
- 5.1.1 Towable RVs
- 5.2 By Application
- 5.2.1 Private
- 5.2.2 Commercial
- 5.3 By Fuel Type
- 5.3.1 Gasoline
- 5.3.2 Diesel
- 5.3.3 Hybrid
- 5.3.4 Battery-Electric
- 5.4 By Sales Channel
- 5.4.1 New RV Sales
- 5.4.2 Used RV Sales
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Rest of North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Thor Industries Inc.
- 6.4.2 Forest River Inc.
- 6.4.3 Winnebago Industries Inc.
- 6.4.4 REV Group
- 6.4.5 Tiffin Motorhomes Inc.
- 6.4.6 Entegra Coach Inc.
- 6.4.7 NeXus RV
- 6.4.8 Cruiser RV
- 6.4.9 Triple E Recreational Vehicles
- 6.4.10 Newmar Corporation
- 6.4.11 Jayco Inc.
- 6.4.12 Airstream Inc.
- 6.4.13 Lance Camper Manufacturing Corp.
- 6.4.14 Pleasure-Way Industries
- 6.4.15 Keystone RV Company
- 6.4.16 Coachmen RV
- 6.4.17 Grand Design RV
- 6.4.18 Roadtrek Inc.
- 6.4.19 Fleetwood RV
- 6.4.20 Holiday Rambler
7 Market Opportunities and Future Outlook
- 7.1 Autonomous RVs to transform caravanning experience
- 7.2 Subscription-based RV ownership models

 拖曳式房車市場:全球市場預測,2026-2032年
 歐洲休閒車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)休閒車市場-2026-2032年全球市場預測
 2026-2030年全球休閒車(RV)市場
 休閒車市場規模、佔有率和成長分析(按地區分類)-2026-2033年產業預測
 全球休閒車市場:依類型、應用和地區劃分 - 市場規模、行業趨勢、機會分析和預測(2025-2033 年)
 休閒車複合板的全球市場。
 2025-2029年全球休閒車(RV)租賃市場
 2030 年休閒車市場預測:按車輛類型、燃料類型、價格分佈、應用、最終用戶和地區進行的全球分析
 全球休閒車 (RV) 市場:按產品類型、按組件、按 RV 外觀、按 RV 內飾、按生活方式配件、按應用、按地區、範圍和預測