


 |
市場調查報告書
商品編碼
2124122
浮法玻璃:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Float Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,預計到 2026 年,浮法玻璃市場將達到 7,686 萬噸,高於 2025 年的 7,427 萬噸,預計到 2031 年將達到 9,118 萬噸。
預計 2026 年至 2031 年的複合年成長率為 3.48%。
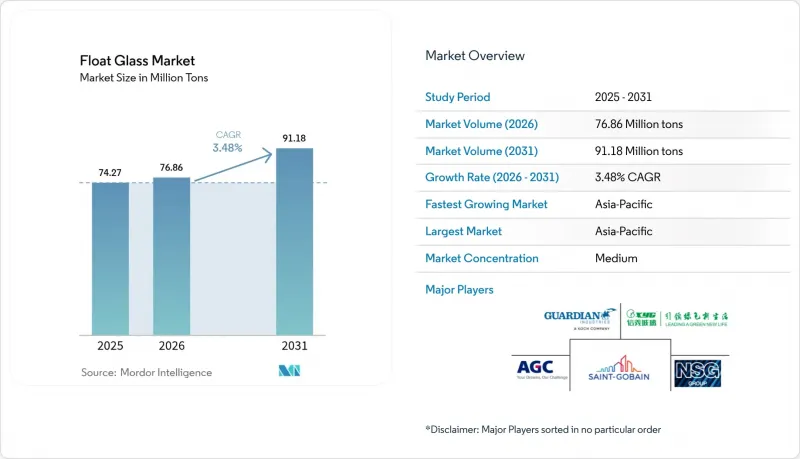
本報告按產品類型(透明、彩色、圖案、帶網紋、超白/低鐵)、應用領域(建築、汽車、太陽能玻璃及其他應用)和地區(亞太、北美、歐洲、南美以及中東和非洲)進行細分。市場預測以噸為單位。
全球浮法玻璃市場趨勢及洞察
新興經濟體建築業的擴張
南亞和東南亞地區公共部門在交通、住宅和工業走廊建設方面的堅定投入,正推動著建築玻璃的持續成長。印度的建築項目儲備相當於該行業年營業收入的3.5倍。儘管由於人手不足導致工程運轉率放緩,泰國東部經濟走廊對浮法玻璃的需求依然強勁。由於區域內浮法玻璃生產線的產能利用率已低於80%,位於這些需求中心附近的製造商無需新增投資即可迅速擴大出貨量。因此,浮法玻璃市場將依靠快速成長的新興經濟體來彌補成熟西方國家消費停滯的情況。
車輛重量的減輕導致每輛車使用的玻璃面積增加。
隨著電氣化成為必然趨勢,車重已成為汽車製造商的關鍵績效指標 (KPI),而高級駕駛輔助系統 (ADAS)、全景天窗和身臨其境型資訊娛樂螢幕的普及卻增加了每輛車的玻璃表面積。這種矛盾的局面正在推動浮法玻璃市場的結構性成長,因為汽車製造商 (OEM) 要求使用更薄、更大尺寸的夾層玻璃和鋼化玻璃,並整合天線、加熱器和抬頭顯示器(HUD) 的塗層。福耀玻璃決定投資 58 億元人民幣(約 8.04 億美元)新建一條專門用於電動汽車平臺的浮法玻璃生產線,充分展現了這一市場機會的巨大規模。由此產生的對光學清晰度和電磁波滲透性的需求,使得高價策略成為合理,確保銷售量成長能夠直接轉化為技術先進供應商的收入和利潤率的提升。
安全玻璃中的聚合物和聚碳酸酯替代品
汽車和建築規範現已認可聚碳酸酯解決方案,該方案可在保持與夾層玻璃相當的抗衝擊性的同時,將重量減輕 40-50%。因此,優先考慮減重的原始設備製造商 (OEM) 正在探索使用聚合物車頂和後窗。然而,耐刮擦性、紫外線穩定性和光學畸變等挑戰限制了其應用範圍,使其僅限於小眾領域。作為回應,玻璃製造商(例如伊士曼公司在歐洲不斷擴大的產能)正在提案使用先進 PVB 中間層的更薄更輕的夾層玻璃。這種材料競爭抑制了浮法玻璃市場的複合年成長率 (CAGR),同時也刺激了創新,拓寬了產品應用範圍,並提高了市場進入門檻。
細分市場分析
到2025年,透明平板玻璃將佔據浮法玻璃市場62.70%的佔有率,預計到2031年將以3.79%的複合年成長率保持最高成長率。這種壓倒性的市場主導地位反映了其無與倫比的多功能性,因為透明玻璃能夠滿足彩色或圖案玻璃無法達到的透明度要求,例如在幕牆玻璃、汽車擋風玻璃和低鐵太陽能蓋板等領域。製造商正加大研發投入,致力於改進精煉和熔體均質化技術,以抑制氣泡和鐵殘留,從而確保利潤率,抵消商品化帶來的不利影響。彩色和圖案玻璃作為設計主導的小眾市場仍然存在,但其市場成長更多地受到建築潮流週期性波動的影響,而非結構技術創新。
超白、低鐵等級的玻璃在高階市場佔據主導地位,這得益於太陽能發電熱潮帶來的經濟效益以及高階建築外觀的美學吸引力。 NSG 的「Pilkington Mirai™」和信義的 2.0 毫米玻璃產品線清晰地展現了其在降低碳含量和實現超薄玻璃方面的雙重目標。隨著 N 型太陽能組件陸續進入生產線,玻璃缺陷率不斷上升,但矛盾的是,每吉瓦裝置容量所需的透明玻璃量卻在增加。因此,整合式砂礦和即時雜質掃描儀正成為浮法玻璃市場的重要競爭優勢。
區域分析
亞太地區主導浮法玻璃市場,預計到2025年將佔全球產量的62.65%,並在2031年之前以3.92%的複合年成長率持續成長。中國憑藉其大型窯爐群支撐著市場,而印度則正經歷前所未有的1.5兆美元建設熱潮,住宅大樓和物流園區對玻璃的需求量龐大。泰國東部經濟走廊周邊的基礎設施投資緩解了住宅市場放緩而導致的區域需求下降。然而,亞洲出口商正被迫應對飆升的運費和即將實施的碳邊境調節措施(CBAM)課稅,這促使他們嘗試投資混合式熔爐和屋頂太陽能發電系統,以減少每噸玻璃的二氧化碳排放量。
歐洲歷來是浮法玻璃創新的發源地,如今已成為低碳製造的標竿。聖戈班的ORAE系列產品採用高比例的再生材料,並獲得「從搖籃到搖籃」(C2C)認證;而AGC Interpane則透過在德國和奧地利升級設備,在住宅開工緩慢的情況下提升生產線效率。
在北美,福耀利用近岸外包趨勢和清潔能源獎勵,投資4億美元在伊利諾州興建浮法玻璃廠,確保其位於中西部的電動車工廠能及時獲得原料供應。加上《通貨膨脹控制法案》提供的製造業稅額扣抵,這些舉措正推動著玻璃生產方式從依賴進口轉向國產熔融玻璃,從而縮短前置作業時間並減少碳排放。在南美洲、中東和非洲,隨著體育場館建設、海水淡化項目和智慧城市建設的推出,玻璃產量正在逐步成長,但由於當地產能有限,人均消費量仍低於成熟市場標準。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新興國家建築業的擴張
- 由於車輛重量減輕,每輛車的玻璃面積(平方公尺)增加。
- 大型太陽能發電廠的建設正在推動對低鐵浮法玻璃的需求。
- 節能型外觀對於都市更新至關重要。
- BIPV幕牆法規正在推動超高透明度、低鐵基板的應用。
- 市場限制因素
- 堿灰和天然氣的價格波動
- 安全玻璃中的聚合物和聚碳酸酯替代材料
- 與歐盟碳邊境調節機制相關的合規成本(這一點一直被忽視)
- 價值鏈分析
- 原料分析
- 沙
- 石灰岩
- 堿灰
- 白雲石
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 清除
- 染色
- 圖案
- 有線
- 超白/低鐵浮法玻璃
- 透過使用
- 建築/施工
- 車
- 太陽能玻璃
- 其他用途
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 越南
- 泰國
- 印尼
- 馬來西亞
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 奈及利亞
- 卡達
- 阿拉伯聯合大公國
- 埃及
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- AGC Inc.
- BG
- CARDINAL GLASS INDUSTRIES, INC
- China Glass Holding
- China Luoyang Float Glass Group Co., Ltd.
- Flat Glass Group Co., Ltd
- Fuyao Group
- Guardian Industries Holdings
- Kibing Group
- Nippon Sheet Glass Co., Ltd
- PRESS GLASS Holding SA
- PT Mulia Industrindo Tbk
- Saint-Gobain
- SCHOTT
- Sisecam
- Taiwan Glass Ind. Corp.
- Vitro
- Xinyi Glass Holdings Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, float glass market size in 2026 is estimated at 76.86 million tons, growing from 2025 value of 74.27 million tons with 2031 projections showing 91.18 million tons, growing at 3.48% CAGR over 2026-2031.
This report is Segmented by Product Type (Clear, Tinted, Patterned, Wired, and Extra Clear/Low Ferrous), Application (Building and Construction, Automotive, Solar Glass, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Float Glass Market Trends and Insights
Construction-Sector Expansion in Emerging Economies
Decisive public-sector outlays on transport, housing, and industrial corridors are fueling sustained purchases of architectural glass across South and Southeast Asia. India's construction pipeline equals 3.5 times the sector's annual operating revenue. Thailand's Eastern Economic Corridor continues to absorb large sheet volumes even as labor shortages slow project execution. With regional float lines already running at utilization rates below 80%, producers situated near these demand hubs can ramp shipments swiftly without green-field investments. As a result, the float glass market will rely on fast-growing emerging economies to offset plateauing consumption in mature Western countries.
Automotive Lightweighting Raises Glazing M2 Per Vehicle
Electrification mandates have made weight a premium KPI for automakers, yet advanced driver-assistance systems, panoramic roofs, and immersive infotainment screens are simultaneously expanding the glass surface area per car. This paradox underpins a structural upswing for the float glass market, as OEMs specify thinner yet larger laminated or tempered panes that integrate antennas, heaters, and head-up-display coatings. Fuyao's decision to inject CNY 5.8 billion (USD 804 million) into new float lines dedicated to electrified vehicle platforms illustrates the scale of the opportunity. The resulting requirement for optical clarity and electromagnetic transparency supports premium pricing, ensuring that volume growth feeds directly into revenue and margin expansion for technologically capable suppliers.
Polymer and Polycarbonate Substitutes in Safety Glazing
Automotive and architectural standards permit polycarbonate solutions that weigh 40-50% less than laminated glass while matching impact resistance. Weight-sensitive OEMs therefore experiment with polymer roofs and rear windows; however, scratch performance, UV stability, and optical distortion issues still confine usage to niche placements. Glass makers answer with thinner, lighter laminates using advanced PVB interlayers, as evidenced by Eastman's European capacity expansion. The resulting material joust moderates the float glass market CAGR but also catalyzes innovation, widening the product envelope and raising entry barriers.
Other drivers and restraints analyzed in the detailed report include:
- Utility-Scale Solar Build-Outs Boost Demand for Low-Iron Float Glass
- BIPV Facade Regulations Spur Ultra-Clear Low-Iron Substrates
- EU Carbon Border Adjustment Mechanism Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Clear sheet controlled 62.70% of the float glass market share in 2025 and will register the highest 3.79% CAGR through 2031. This dominance reflects unrivaled versatility: facade glazing, automotive windscreens, and low-iron solar covers all demand transparency levels unattainable by tinted or patterned variants. Manufacturers channel research and development budgets into purification and melt-homogeneity technologies that suppress bubble content and iron residue, securing margins that offset commodity headwinds. Tinted and patterned sheets persist as design-driven niches, yet their uptake follows cyclical architectural trends rather than structural technology shifts.
Extra-clear low-ferrous grades sit at the premium apex, powered by solar boom economics and luxury facade aesthetics. NSG's Pilkington Mirai(TM) and Xinyi's 2.0 mm glass lines exemplify the emphasis on both embodied-carbon cuts and extreme thinness. As N-type solar modules cascade through production lines, sheet rejection rates rise, paradoxically lifting clear-glass tonnage per installed gigawatt. Integrated sand quarries and real-time impurity scanners thus become critical competitive assets across the float glass market.
Complete Report Scope:
- By Product Type
- Clear
- Tinted
- Patterned
- Wired
- Extra Clear/Low Ferrous Floated Glass
- By Application
- Building and Construction
- Automotive
- Solar Glass
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Vietnam
- Thailand
- Indonesia
- Malaysia
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordic Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Nigeria
- Qatar
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominates the float glass market, supplying 62.65% of global output in 2025 and advancing at a 3.92% CAGR to 2031. China anchors the base with mega-scale kiln clusters, while India rides an unprecedented USD 1.5 trillion construction upcycle that absorbs large sheets for residential towers and logistics parks. Thailand's infrastructure spend around the Eastern Economic Corridor cushions regional demand dips tied to residential slowdowns. Yet Asian exporters must navigate rising freight charges and looming CBAM levies, prompting pilot investments in hybrid furnaces and rooftop solar to reduce shipped-ton CO2.
Europe, historically the cradle of float innovation, is now the crucible for low-carbon manufacturing. Saint-Gobain's ORAE series combines high recycled content with cradle-to-cradle certification, while AGC Interpane's upgrades in Germany and Austria elevate line efficiencies despite weak housing starts.
North America capitalizes on nearshoring dynamics and clean-energy incentives. Fuyao's USD 400 million boost to its Illinois float facility ensures just-in-time supply for Midwest EV plants. Combined with the Inflation Reduction Act's manufacturing tax credits, these moves shift import reliance toward domestically melted sheets, narrowing latency and carbon footprints. South America and the Middle East and Africa deliver incremental tonnage via stadium builds, desalination projects, and smart-city launches, but limited local capacity keeps per-capita consumption below mature-market norms.
- AGC Inc.
- BG
- CARDINAL GLASS INDUSTRIES, INC
- China Glass Holding
- China Luoyang Float Glass Group Co., Ltd.
- Flat Glass Group Co., Ltd
- Fuyao Group
- Guardian Industries Holdings
- Kibing Group
- Nippon Sheet Glass Co., Ltd
- PRESS GLASS Holding SA
- PT Mulia Industrindo Tbk
- Saint-Gobain
- SCHOTT
- Sisecam
- Taiwan Glass Ind. Corp.
- Vitro
- Xinyi Glass Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Construction Sector Expansion in Emerging Economies
- 4.2.2 Automotive Lightweighting Raises Glazing M2 Per Vehicle
- 4.2.3 Utility-Scale Solar Buildouts Boost Demand for Low-Iron Float Glass
- 4.2.4 Urban Regeneration Mandates Energy-Efficient Facades
- 4.2.5 BIPV Facade Regulations Spur Ultra-Clear Low-Iron Substrates
- 4.3 Market Restraints
- 4.3.1 Volatile Soda-Ash and Natural-Gas Prices
- 4.3.2 Polymer and Polycarbonate Substitutes in Safety Glazing
- 4.3.3 EU Carbon Border Adjustment Mechanism Compliance Costs (under-radar)
- 4.4 Value Chain Analysis
- 4.5 Raw Material Analysis
- 4.5.1 Sand
- 4.5.2 Limestone
- 4.5.3 Soda Ash
- 4.5.4 Dolomite
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Product Type
- 5.1.1 Clear
- 5.1.2 Tinted
- 5.1.3 Patterned
- 5.1.4 Wired
- 5.1.5 Extra Clear/Low Ferrous Floated Glass
- 5.2 By Application
- 5.2.1 Building and Construction
- 5.2.2 Automotive
- 5.2.3 Solar Glass
- 5.2.4 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Vietnam
- 5.3.1.6 Thailand
- 5.3.1.7 Indonesia
- 5.3.1.8 Malaysia
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Nordic Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Nigeria
- 5.3.5.3 Qatar
- 5.3.5.4 United Arab Emirates
- 5.3.5.5 Egypt
- 5.3.5.6 South Africa
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AGC Inc.
- 6.4.2 BG
- 6.4.3 CARDINAL GLASS INDUSTRIES, INC
- 6.4.4 China Glass Holding
- 6.4.5 China Luoyang Float Glass Group Co., Ltd.
- 6.4.6 Flat Glass Group Co., Ltd
- 6.4.7 Fuyao Group
- 6.4.8 Guardian Industries Holdings
- 6.4.9 Kibing Group
- 6.4.10 Nippon Sheet Glass Co., Ltd
- 6.4.11 PRESS GLASS Holding SA
- 6.4.12 PT Mulia Industrindo Tbk
- 6.4.13 Saint-Gobain
- 6.4.14 SCHOTT
- 6.4.15 Sisecam
- 6.4.16 Taiwan Glass Ind. Corp.
- 6.4.17 Vitro
- 6.4.18 Xinyi Glass Holdings Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 全球低鐵玻璃市場:市場規模、佔有率、趨勢和成長分析(2026-2034)
 低鐵玻璃:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 2026年全球建築用透明浮法玻璃市場報告2026年全球浮法玻璃市場報告
 全球浮法玻璃市場:按厚度、產品、終端用途產業和地區分類的市場規模-預測至2030年
 浮法玻璃市場按產品類型、厚度、塗層類型、應用和分銷管道分類-2025-2030 年全球預測
 浮法玻璃的全球市場的評估:各類型,各用途,各地區,機會,預測(2018年~2032年)浮法玻璃的印度市場評估:各類型,各用途,各地區,機會,預測(2019年度~2033年度)
 浮法玻璃機械市場、佔有率、規模、趨勢、行業分析報告(按類型、應用和地區)- 市場預測,2025-2034 年