


 |
市場調查報告書
商品編碼
2124112
高爾夫球車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Golf Cart - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
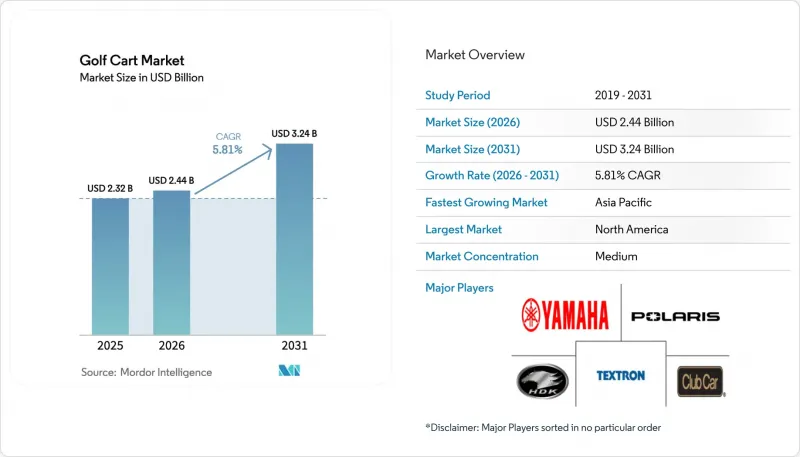
據 Mordor Intelligence 稱,2025 年高爾夫球車市值為 23.2 億美元,預計到 2031 年將達到 32.4 億美元,而 2026 年為 24.4 億美元,預測期(2026-2031 年)的複合年成長率為 5.81%。
本報告按動力系統(電動、汽油、太陽能混合動力)、乘客容量(2座、4座、6座、8座以上)、車身類型(敞篷、封閉式)、應用領域(高爾夫球場等)、銷售管道(線下、線上)和地區進行細分。市場預測以價值(美元)和銷售(輛)為單位呈現。
全球高爾夫球車市場趨勢與洞察
美國退休社區新趨勢的迅速傳播
在佛羅裡達州、亞利桑那州和南卡羅來納州,高爾夫球車已成為老年住宅的主要交通工具。領先的營運商「The Villages」管理著一支龐大的高爾夫球車車隊,並且每年都保持著顯著的成長。近年來,佛羅裡達州的經銷商高爾夫球車銷量大幅成長。這一成長主要由年輕的退休人士推動,他們會改裝自己的高爾夫球車,例如加裝升高懸吊、LED 照明和藍牙音響等,以確保其符合道路法規。在達尼丁和巴拿馬城,市政法令擴大了低速行駛區域的範圍,允許住宅直接通往零售和醫療機構。因此,四座高爾夫球車的需求日益成長,反映了多代同堂家庭的需求。最近,美國國家公路交通安全管理局 (NHTSA) 宣布修訂安全標準,強制要求高爾夫球車,特別是那些在未來幾年內在公共道路上行駛的高爾夫球車,必須配備安全帶、擋風玻璃和轉向燈。
作為海灣合作理事會(GCC)大型企劃的一部分,計劃建造高爾夫球場周邊城鎮。
在沙烏地阿拉伯,NEOM正在推廣吉多里(Guidori)和吉迪亞(Qiddiya)滑雪場,以及位於阿拉伯聯合大公國的紅海滑雪場。為了應對沙漠酷熱,紅海滑雪場正在引入不同座位容量的封閉式空調滑雪車。吉迪亞滑雪場計劃在未來幾年吸引大量遊客,因此迫切需要大容量VIP滑雪車。這些雄心勃勃的項目正在推動與供應商的合作,並透過重點發展溫控電池和太陽能混合屋頂,大幅減少對傳統發電機的依賴。
鋰離子電池組成本波動
近年來,電池組價格大幅下降,達到五年多來的最低水準。儘管價格下跌,但大部分電芯生產仍集中在中國,中國在全球產量中佔相當大的佔有率。依賴進口的拉丁美洲和非洲等地區的組裝製造商正面臨供應鏈中斷的挑戰,導致進口零件成本上升。國際能源總署(IEA)預測,隨著磷酸鋰鐵(LFP)和鈉離子電池技術的進步,以及規模生產的推進,未來幾年電池成本可望進一步降低。Yamaha計劃於2020年代中期推出的新款電動代步車將採用自主研發的創新LFP電池組。與以往使用鉛酸電池的車型相比,這款新設計可望顯著提高能源效率,即使在市場波動的情況下也能提供更穩定可靠的解決方案。
細分市場分析
由於大多數球場都配備了完善的充電基礎設施,因此電動代步車佔據市場主導地位,市場佔有率高達78.81%。然而,受離網度假村對自給自足需求的日益成長的推動,太陽能混合模式高爾夫球車市場預計將以5.83%的複合年成長率成長。洛斯納蘭霍斯高爾夫俱樂部已證明,在其屋頂安裝太陽能板可降低40%的電力成本,並可在五年內收回投資。磷酸鐵鋰電池正以更高的能量密度和循環壽命取代鉛酸電池,而Yamaha的氫燃料電池概念則預示著未來市場的多元化發展。諸如歐盟2023/1804號法規等相關法規正在加速淘汰汽油動力車輛,從而縮小了內燃機高爾夫球車的長期發展前景。
中國供應商提供的CE認證太陽能屋頂和150瓦涓流充電器套裝售價低於400美元,使混合動力高爾夫球車成為東南亞和加勒比地區營運商的理想選擇。高爾夫球車市場持續吸收來自報廢電動車的電池組,這有助於穩定電池供應並減少排放。
到2025年,雙座車型仍將佔據最大的市場佔有率,達到47.63%,但四座車型的成長速度最快,這主要得益於陽光地帶住宅的廣泛接受。預計到2031年,四座高爾夫球車的市場規模將以每年5.88%的速度成長。像EZ-GO的「Liberty」和Yamaha的五座「G30E」這樣的車型,在空間利用率和乘客容量之間取得了良好的平衡。
在退休社區,諸如後向座椅和儲物箱等維修推動了售後市場的收入成長。在海灣合作理事會(GCC)地區的大型企劃中,配備空調的6人座和8人座卡丁車是貴賓和團體娛樂的首選,形成了一個高階需求細分市場。
區域分析
預計到2025年,北美將佔總銷售量的38.71%,憑藉其成熟的老年人社區文化和廣泛的課程網路,北美仍將是其核心市場。儘管FMVSS 305a安全標準的標準化預計將推高平均售價,但也會加速老舊車輛的更新換代。加拿大更嚴格的消防法規將增加維修成本,但Clubcar、Yamaha和Textron等公司在加拿大本地的生產將確保較短的交貨週期和客製化的服務方案。
亞太地區是成長最快的地區,複合年成長率達5.87%。在東南亞國協中,泰國在球童車普及方面處於領先地位,這得益於當地製造商和旅遊業主導的球童車需求。 2022年,中國市場規模已達1.3447億美元,隨著應用範圍擴展到公園和工業園區,到2029年可望翻倍。在日本,五人座球童車更受歡迎,原始設備製造商(OEM)正在整合電磁感應系統,以實現球童車在球道上的自動駕駛。印度城鎮的球童車車隊正處於試點階段,如果融資方案得以建立,則有望實現大規模部署。
在歐洲,機會與風險並存。雖然強制電氣化確保了替換需求,但英國、德國和法國會員人數的下降正在減緩銷售成長。西班牙和義大利的高爾夫俱樂部正透過太陽能屋頂和電池儲能的組合來抵消電力成本,並在五年內獲利。南美和中東的絕對數量落後於歐洲,但成長率最高,海灣合作理事會(GCC)國家的大型企劃為封閉式空調高爾夫球車樹立了高階標竿。加勒比海島嶼在採用太陽能混合動力方面處於領先,巴貝多的電池再利用試點計畫展示了循環經濟的優勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新的趨勢正在美國退休群體中迅速蔓延,尤其是在陽光地帶各州。
- 歐洲的高爾夫球場和鄉村俱樂部必須實現電氣化。
- 東南亞島嶼正在將微型交通項目融入度假設施中。
- 在海灣合作理事會國家,規劃完善的高爾夫球場城鎮正作為大型企劃的一部分迅速湧現。
- 印度區域運輸車輛的OEM捆綁融資
- 在加勒比海一個電力供應有限的度假小鎮,一輛太陽能混合動力汽車正在進行試運行。
- 市場限制因素
- 鋰離子電池組成本波動(2023年及以後受供應衝擊影響)
- 西歐高爾夫俱樂部會員人數下降
- 加強地方政府關於手推車存放的消防安全法規(美國和加拿大)
- 加勒比海離島缺乏充電基礎設施
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 依推進類型
- 電動高爾夫球車
- 汽油動力高爾夫球車
- 太陽能混合動力高爾夫球車
- 按座位數
- 雙座
- 四座
- 6座
- 8人或以上
- 車輛類型
- 敞篷
- 封閉式/防風雨式
- 透過使用
- 高爾夫球場
- 個人/住宅出行
- 商業服務(度假村、主題樂園、校園)
- 工業及機場公用設施
- 按銷售管道
- 線下(經銷商和分銷商)
- 線上/直接向消費者銷售
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 土耳其
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Club Car LLC
- Yamaha Golf-Car Company
- Textron Specialized Vehicles(EZ-GO, Cushman)
- Columbia Vehicle Group(ParCar)
- HDK Electric Vehicles
- Suzhou Eagle EV Mfg. Co.
- JH Global Services(Star EV)
- Dongguan Excellence Golf & Sightseeing Car
- ICON EV
- Marshell Electric Vehicle
- Bintelli Electric Vehicles
- Xiamen Dalle Electric Car
- Polaris GEM(Polaris Inc.)
- Speedways Electric
- AgT Electric Cars
- CitEcar Electric Vehicles
- Kandi Technologies Group
- Tomberlin(Columbia)
- ELLWEE AB
第7章 市場機會與未來展望
According to Mordor Intelligence, the golf cart market size was valued at USD 2.32 billion in 2025 and estimated to grow from USD 2.44 billion in 2026 to reach USD 3.24 billion by 2031, at a CAGR of 5.81% during the forecast period (2026-2031).
This report is Segmented by Propulsion Type (Electric, Gasoline, and Solar-Hybrid), Seating Capacity (2, 4, 6, and 8+ Seater), Vehicle Format (Open-Top and Enclosed), Application (Golf Courses and More), Sales Channel (Offline and Online), and Geography. Market Forecasts in Value (USD) and Volume (Units).
Global Golf Cart Market Trends and Insights
United States Retirement Communities Rapidly Adopting New Trends
In Florida, Arizona, and South Carolina, retirement communities have made carts a staple mode of transport. The Villages, a prominent player, operates a substantial number of units and boasts significant annual growth. In recent years, Florida dealers have experienced a considerable increase in cart sales. This growth is largely driven by younger retirees who are customizing their carts with features like lifted suspensions, LED lighting, and Bluetooth audio, ensuring they're street-legal. In Dunedin and Panama City, city ordinances have expanded low-speed vehicle zones, linking homes directly to retail areas and healthcare facilities. As a result, there's an increasing demand for four-seater carts, reflecting the needs of multigenerational households. Recently, the National Highway Traffic Safety Administration introduced updated safety standards, requiring the integration of seat belts, windshields, and turn signals in carts over the coming years, especially for those on public roads .
Planned Golf Townships Emerging in GCC Mega-Projects
Saudi Arabia's NEOM's Gidori and Qiddiya, along with the United Arab Emirates' Red Sea courses, are introducing enclosed, air-conditioned carts with varying seating capacities, designed to combat the sweltering desert heat. Qiddiya, aiming to attract a significant number of annual visitors in the coming years, is in dire need of high-capacity VIP fleets. These ambitious projects are fostering partnerships with suppliers, focusing on thermally managed batteries and solar-hybrid roofs, significantly reducing dependence on traditional generators .
Lithium-Ion Pack Cost Volatility
In recent years, battery pack prices have experienced a significant decline, reaching their lowest levels in over half a decade. Despite this reduction, the majority of cell production continues to be heavily concentrated in China, accounting for a substantial share of the global output. Import-dependent assemblers in regions such as Latin America and Africa face challenges due to disruptions in the supply chain, which have led to increased costs for imported components. According to the International Energy Agency, further cost reductions are anticipated in the coming years as advancements in lithium iron phosphate (LFP) and sodium-ion battery chemistries gain momentum and achieve greater scalability . Yamaha's upcoming electric cart model, scheduled for release in the middle of the decade, features an innovative in-house battery pack utilizing LFP chemistry. This new design is expected to deliver significantly improved energy efficiency compared to earlier models that relied on lead-acid batteries, providing a more stable and reliable solution amidst market volatility.
Other drivers and restraints analyzed in the detailed report include:
- OEM Bundled Financing for Community Fleets in India
- Caribbean Resorts Piloting Solar-Hybrid Carts
- Declining Golf Membership in Western Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electric carts dominate with 78.81% share, anchored by mature charging infrastructure at most courses. The golf cart market size for solar-hybrid models, however, is projected to grow at a 5.83% CAGR, catalyzed by off-grid resorts seeking autonomy. Los Naranjos Golf Club cut electricity costs by 40% by adding rooftop panels, validating a five-year payback. LFP batteries displace lead-acid, improving energy density and cycle life, while Yamaha's hydrogen fuel-cell concept hints at future diversification. Regulations such as EU 2023/1804 accelerate the pivot away from gasoline, narrowing long-term prospects for combustion carts.
Chinese suppliers offer CE-marked solar roofs bundled with 150 W trickle chargers priced under USD 400, making hybrids attractive for Southeast Asian and Caribbean operators. The golf cart market continues to absorb battery-reuse packs from end-of-life EVs, smoothing supply and lowering emissions footprints.
Two-seater units still hold the largest slice with 47.63% market share in 2025, yet four-seaters advance fastest on the back of Sun-belt residential adoption. The golf cart market size for four-seater models is forecast to expand 5.88% per year through 2031. Players like E-Z-GO's Liberty and Yamaha's five-seat G30Es bridge space efficiency with greater passenger accommodation.
Retirement communities retrofit rear-facing seats and cargo boxes, spurring aftermarket revenue. GCC mega-projects lean toward six- and eight-seater, air-conditioned carts for VIP and group play, shaping premium demand tiers.
Complete Report Scope:
- By Propulsion Type
- Electric Golf Carts
- Gasoline Golf Carts
- Solar-Hybrid Golf Carts
- By Seating Capacity
- 2 Seater
- 4 Seater
- 6 Seater
- 8+ Seater
- By Vehicle Format
- Open-Top
- Enclosed / Weather-proof
- By Application
- Golf Courses
- Personal / Residential Mobility
- Commercial Services (Resorts, Theme-Parks, Campuses)
- Industrial & Airport Utility
- By Sales Channel
- Offline (Dealers & Distributors)
- Online / Direct-to-Consumer
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
North America, with 38.71% revenue in 2025, remains the anchor due to entrenched retirement-community culture and extensive course networks. FMVSS 305a harmonizes safety compliance, likely raising average selling prices but also spurring replacement of older fleets. Canada's stricter fire codes add retrofit costs, while localized production by Club Car, Yamaha, and Textron ensures quick lead times and tailored service packages.
Asia Pacific is the fastest-rising region at a 5.87% CAGR. Thailand leads ASEAN adoption, supported by local manufacturers and tourism-driven cart demand. China's market, already USD 134.47 million in 2022, could double by 2029 as applications widen to parks and industrial campuses. Japan's preference for five-seat caddie carts pushes OEMs to integrate electromagnetic guidance for autonomous fairway loops. India's township fleets enter pilot stage, signaling potential scale once bundled financing solidifies.
Europe blends opportunity and risk. Electrification mandates guarantee replacement demand, yet United Kingdom, German, and French membership attrition reduces volume upside. Clubs in Spain and Italy offset power costs through solar roofs and battery-storage pairs, breaking even within five years. South America and the Middle East trail in absolute numbers but post the steepest percentage gains, with GCC mega-projects setting premium benchmarks for enclosed, cooled carts. Caribbean islands pioneer solar-hybrid adoption as battery-reuse labs in Barbados illustrate circular-economy gains.
- Club Car LLC
- Yamaha Golf-Car Company
- Textron Specialized Vehicles (E-Z-GO, Cushman)
- Columbia Vehicle Group (ParCar)
- HDK Electric Vehicles
- Suzhou Eagle EV Mfg. Co.
- JH Global Services (Star EV)
- Dongguan Excellence Golf & Sightseeing Car
- ICON EV
- Marshell Electric Vehicle
- Bintelli Electric Vehicles
- Xiamen Dalle Electric Car
- Polaris GEM (Polaris Inc.)
- Speedways Electric
- AgT Electric Cars
- CitEcar Electric Vehicles
- Kandi Technologies Group
- Tomberlin (Columbia)
- ELLWEE AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 United States Retirement Communities, Especially in the Sun-belt States, are Rapidly Adopting New Trends
- 4.2.2 European Golf Courses and Country Clubs are Mandated to Electrify their Operations
- 4.2.3 Southeast Asian Islands are Integrating Micro-Mobility Programs Into their Resorts
- 4.2.4 Planned Golf Townships are Quickly Emerging as Part of Mega-projects in the GCC
- 4.2.5 OEM Bundled-Financing for Community Transport Fleets in India
- 4.2.6 Caribbean Resorts with Low Grid Access are Piloting Solar-hybrid Carts
- 4.3 Market Restraints
- 4.3.1 Lithium-Ion Pack Cost Volatility (Post-2023 Supply Shock)
- 4.3.2 Declining Golf Membership in Western Europe
- 4.3.3 Municipal Fire-Code Tightening for Cart Storage (United States and Canada)
- 4.3.4 Sparse Charging Infrastructure in Outlying Caribbean Islands
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Propulsion Type
- 5.1.1 Electric Golf Carts
- 5.1.2 Gasoline Golf Carts
- 5.1.3 Solar-Hybrid Golf Carts
- 5.2 By Seating Capacity
- 5.2.1 2 Seater
- 5.2.2 4 Seater
- 5.2.3 6 Seater
- 5.2.4 8+ Seater
- 5.3 By Vehicle Format
- 5.3.1 Open-Top
- 5.3.2 Enclosed / Weather-proof
- 5.4 By Application
- 5.4.1 Golf Courses
- 5.4.2 Personal / Residential Mobility
- 5.4.3 Commercial Services (Resorts, Theme-Parks, Campuses)
- 5.4.4 Industrial & Airport Utility
- 5.5 By Sales Channel
- 5.5.1 Offline (Dealers & Distributors)
- 5.5.2 Online / Direct-to-Consumer
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Turkey
- 5.6.5.5 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Club Car LLC
- 6.4.2 Yamaha Golf-Car Company
- 6.4.3 Textron Specialized Vehicles (E-Z-GO, Cushman)
- 6.4.4 Columbia Vehicle Group (ParCar)
- 6.4.5 HDK Electric Vehicles
- 6.4.6 Suzhou Eagle EV Mfg. Co.
- 6.4.7 JH Global Services (Star EV)
- 6.4.8 Dongguan Excellence Golf & Sightseeing Car
- 6.4.9 ICON EV
- 6.4.10 Marshell Electric Vehicle
- 6.4.11 Bintelli Electric Vehicles
- 6.4.12 Xiamen Dalle Electric Car
- 6.4.13 Polaris GEM (Polaris Inc.)
- 6.4.14 Speedways Electric
- 6.4.15 AgT Electric Cars
- 6.4.16 CitEcar Electric Vehicles
- 6.4.17 Kandi Technologies Group
- 6.4.18 Tomberlin (Columbia)
- 6.4.19 ELLWEE AB
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 北美高爾夫球車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 高爾夫球車市場-2026-2032年全球市場預測
 高爾夫球車和社區型電動車(NEV) 市場規模、佔有率和成長分析:按車輛類型、驅動系統、應用、最終用戶和地區分類-2026-2033 年產業預測高爾夫球車和社區型電動車市場:2026-2032年全球市場預測(按車輛類型、電池電壓、續航里程、座位數、應用和銷售管道)
 高爾夫球車市場分析及預測(至2035年):類型、產品類型、服務、技術、組件、應用、最終用戶、功能、使用模式
 全球高爾夫球車市場規模、佔有率、趨勢和成長分析報告(2026-2034年)全球高爾夫球車和新能源汽車市場:市場規模、佔有率、趨勢和成長分析(2026-2034 年)
 高爾夫球車市場:按類型、應用和地區分類
 2026年全球高爾夫球車及周邊電動車(NEV)市場報告2026年全球高爾夫球車市場報告