


 |
市場調查報告書
商品編碼
2123669
生物識別:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Biometrics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,生物識別市場規模將從 2025 年的 589.8 億美元成長到 2026 年的 678.6 億美元,然後在 2031 年達到 1,368.6 億美元,2026 年至 2031 年的複合年成長率為 15.07%。
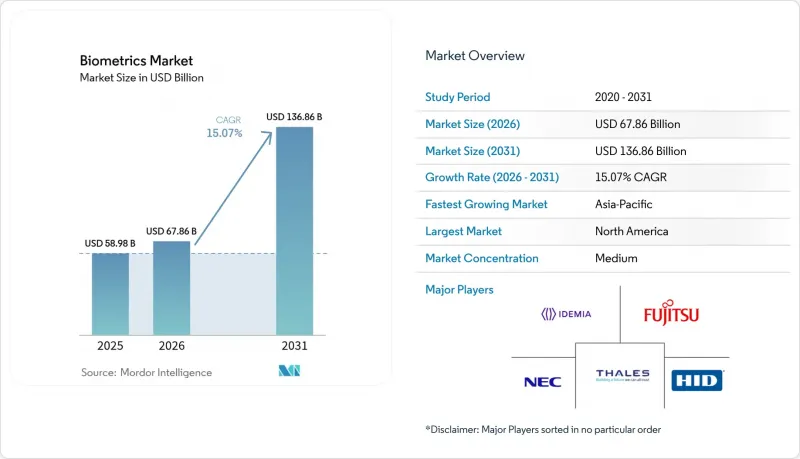
本報告按組件(硬體、軟體、服務)、生物識別方法(生理、行為)、接觸類型(接觸式、非接觸式、混合式)、認證類型(單因素、多因素)、應用(門禁控制、支付認證、其他)、最終用戶行業(政府、銀行、金融服務和保險業、其他)以及地區進行細分。市場預測以美元計價。
全球生物識別市場趨勢及洞察
亞洲各國政府主導的國家電子識別項目
亞洲各國政府正大力推動大規模數位身分轉型。韓國基於智慧型手機的居民登記卡以及越南決定在2025年7月前將生物識別身分證推廣至外國人,都在為包容性生態系統樹立標竿。印尼斥資2億美元打造的「INA Digital」平台以及菲律賓8,950萬公民的登記,使得先前沒有銀行帳戶的成年人也能獲得金融服務。斯里蘭卡結合指紋、臉部和視網膜掃描的多模態計畫於2026年完成,展現了新興經濟體如何跨越傳統基礎設施的鴻溝。
EMVCo 和 ISO 標準促進了指紋支付卡的發展。
隨著EMVCo和ISO標準的統一,生物識別卡已從試點階段過渡到商業發行階段。英飛凌的SECORA Pay Bio晶片和泰雷茲的全球檢測體系降低了誤識率,並提高了交易限額。萬事達卡的身份驗證和密碼支援功能可實現無縫認證,並幫助發卡機構減少詐欺和扣回爭議帳款。隨著銀行優先發展無PIN碼的非接觸式支付體驗,供應商預測2028年,生物識別卡的出貨量將達到1.133億張。
GDPR 和 BIPA 帶來的訴訟風險阻礙了發展。
2024年至2025年間,與《伊利諾州臉部辨識隱私法案》(BIPA)相關的和解金額超過2億美元,其中包括Clearview AI公司支付的5,175萬美元和解金。這表明,未經明確同意而實施臉部辨識技術的公司可能面臨巨額賠償責任。 GDPR嚴格的資料最小化和本地處理規則導致歐洲每次實施的合規成本高達5萬至20萬歐元(約合5.65萬至22.6萬美元),從而限制了小規模專案的應用範圍。美國聯邦貿易委員會(FTC)對Rite Aid公司採取的糾正措施,在美國演算法偏見審計方面樹立了先例,迫使供應商重新設計其架構,以確保「隱私納入設計」。
細分市場分析
儘管硬體仍佔總收入的 41.92%,但軟體引擎已從輔助角色躍升為成長最快的組成部分,複合年成長率高達 16.35%。該公司專注於雲端協作、基於人工智慧的生物識別檢測以及不斷適應不斷變化的欺詐手段的去中心化身份錢包。 Entrust 收購 Onfid 符合這一趨勢,而新增的深度造假防範措施則使防止身分偽造的有效性提高了五倍。
硬體領域仍然至關重要,尤其是在專用感測器向安全元件傳輸加密模板的場景中。英飛凌的汽車級指紋辨識晶片就是一個典型的例子,它展示了量產級組件如何將生物識別市場拓展到行動出行和門禁控制領域。雖然服務領域的規模最小,但隨著整合商為受監管行業量身打造多模態部署方案,其需求正穩定成長。
虹膜辨識正以17.85%的複合年成長率快速成長,這得益於液態透鏡光學技術的進步,該技術降低了組件成本並縮小了外形規格。指紋辨識技術依然穩固,即使到2025年,它仍將佔據生物識別市場36.55%的佔有率,這主要得益於智慧型手機、支付卡和考勤管理系統的普及。臉部認證在機場和體育場館的應用日益廣泛,而語音分析技術在客服中心的身份驗證中也發揮著越來越重要的作用。
行為生物生物識別,特別是步態模式和擊鍵的動態特徵,增加了一層被動的安全保障,在不增加使用者負擔的情況下提升了安全性。成熟的指紋和臉部認證解決方案正擴大與虹膜、掌紋或語音模組結合,形成多模態辨識套件,從而拓展收入來源並降低單一模式的風險。
區域分析
到2025年,在聯邦預算和私營部門廣泛應用的支持下,北美將佔全球收入的30.35%。美國運輸安全局(TSA)加快了安檢通道的擴建,國防安全保障部(DHS)也撥款2.508億美元用於身分管理,這些措施為供應商提供了多年的支持。加拿大和墨西哥正在對其陸地邊境的電子閘門進行現代化改造,以簡化貿易流程,從而加強北美大陸的部署。
亞太地區正呈現最快的成長軌跡,預計到2031年複合年成長率將達到18.10%。韓國全國行動身分識別系統的部署、中國臉部辨識監管法規的製定以及印度與Aadhaar合作推出的支付服務,正在推動一個規模遠超單一國家計畫的綜合生物識別市場的發展。該地區48億數位錢包用戶正推動生物識別驗證(KYC)從銀行和電信公司的可選流程轉變為強制性流程。
在歐洲,在《一般資料保護規範》(GDPR)的嚴格監管下,經濟持續穩定成長。歐盟的出入境管理系統(EES)正在申根區各邊境引入生物識別,而英國新的信任框架則促進了私部門在認證技術方面的創新。北歐國家的試點計畫表明,設備端處理能夠在不犧牲速度的前提下滿足隱私監管機構的要求,這正在影響整個歐洲的採購標準。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 亞洲國家政府主導的國家電子識別計劃
- 透過 EMVCo 和 ISO 標準,促進北美和歐洲採用指紋認證支付卡。
- 疫情後歐洲商業不動產對非接觸式物理門禁的需求
- 美國運輸安全局(TSA) 的生物識別藍圖正在推動聯邦政府採購激增。
- 中國的「智慧機場2025」計畫加快了臉部認證和語音辨識技術的應用。
- 海灣合作理事會和非洲各國中央銀行強制生物識別KYC(了解你的客戶)流程
- 市場限制因素
- GDPR 和 BIPA 帶來的訴訟風險阻礙了臉部辨識技術的應用。
- 演算法對深色膚色的偏好導致採購暫時中止。
- CMOS影像感測器的供不應求限制了指紋認證模組的供應。
- 對南美零售連鎖店整合和投資回報率的擔憂
- 價值供應鏈分析
- 監理展望
- 技術展望
- 波特五力分析
- 產業相關人員分析
- 投資與資金籌措分析
第5章 市場規模與成長預測
- 按組件
- 硬體
- 軟體
- 服務
- 通過生物識別方法
- 生理生物生物識別
- 指紋自動指紋辨識系統
- 非自動指紋辨識系統(AFIS)指紋識別
- 臉部認證
- 虹膜辨識
- 其他(掌靜脈、手部形態)
- 行為生物生物識別
- 語音辨識
- 簽名認證
- 其他(步態分析、擊鍵動態)
- 生理生物生物識別
- 聯繫類型
- 聯繫類型
- 非接觸式
- 混合
- 按身份驗證類型
- 單元素
- 多元素
- 透過使用
- 物理和邏輯存取控制
- 考勤管理
- 支付和交易認證
- 電子護照和邊境管制
- 病患身分識別和電子健康記錄(EHR) 安全性
- 客戶註冊(電子身份驗證)
- 公共監督和安全
- 汽車和智慧車輛的介面
- 按最終用途行業分類
- 政府和執法機關
- BFSI
- 衛生保健
- 家用電子電器
- 商業和零售
- 旅遊與移民
- 軍事/國防
- 車
- 教育
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 北歐的
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- ASEAN
- 澳洲
- 紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 以色列
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 肯亞
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Thales Group
- NEC Corporation
- IDEMIA France SAS
- Fujitsu Limited
- HID Global Corporation
- Assa Abloy AB
- Aware Inc.
- Suprema Inc.
- Synaptics Incorporated
- Bio-Key International Inc.
- Zwipe AS
- Fingerprint Cards AB
- M2SYS Technology
- Infineon Technologies AG
- Entrust Corporation
- ImageWare Systems Inc.
- Phonexia sro
- BioID AG
- Crossmatch Technologies Inc.
- Hitachi Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the biometrics market size is expected to grow from USD 58.98 billion in 2025 to USD 67.86 billion in 2026 and is forecast to reach USD 136.86 billion by 2031 at 15.07% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Biometric Modality (Physiological, Behavioral), Contact Type (Contact-Based, Contactless, Hybrid), Authentication Type (Single-Factor, Multi-Factor), Application (Access Control, Payment Authentication, and More), End-Use Industry (Government, BFSI, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Biometrics Market Trends and Insights
Government-backed National e-ID Programs Across Asia
Asian authorities are orchestrating large-scale digital identity transformations. South Korea's smartphone-based resident registration card and Vietnam's decision to extend biometric IDs to foreign nationals by July 2025 have set benchmarks for inclusive ecosystems. Indonesia's USD 200 million INA Digital platform and the Philippines' registration of 89.5 million citizens unlock financial services for previously unbanked adults. Sri Lanka's multi-modal program combining fingerprints, face, and retina scans targets completion in 2026, illustrating how emerging economies leapfrog legacy infrastructures.
EMVCo and ISO Standards Catalyzing Fingerprint Payment Cards
Harmonized EMVCo and ISO rules have moved biometric cards from pilots to commercial issuance. Infineon's SECORA Pay Bio silicon and Thales' global trials cut false-accept rates and allow higher transaction ceilings . Mastercard's Identity Check and passkey support promise frictionless authentication, helping issuers reduce fraud and chargebacks. Vendors forecast shipments of 113.3 million biometric cards by 2028 as banks prioritize PIN-free contactless experiences.
GDPR and BIPA Litigation Risks Curtailing Roll-outs
More than USD 200 million in BIPA settlements during 2024-2025, including Clearview AI's USD 51.75 million payment, signals material liability for enterprises deploying facial recognition without explicit consent. GDPR's strict data-minimization and local-processing rules add EUR 50,000-200,000 (USD 56,500-226,000) compliance cost per European installation, shrinking the addressable base for small projects. The FTC's enforcement against Rite Aid sets a U.S. precedent for algorithmic-bias audits, compelling vendors to redesign architectures for privacy by design.
Other drivers and restraints analyzed in the detailed report include:
- U.S. TSA Biometrics Road-map Driving Federal Procurement Surge
- China's "Smart Airport 2025" Policy Accelerating Face & Voice Biometrics
- Algorithmic Bias Triggering Procurement Moratoriums
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software engines grew from a supporting role to the highest-growth component at a 16.35% CAGR, even while hardware kept the 41.92 revenue share. Organizations value cloud orchestration, AI-based liveness detection, and decentralized identity wallets that continuously adapt to evolving fraud. Entrust's acquisition of Onfido aligns with this trajectory, adding deep-fake countermeasures that improved forged-ID prevention five-fold.
The hardware segment remains indispensable where specialized sensors deliver cryptographic templates to secure elements. Infineon's automotive-qualified fingerprint ICs illustrate how production-grade components expand the biometrics market into mobility and access domains. Services, while smallest, record consistent uptake as integrators customize multi-modal deployments for regulated industries.
Iris recognition posts an 17.85% CAGR, supported by liquid-lens optics that lower bill-of-material cost and shrink form factors. Fingerprint remains entrenched with 36.55% of biometrics market share in 2025, thanks to smartphones, payment cards, and time-clock systems. Facial recognition steadily penetrates airports and stadiums, while voice analytics gains footing in call-center authentication.
Behavioral biometrics, particularly gait and keystroke dynamics, add passive layers that elevate security without user friction. Mature fingerprint and facial solutions increasingly pair with iris, palm-vein, or voice modules in multi-modal kits, diversifying revenue and diluting single-modality risk.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Biometric Modality
- Physiological Biometrics
- Fingerprint AFIS
- Fingerprint Non-AFIS (Automated Fingerprint Identification System)
- Facial Recognition
- Iris Recognition
- Others (Palm Vein, Hand Geometry)
- Behavioral Biometrics
- Voice Recognition
- Signature Verification
- Others (Gait Analysis, Keystroke Dynamics)
- Physiological Biometrics
- By Contact Type
- Contact-based
- Contactless
- Hybrid
- By Authentication Type
- Single-factor
- Multi-factor
- By Application
- Physical and Logical Access Control
- Time and Attendance Management
- Payment and Transaction Authentication
- e-Passport and Border Control
- Patient Identification and EHR Security
- Customer On-boarding (eKYC)
- Public Surveillance and Safety
- Automotive and Smart Vehicle Interfaces
- By End-Use Industry
- Government and Law Enforcement
- BFSI
- Healthcare
- Consumer Electronics
- Commercial and Retail
- Travel and Immigration
- Military and Defense
- Automotive
- Education
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Australia
- New Zealand
- Rest of Asia Paccific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America produced 30.35% of global revenue in 2025, anchored by federal budgets and widespread private-sector adoption. TSA's accelerating lane expansions and DHS's USD 250.8 million line-item for identity management provide a multi-year demand floor for vendors . Canada and Mexico modernize land-border e-gates to streamline trade, reinforcing continental scale.
Asia Pacific records the steepest trajectory with an 18.10% CAGR forecast to 2031. South Korea's nationwide mobile-ID completion, China's codified face-recognition rules, and India's Aadhaar-linked pay services cultivate a unified biometrics market bigger than any single-country program. The region's 4.8 billion digital-wallet users push biometric KYC from optional to mandatory across banks and telecoms.
Europe's growth remains steady under strict GDPR oversight. The EU Entry/Exit System rolls out border biometrics across Schengen states, while the United Kingdom's new trust framework fosters private-sector credential innovation. Nordic pilots prove that on-device processing can satisfy privacy watchdogs without sacrificing speed, shaping procurement criteria across the continent.
- Thales Group
- NEC Corporation
- IDEMIA France SAS
- Fujitsu Limited
- HID Global Corporation
- Assa Abloy AB
- Aware Inc.
- Suprema Inc.
- Synaptics Incorporated
- Bio-Key International Inc.
- Zwipe AS
- Fingerprint Cards AB
- M2SYS Technology
- Infineon Technologies AG
- Entrust Corporation
- ImageWare Systems Inc.
- Phonexia s.r.o.
- BioID AG
- Crossmatch Technologies Inc.
- Hitachi Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-backed National e-ID Programs Across Asia
- 4.2.2 EMVCo and ISO Standards Catalyzing Fingerprint Payment Cards in North America and Europe
- 4.2.3 Post-pandemic Demand for Touch-free Physical Access in European Commercial Real-estate
- 4.2.4 U.S. TSA Biometrics Road-map Driving Federal Procurement Surge
- 4.2.5 China's "Smart Airport 2025" Policy Accelerating Face and Voice Biometrics
- 4.2.6 Biometric KYC Mandates by GCC and African Central Banks
- 4.3 Market Restraints
- 4.3.1 GDPR and BIPA Litigation Risks Curtailing Facial-Recognition Roll-outs
- 4.3.2 Algorithmic Bias Against Dark-Skin Demographics Triggering Procurement Moratoriums
- 4.3.3 CMOS Image-Sensor Shortages Constricting Fingerprint Module Supply
- 4.3.4 Integration and ROI Concerns in South-American Retail Chains
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Industry Stakeholder Analysis
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Biometric Modality
- 5.2.1 Physiological Biometrics
- 5.2.1.1 Fingerprint AFIS
- 5.2.1.2 Fingerprint Non-AFIS (Automated Fingerprint Identification System)
- 5.2.1.3 Facial Recognition
- 5.2.1.4 Iris Recognition
- 5.2.1.5 Others (Palm Vein, Hand Geometry)
- 5.2.2 Behavioral Biometrics
- 5.2.2.1 Voice Recognition
- 5.2.2.2 Signature Verification
- 5.2.2.3 Others (Gait Analysis, Keystroke Dynamics)
- 5.2.1 Physiological Biometrics
- 5.3 By Contact Type
- 5.3.1 Contact-based
- 5.3.2 Contactless
- 5.3.3 Hybrid
- 5.4 By Authentication Type
- 5.4.1 Single-factor
- 5.4.2 Multi-factor
- 5.5 By Application
- 5.5.1 Physical and Logical Access Control
- 5.5.2 Time and Attendance Management
- 5.5.3 Payment and Transaction Authentication
- 5.5.4 e-Passport and Border Control
- 5.5.5 Patient Identification and EHR Security
- 5.5.6 Customer On-boarding (eKYC)
- 5.5.7 Public Surveillance and Safety
- 5.5.8 Automotive and Smart Vehicle Interfaces
- 5.6 By End-Use Industry
- 5.6.1 Government and Law Enforcement
- 5.6.2 BFSI
- 5.6.3 Healthcare
- 5.6.4 Consumer Electronics
- 5.6.5 Commercial and Retail
- 5.6.6 Travel and Immigration
- 5.6.7 Military and Defense
- 5.6.8 Automotive
- 5.6.9 Education
- 5.6.10 Others
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 United Kingdom
- 5.7.3.2 Germany
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Nordics
- 5.7.3.7 Russia
- 5.7.3.8 Rest of Europe
- 5.7.4 Asia Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 South Korea
- 5.7.4.4 India
- 5.7.4.5 ASEAN
- 5.7.4.6 Australia
- 5.7.4.7 New Zealand
- 5.7.4.8 Rest of Asia Paccific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 Saudi Arabia
- 5.7.5.1.2 United Arab Emirates
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Israel
- 5.7.5.1.5 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Kenya
- 5.7.5.2.4 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes global overview, market overview, core segments, financials, strategic information, market rank/share, products and services, recent developments)
- 6.4.1 Thales Group
- 6.4.2 NEC Corporation
- 6.4.3 IDEMIA France SAS
- 6.4.4 Fujitsu Limited
- 6.4.5 HID Global Corporation
- 6.4.6 Assa Abloy AB
- 6.4.7 Aware Inc.
- 6.4.8 Suprema Inc.
- 6.4.9 Synaptics Incorporated
- 6.4.10 Bio-Key International Inc.
- 6.4.11 Zwipe AS
- 6.4.12 Fingerprint Cards AB
- 6.4.13 M2SYS Technology
- 6.4.14 Infineon Technologies AG
- 6.4.15 Entrust Corporation
- 6.4.16 ImageWare Systems Inc.
- 6.4.17 Phonexia s.r.o.
- 6.4.18 BioID AG
- 6.4.19 Crossmatch Technologies Inc.
- 6.4.20 Hitachi Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 全球步態辨識市場(2026-2030 年)
 生物識別卡:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 全球生物識別卡市場規模、佔有率、趨勢和成長分析報告(2026-2034年)軍事生物識別:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026年全球軍事生物辨識市場報告下一代生物識別:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 生物識別系統市場-2026-2032年全球市場預測生物識別和身分管理市場:2026-2032年全球市場預測(按技術類型、組件、認證方法、應用、最終用戶和部署模式分類)消費性電子生物識別市場:2026-2032年全球市場預測(依產品、模式、技術、設備類型、接觸方式、外形規格、應用及銷售管道)生物識別市場:按組件、技術類型、交付方式、認證方式、行動性和最終用戶產業分類-2026-2032年全球市場預測