


 |
市場調查報告書
商品編碼
2123570
智慧鎖:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Smart Lock - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
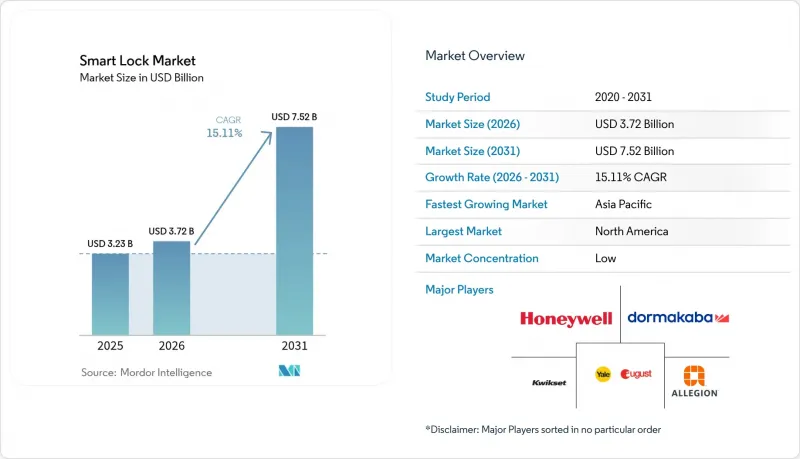
據 Mordor Intelligence 稱,2025 年智慧鎖市場價值為 32.3 億美元,預計到 2031 年將達到 75.2 億美元,而 2026 年為 37.2 億美元,預測期(2026-2031 年)的複合年成長率為 15.11%。
本報告依鎖具類型(插銷鎖、拉桿鎖等)、通訊技術(藍牙、Wi-Fi等)、認證方式(密碼/小鍵盤、生物識別(指紋、臉部辨識)等)、最終用戶(住宅、商業辦公等)和地區進行細分。市場預測以美元計價。
全球智慧鎖市場趨勢及洞察
智慧家庭生態系統的快速普及
在集中式設備管理需求日益成長的推動下,智慧門鎖已成為連網家庭升級的熱門選擇。耶魯、Schlage 和 Level 共同推出的「Matter-over-Thread」技術打破了廠商鎖定,並將電池續航時間延長至 12 個月以上。鑑於美國已有 70% 的家庭使用語音助手,這項技術正在加速語音控制門鎖的普及。計劃於 2026 年推出的 Thread 1.4 版本將進一步增強生態系統整合,使新產品無需額外閘道器即可連接到現有網路。
都市區入室竊盜犯罪率上升,安全隱患日益嚴重
都市區的犯罪模式提高了住宅的警覺性,數據顯示,83%的入侵者會在入室行竊前偵察安全措施。將智慧門鎖與影像驗證結合,可消除傳統系統常見的15秒警報響應延遲。 Lockly的臉部辨識引擎現在可以在1.5秒內偵測到未經授權的人臉,並發送即時警報,從而防止機會主義犯罪。在人口密集的高層住宅中,匿名性往往會助長入侵,因此結合生物識別和PIN碼的多因素身份驗證可以提供多層保護。
網路安全與駭客攻擊漏洞
備受矚目的資料外洩事件暴露了主流產品中生物識別繞過和可複製NFC標籤的問題。消費者組織的測試發現,85.7%的晶片設備至少有一項嚴重缺陷。儘管廠商現在提供端對端加密和雙重登入認證,但硬體設計的差異使得集中式修補程式管理難以實現。連接與標準聯盟(CSA)內的產業組織正在製定基本要求,但由於實現方法存在顯著差異,網路安全風險依然居高不下。
細分市場分析
預計到2025年,插銷鎖將佔智慧鎖銷售額的45.12%,反映出住宅普遍對其實體強度充滿信心。這一佔有率在硬體形式的智慧鎖市場中佔據最大比例。受飯店和辦公室ADA殘障人士需求的推動,拉桿式門把手系統預計將實現15.18%的複合年成長率,創歷史新高,這表明其操作簡便性在高人流量環境中廣受歡迎。
消費者對隱蔽升級的需求推動了對隱藏電子元件的售後鎖芯的興趣。 Level 的隱形鎖心就是一個典型的例子。掛鎖式智慧型裝置適用於戶外工業應用場景,但防水成本高昂,使其仍處於小眾市場。儘管持續的小型化可能會模糊產品類別的界限,但預計到 2031 年,插銷式智慧鎖仍將保持其在智慧鎖市場的主導地位。
預計到2025年,藍牙將佔據61.68%的市場佔有率,成為智慧門鎖的主要連接方式。它易於與智慧型手機配對,因此非常適合路由器連接不穩定的出租房屋。然而,由於通訊範圍和網狀網路能力的限制,它不太適合多用戶住宅。
受Matter認證和Silicon Labs超低功耗SoC的推動,Zigbee-Thread協定棧預計將以16.74%的複合年成長率成長。儘管存在電池消耗方面的擔憂,Wi-Fi在優先考慮直接遠端控制的「雲端優先」部署中仍然被廣泛應用。更新的超寬頻(UWB)技術可實現免持、高精度操作,但在出貨量提升之前,仍將被歸類為「其他」類別。各種協定的標準化正在推進,消除了市場分割,這一趨勢有望推動智慧鎖市場的整體普及。
區域分析
預計到2025年,北美將佔全球銷售額的37.05%,這主要得益於智慧家庭的早期普及、有利的建築規範以及智慧安防產品可享高達10%的保險折扣。在美國,開發商正將智慧門鎖視為標配,從而推動了房屋翻新需求。加拿大也緊跟其後,利用類似的建築規範和寬頻普及率優勢。
亞太地區預計將以15.42%的複合年成長率領跑,反映出快速的都市化和中產階級可支配所得的成長。中國在智慧家庭產品出貨量方面處於領先地位,而印度的住宅自動化市場預計將成長39.79%,其中智慧門鎖在消費者的升級清單中名列前茅。在日本,人口老化推動了對非接觸式門禁解決方案的需求成長,以支持老年人的獨立生活。
在歐洲,在能源效率指令和嚴格的隱私法規的推動下,智慧鎖市場正穩步發展。雖然先進的加密要求推高了開發成本,但也促進了符合GDPR要求的差異化產品的交付。中東和非洲市場目前規模較小,但受益於智慧城市建設投資,這些投資已融入新的房地產項目中,從而開闢了一條快速擴張的管道,並將提升智慧鎖市場的未來標準。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 智慧家庭生態系統的快速普及
- 都市區入室竊盜犯罪率上升,安全隱患日益嚴重
- 智慧型手機和物聯網的廣泛應用使得遠端存取成為可能。
- 透過建築規範推廣免鑰匙節能門的廣泛應用。
- Airbnb 等類型的出租房產對自動化房客入住和退房管理的需求。
- 安裝智慧門鎖可享住宅保險保費折扣
- 市場限制因素
- 網路安全與駭客攻擊漏洞
- 高昂的初始終端和安裝成本
- 消費者關注電池壽命和維護問題
- 維修項目中協議之間的互通性差距
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 按鎖類型
- 門栓
- 槓桿手柄
- 掛鎖
- 其他
- 透過通訊技術
- Bluetooth
- Wi-Fi
- Zigbee
- 其他
- 身份驗證方法
- PIN碼小鍵盤
- 生物識別(指紋、臉部)
- RFID/NFC卡
- 其他
- 最終用戶
- 住宅
- 商業辦公
- 飯店和短期租賃
- 工業和基礎設施
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 東南亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ASSA ABLOY(Yale, August)
- Allegion plc(Schlage)
- Spectrum Brands Holdings(Kwikset)
- dormakaba Group
- Honeywell International
- SALTO Systems
- U-TEC(ULTRALOQ)
- Lockly
- Master Lock
- Nuki Home Solutions
- Netatmo(Legrand)
- SimpliSafe
- Samsung SDS
- Aqara(Xiaomi)
- Eufy Security(Anker)
- Level Home
- Tedee
- Hanman International
- Panasonic Life Solutions
- Xiaomi Mi Smart Home
第7章 市場機會與未來展望
According to Mordor Intelligence, the smart lock market size was valued at USD 3.23 billion in 2025 and estimated to grow from USD 3.72 billion in 2026 to reach USD 7.52 billion by 2031, at a CAGR of 15.11% during the forecast period (2026-2031).
This report is Segmented by Lock Type (Deadbolt, Lever Handle, and More), Communication Technology (Bluetooth, Wi-Fi, and More), Authentication Method (Pin-Code / Keypad, Biometric (Fingerprint, Face), and More), End User (Residential, Commercial Offices, and More) and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Lock Market Trends and Insights
Rapid Adoption of Smart-Home Ecosystems
Growing preference for unified device control makes smart lock integration one of the first upgrades in connected homes. Matter-over-Thread launches by Yale, Schlage, and Level are removing vendor lock-in and extending battery life to more than 12 months. Voice assistants already reside in 70% of United States households, which accelerates voice-enabled locking. Scheduled Thread 1.4 adoption by 2026 will let new products join existing networks without additional hubs, further tightening ecosystem stickiness.
Rising Burglary and Safety Concerns in Urban Areas
Urban crime patterns have raised homeowner vigilance, and data show 83% of burglars survey security setups before entry. Integrating a smart lock with video verification closes the 15-second alarm response gap common in legacy systems. Lockly's facial recognition engine now flags unauthorized faces in 1.5 seconds, sending real-time alerts that deter opportunistic crime. Multi-factor combinations of biometrics and PINs add layered protection for dense residential high-rises where anonymity often aids break-ins.
Cyber-Security and Hacking Vulnerabilities
High-profile breaches have exposed biometric bypasses and cloneable NFC tags in mainstream models. Tests by one consumer association found 85.7% of chip-activated units exhibited at least one critical flaw. Vendors now ship end-to-end encryption and two-factor log-ins, yet fragmented hardware designs make universal patching hard to maintain. Industry groups within the Connectivity Standards Alliance are drafting baseline requirements, but wide variation in implementation keeps cyber-risk elevated.
Other drivers and restraints analyzed in the detailed report include:
- Smartphone and IoT Proliferation Enabling Remote Access
- Building-Code Push for Keyless Energy-Efficient Doors
- Up-Front Device and Installation Cost Premium
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Deadbolts retained 45.12% of 2025 revenue, reflecting widespread homeowner confidence in their physical robustness. This share equates to the largest slice of the smart lock market size for hardware formats. Lever handle systems achieved the leading 15.18% CAGR due to ADA compliance needs in hotels and offices, demonstrating how ease-of-operation appeals to high-traffic settings.
Consumers seeking discreet upgrades have driven interest in retrofit cylinders that hide electronics inside existing housings, exemplified by Level's invisible mechanism. Padlock-style smart devices service out-door industrial use cases but remain niche because of weather-proofing costs. Continuous miniaturization will likely blur category boundaries, though deadbolts are expected to keep a commanding presence through 2031 in the smart lock market.
Bluetooth held 61.68% share in 2025, translating into the top position within the smart lock market share for connectivity. Its phone-to-lock pairing simplicity favors rental properties where router access is uncertain. Range and mesh limitations, however, make it less suited to multi-unit dwellings.
The Zigbee-Thread stack is projected for a 16.74% CAGR, propelled by Matter certification and Silicon Labs' ultra-low-power SoCs. Wi-Fi continues in cloud-first deployments that prioritize direct remote control despite battery drain. Emerging ultra-wideband adds hands-free precision but sits within the "Others" bucket until shipping volumes scale. Across protocols, standardization is shrinking fragmentation, a trend that will raise the overall smart lock market adoption curve.
Complete Report Scope:
- By Lock Type
- Deadbolt
- Lever Handle
- Padlock
- Others
- By Communication Technology
- Bluetooth
- Wi-Fi
- Zigbee
- Others
- By Authentication Method
- Pin-Code / Keypad
- Biometric (Fingerprint, Face)
- RFID / NFC Card
- Others
- By End-user
- Residential
- Commercial Offices
- Hospitality and Short-term Rentals
- Industrial and Infrastructure
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America secured 37.05% of 2025 revenue due to early smart-home adoption, favorable codes, and insurance discounts of up to 10% for connected security. The United States drives renovation demand as developers view smart locks as standard amenity packages. Canada follows, leveraging similar building norms and broadband penetration.
Asia-Pacific is set for the highest 15.42% CAGR, reflecting rapid urban migration and growing middle-class disposable income. China leads smart-home shipments, while India's residential automation pipeline shows a 39.79% expansion outlook that positions smart locks near the top of consumer upgrade lists. Japan's aging demographic attracts contactless door solutions supporting senior independence.
Europe posts steady progression anchored by energy-efficiency directives and strong privacy oversight. Advanced encryption requirements raise development costs yet promote differentiated offerings that comply with GDPR. The Middle East and Africa, though smaller today, benefit from smart-city investments baked into greenfield real-estate projects, enabling leapfrog adoption paths that raise the future baseline of the smart lock market.
- ASSA ABLOY (Yale, August)
- Allegion plc (Schlage)
- Spectrum Brands Holdings (Kwikset)
- dormakaba Group
- Honeywell International
- SALTO Systems
- U-TEC (ULTRALOQ)
- Lockly
- Master Lock
- Nuki Home Solutions
- Netatmo (Legrand)
- SimpliSafe
- Samsung SDS
- Aqara (Xiaomi)
- Eufy Security (Anker)
- Level Home
- Tedee
- Hanman International
- Panasonic Life Solutions
- Xiaomi Mi Smart Home
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid adoption of smart-home ecosystems
- 4.2.2 Rising burglary and safety concerns in urban areas
- 4.2.3 Smartphone and IoT proliferation enabling remote access
- 4.2.4 Building-code push for keyless energy-efficient doors
- 4.2.5 Airbnb-style rentals demanding automated guest access
- 4.2.6 Home-insurance premium discounts for connected locks
- 4.3 Market Restraints
- 4.3.1 Cyber-security and hacking vulnerabilities
- 4.3.2 Up-front device and installation cost premium
- 4.3.3 Battery-life / maintenance anxieties among consumers
- 4.3.4 Inter-protocol interoperability gaps in retrofit projects
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Lock Type
- 5.1.1 Deadbolt
- 5.1.2 Lever Handle
- 5.1.3 Padlock
- 5.1.4 Others
- 5.2 By Communication Technology
- 5.2.1 Bluetooth
- 5.2.2 Wi-Fi
- 5.2.3 Zigbee
- 5.2.4 Others
- 5.3 By Authentication Method
- 5.3.1 Pin-Code / Keypad
- 5.3.2 Biometric (Fingerprint, Face)
- 5.3.3 RFID / NFC Card
- 5.3.4 Others
- 5.4 By End-user
- 5.4.1 Residential
- 5.4.2 Commercial Offices
- 5.4.3 Hospitality and Short-term Rentals
- 5.4.4 Industrial and Infrastructure
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Southeast Asia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.2.5 Egypt
- 5.5.5.2.6 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ASSA ABLOY (Yale, August)
- 6.4.2 Allegion plc (Schlage)
- 6.4.3 Spectrum Brands Holdings (Kwikset)
- 6.4.4 dormakaba Group
- 6.4.5 Honeywell International
- 6.4.6 SALTO Systems
- 6.4.7 U-TEC (ULTRALOQ)
- 6.4.8 Lockly
- 6.4.9 Master Lock
- 6.4.10 Nuki Home Solutions
- 6.4.11 Netatmo (Legrand)
- 6.4.12 SimpliSafe
- 6.4.13 Samsung SDS
- 6.4.14 Aqara (Xiaomi)
- 6.4.15 Eufy Security (Anker)
- 6.4.16 Level Home
- 6.4.17 Tedee
- 6.4.18 Hanman International
- 6.4.19 Panasonic Life Solutions
- 6.4.20 Xiaomi Mi Smart Home
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 美國智慧鎖:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 智慧鎖市場:2026-2032年全球市場預測(依鎖類型、通訊協定、認證方式、應用及銷售管道)
 2026 年至 2035 年住宅智慧鎖的市場機會、成長要素、產業趨勢與預測。
 全球智慧鎖市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 智慧門鎖和門鈴市場預測至2034年-按產品類型、鎖具類型、通路、最終用戶和地區分類的全球分析
 2026年全球人工智慧(AI)智慧鎖市場報告2026年全球智慧鎖控制器市場報告
 智慧鎖市場規模、佔有率、趨勢和預測:按鎖類型、通訊協定、最終用戶和地區分類,2026-2034年
 智慧鎖市場:按產品類型、解鎖方式、應用程式和地區分類2026年全球智慧鎖市場報告