


 |
市場調查報告書
商品編碼
2123435
北美全地形車和多用途車:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)North America ATV And UTV - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,北美 ATV 和 UTV 市場預計到 2026 年價值將達到 117.9 億美元,高於 2025 年的 109.6 億美元,預計到 2031 年將達到 169.5 億美元。
預計 2026 年至 2031 年的複合年成長率為 7.55%。
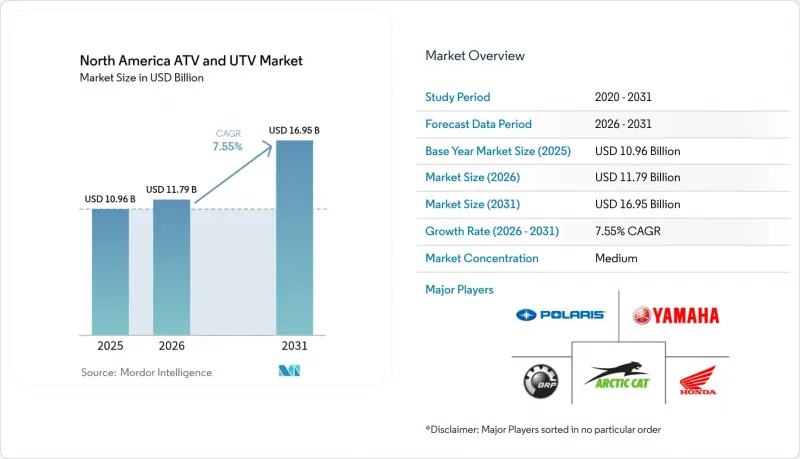
本報告按車輛類型(全地形車和多用途地形車)、動力系統/燃料類型(汽油、柴油等)、最終用途行業(混合動力等)、座位數/乘客容量(單座、2-3座、4-6座)、驅動方式(兩輪驅動等)和地區(美國等)進行細分。市場預測以價值(美元)和銷售(輛)為單位。
北美全地形車及多用途車市場趨勢及洞察
農業機械化的需求日益成長
這款安裝在全地形車上的基於機器學習的作物調查附件結合了頻譜成像和人工智慧視覺分析,能夠即時檢測作物養分缺乏情況,從而使產量提高15-20%。農民在購買時將耐用性視為首要考慮因素,這促使原始設備製造商(OEM)加固卡車貨廂,以承受450公斤乾草捆的重量。目前,經銷商可選裝精度達亞米級的GPS導航套件,該套件可自動完成不平坦田地中的噴灑和土壤取樣作業。農業部門佔全地形車相關死亡事故的五分之三,因此提高安全性至關重要。為此,該車配備了翻滾檢測系統,可在感知器啟動後200毫秒內切斷引擎動力。目前正在愛荷華州進行初步試驗的自動駕駛原型車以「跟隨我」模式運作,跟隨聯合收割機,從而在收割高峰期降低人工人事費用。這些創新使 UTV 不僅僅是可有可無的購買品,而是農場的必備資產,從而支撐了北美 ATV 和 UTV 市場的長期需求。
休閒和賽車運動活動增加
由各州旅遊局資助的全地形車(ATV)越野道總長度持續成長,賓州的區域越野道連接線(Regional Trail Connector)就是一個典型的例子。該項目目前已將1200英里的多用途路線與當地的住宿設施中心連接起來。導遊業者透過將設備租賃、越野道通行證和安全裝備打包成週末套餐,每年為租賃公司累計超過8.5萬美元的利潤。在威斯康辛州,一項允許全地形車和多用途越野車在指定縣級道路上行駛的法律修正案促進了「騎乘式」和「騎乘式」旅遊的發展,增加了當地住宿和餐飲服務企業的收入。設備製造商正在聯合贊助一些節日活動,例如2025年在猶他州舉行的派尤特越野車節(Paiute Trail Jamboree),展示新車型並透過遠端資訊處理技術收集即時性能數據。因此,北美全地形車和多用途越野車市場佔據了全球全地形車需求的很大一部分,為售後零組件和服裝銷售提供了強勁的支撐。
高昂的購置和維護成本
高階UTV的售價如今已超過3萬美元,例如2025款北極星Ranger XP Kinetic,選配所有配置後售價高達37,499美元。對於商業車隊所有者而言,由於各品牌動力系統、懸吊和電池模組的差異,高昂的保險成本和零件庫存正令其營運資金捉襟見肘。雖然預計電動車款將在五年內降低五分之一以上的營運成本,但經銷商有限的服務能力會導致高壓零件故障時長時間停機。對於需要管理季節性現金流的小規模農場而言,資金籌措的複雜性是一個難題。貸款機構通常要求20%的首付以及非車輛抵押品。價格壓力正在減緩車輛的更換週期,儘管北美ATV和UTV市場的長期基本面強勁,但短期銷售仍然低迷。
細分市場分析
到2025年,多用途地形車(UTV)將佔據北美ATV和UTV市場71.18%的佔有率,年複合成長率達7.66%。 UTV用途廣泛,涵蓋建築、緊急應變和野外旅遊等領域,其多功能性尤其引人注目。這一市場主導地位進一步增強了貨箱襯墊、駕駛室封閉裝置和液壓升降套件供應商的規模經濟優勢。預計到2031年,北美ATV和UTV市場中多用途UTV的佔有率將大幅成長,這得益於經銷商安裝的遠端資訊處理系統在市政車輛管理標準化方面的普及。像YamahaWolverine RMAX4 1000這樣的運動型UTV車型,在保持高利潤率的同時,也幫助製造商展示了可應用於商用車型的懸吊技術。
全地形車 (ATV) 佔據著一個獨特的市場,在這個市場中,單人駕駛的操控性、輕量化和窄輪距至關重要,尤其是在強制要求車輛長度小於 50 英寸的越野路段。根據原始設備製造商 (OEM) 的藍圖,預計到 2025 年,將有六款新型 ATV 車型問世,這些車型將整合電子油門、盲點雷達和原廠絞盤,以抵禦快速發展的 UTV 市場對其市場佔有率的衝擊。 ATV 翻滾安全標準與 UTV 乘員保護協議之間的監管協調可能會模糊傳統車型之間的界限。未來的車型很可能共用底盤零件和電力電子設備。因此,平台模組化有望縮短開發週期,在控制創新步伐的同時,抑制北美 ATV 和 UTV 市場不斷上漲的零件成本。
截至2025年,汽油引擎在北美全地形車(ATV)和多用途車(UTV)市場佔有62.67%的佔有率。然而,由於排放氣體法規日益嚴格以及消費者對更安靜運作的需求不斷成長,電動動力系統正以7.62%的複合年成長率快速擴張。本田在北卡羅來納州持續推進的擴建計畫旨在提升電池組和整車組裝能力,這表明電氣化正逐漸成為主流。假設電池組價格持續走低,預計到2031年,北美ATV和UTV市場中電動車型的市佔率將大幅成長。同時,柴油引擎仍主要應用於牧場和林業等重型作業領域,在這些領域,高扭矩牽引力比能量密度限制更為重要。
像HuntVe的「Switchback」這樣的混合動力增程器概念體現了一種過渡架構。 72V鋰離子電池組可提供40公里的靜音續航里程,之後由708cc汽油引擎接管動力。加州政策制定者已強制實施第五階段非道路車輛排放氣體法規,加速了公共服務車輛的電氣化。然而,電動車要在大眾市場廣泛應用,需要在越野路段和農田等區域部署240V二級充電樁,目前中西部各州的電力公司和經銷商正在透過合作計畫來應對這項挑戰。在這些電網升級改造完成之前,汽油動力車輛很可能仍將繼續主導北美全地形車(ATV)和多用途車(UTV)市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 由於農業機械化的發展,需求日益成長
- 休閒和賽車運動活動增加
- 自然保護和狩獵領域對安靜的電動並排式全地形車的潛在需求
- 懸吊和安全技術的進步
- 步道旅遊推廣計劃
- 農村地區基於寬頻的車輛網路連接
- 市場限制因素
- 高昂的購置和維修成本
- 鋰供應鏈的波動性
- 加強排放氣體和噪音法規
- 關於土地所有者責任的訴訟
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 車輛類型
- 全地形車(ATV)
- 運動型全地形車
- 多用途/工作用全地形車
- 多用途地形車(UTV/並排式)
- 運動型多用途越野車
- 多用途UTV
- 全地形車(ATV)
- 按驅動系統/燃料類型
- 汽油
- 柴油引擎
- 電的
- 按最終用途行業分類
- 混合
- 休閒和體育
- 農業和林業
- 工業與建築
- 軍事/政府
- 搜救和緊急應變服務
- 按座位數/容量
- 單人座
- 2-3個座位
- 4-6個座位
- 透過驅動系統
- 兩輪驅動
- 四輪驅動
- 全輪驅動
- 國家
- 美國
- 加拿大
- 其他北美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Polaris Inc.
- BRP Inc.(Can-Am)
- American Honda Motor Co.
- Yamaha Motor Co.
- Kawasaki Heavy Industries
- Textron Inc.(Arctic Cat & Tracker Off-Road)
- Suzuki Motor Corp.
- CF Moto Powersports
- Kubota Corp.
- Deere & Company(Gator)
- Mahindra Automotive NA(ROXOR)
- Segway Powersports
- Hisun Motors Corp.
- DRR USA Inc.
- Intimidator/BAD BOY Off-Road
- ODES Powersports
- Club Car LLC
- Toro Co.
- Kioti(Daedong-USA)
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America ATV and UTV market size in 2026 is estimated at USD 11.79 billion, growing from 2025 value of USD 10.96 billion with 2031 projections showing USD 16.95 billion, growing at 7.55% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (All-Terrain Vehicles and Utility Terrain Vehicles), Propulsion/Fuel Type (Gasoline, Diesel, and More), End-Use Industry (Hybrid, and More), Seating/Capacity (Single-Seat, 2-3 Seat, and 4-6 Seat), Drive Type (2-Wheel Drive and More), and Geography (United States and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
North America ATV And UTV Market Trends and Insights
Growing Agricultural Mechanization Needs
Machine-learning-based crop-scouting attachments mounted on UTVs deliver 15-20% yield gains by combining multispectral imaging and AI vision analytics that flag nutrient deficiencies in real time. Farmers cite durability as their prime purchase criterion, pushing OEMs to reinforce cargo beds to withstand 450 kg hay bale loads. Precision guidance kits with sub-meter GPS accuracy now ship as dealer-installed options, automating spraying and soil sampling on irregular fields. Safety enhancements remain critical because agriculture accounts for three-fifth of work-related ATV fatalities, prompting roll-over detection systems that cut engine power within 200 ms of sensor activation. Autonomous prototypes undergoing pilot trials in Iowa operate follow-me modes behind combines, reducing hired-hand costs during peak harvest. Such innovations position UTVs as integral field assets rather than discretionary purchases, supporting long-run demand for the North America ATV and UTV market.
Rising Recreational & Motorsports Activities
ATV trail mileage funded by state tourism boards keeps expanding, exemplified by Pennsylvania's Regional Trail Connector that now links 1,200 miles of mixed-use routes to local lodging hubs. Rental fleets report annual profits topping USD 85,000 as guided tour operators bundle equipment hire, trail permits, and safety gear in weekend packages. Wisconsin's statutory update allowing ATVs and UTVs on designated county roads bolsters ride-in/ride-out tourism, lifting rural hospitality revenue. Equipment OEMs co-sponsor festivals such as Utah's 2025 Paiute Trail Jamboree to showcase new models and collect real-time performance data through telematics. As a result, the North America ATV and UTV market captures significant global ATV demand, underpinning sustained aftermarket parts and apparel sales.
High Purchase & Maintenance Costs
Premium UTV stickers now eclipse USD 30,000 with the 2025 Polaris RANGER XP Kinetic topping USD 37,499 in fully optioned trim. For commercial fleet owners, high insurance costs and parts inventory tie up working capital because driveline, suspension, and battery modules remain brand-specific. Electric models promise more than one-fifth lower running costs over five years, yet limited dealership service capability prolongs downtime when high-voltage components fail. Financing complexities emerge for small farms that manage seasonal cash flows; lenders often require 20% down payments and collateral beyond the vehicle. Price pressure delays replacement cycles, muting short-term unit sales despite robust long-term fundamentals for the North America ATV and UTV market.
Other drivers and restraints analyzed in the detailed report include:
- Silent Electric SxS Demand in Conservation & Hunting
- Technological Advances in Suspension & Safety
- Lithium Supply-Chain Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Utility terrain vehicles commanded 71.18% of the North America ATV and UTV market share in 2025 and growing at a 7.66% CAGR, underscoring their multi-purpose appeal across construction, emergency response, and back-country tourism. This dominance-reinforcing scale advantages for cargo-bed liners, cab enclosures, and hydraulic lift kits suppliers. The North America ATV and UTV market size allocated to multi-purpose UTV configurations is set to grow exponentially by 2031, supported by dealer-installed telematics that standardize fleet monitoring for municipalities. Sport-oriented UTV models such as Yamaha's Wolverine RMAX4 1000 help manufacturers defend high-margin niches while showcasing suspension technology transferable to work-focused trims.
All-terrain vehicles maintain niche relevance where single-rider agility, lower curb weight, and narrower track widths matter, particularly on trail systems mandating sub-50-inch vehicles. OEM roadmaps reveal six new ATV variants for 2025, integrating ride-by-wire throttles, blind-spot radar, and factory-installed winches to protect share against rapidly advancing UTVs. Regulatory alignment of ATV rollover standards with UTV occupant-protection protocols could blur historic category boundaries, with future models sharing chassis components and power electronics. Consequently, platform modularity is poised to reduce development cycles, sustaining innovation cadence while tempering bill-of-materials inflation across the North America ATV and UTV market.
Gasoline engines held 62.67% of the North America ATV and UTV market share in 2025. Yet, electrified drivetrains are advancing at a 7.62% CAGR, reflecting tightening emission caps and user preference for low-noise operation. Honda's expansion in North Carolina earmarks battery packs and final vehicle assembly capacity, signaling mainstream adoption. The North America ATV and UTV market size attributable to electric units is projected to grow drastically by 2031, assuming pack prices decline. Meanwhile, diesel remains confined to heavy-duty ranch and forestry applications where high-torque hauling supersedes energy-density constraints.
Hybrid range-extended concepts such as HuntVe's Switchback illustrate transitional architectures: a 72-V lithium pack supplies 40 km silent range before a 708 cc gasoline engine engages. Policymakers in California already mandate stage-V-equivalent off-road emission limits, hastening fleet electrification among public agencies. Yet mass-market electric penetration awaits infrastructure build-out of 240-V Level-2 chargers across trailheads and farmsteads, a requirement now tackled by cooperative utility-dealer programs in Midwestern states. Until such grid upgrades materialize, gasoline will sustain its majority hold on unit volumes within the North America ATV and UTV market.
Complete Report Scope:
- By Vehicle Type
- All-Terrain Vehicles (ATVs)
- Sport ATVs
- Utility/Work ATVs
- Utility Terrain Vehicles (UTVs/Side-by-Sides)
- Sport UTVs
- Multi-purpose UTVs
- All-Terrain Vehicles (ATVs)
- By Propulsion/Fuel Type
- Gasoline
- Diesel
- Electric
- By End-use Industry
- Hybrid
- Recreation & Sports
- Agriculture & Forestry
- Industrial & Construction
- Military & Government
- Search, Rescue & Emergency Services
- By Seating/Capacity
- Single-seat
- 2 - 3 seat
- 4 - 6 seat
- By Drive Type
- 2-Wheel Drive
- 4-Wheel Drive
- All-Wheel Drive
- By Country
- United States
- Canada
- Rest of North America
List of Companies Covered in this Report:
- Polaris Inc.
- BRP Inc. (Can-Am)
- American Honda Motor Co.
- Yamaha Motor Co.
- Kawasaki Heavy Industries
- Textron Inc. (Arctic Cat & Tracker Off-Road)
- Suzuki Motor Corp.
- CF Moto Powersports
- Kubota Corp.
- Deere & Company (Gator)
- Mahindra Automotive NA (ROXOR)
- Segway Powersports
- Hisun Motors Corp.
- DRR USA Inc.
- Intimidator/BAD BOY Off-Road
- ODES Powersports
- Club Car LLC
- Toro Co.
- Kioti (Daedong-USA)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing agricultural mechanisation needs
- 4.2.2 Rising recreational & motorsports activities
- 4.2.3 Silent electric SxS demand in conservation & hunting
- 4.2.4 Technological advances in suspension & safety
- 4.2.5 Trail-tourism incentive programs
- 4.2.6 Rural broadband-enabled fleet connectivity
- 4.3 Market Restraints
- 4.3.1 High purchase & maintenance costs
- 4.3.2 Lithium supply-chain volatility
- 4.3.3 Emission & noise regulation tightening
- 4.3.4 Land-owner liability litigation
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 All-Terrain Vehicles (ATVs)
- 5.1.1.1 Sport ATVs
- 5.1.1.2 Utility/Work ATVs
- 5.1.2 Utility Terrain Vehicles (UTVs/Side-by-Sides)
- 5.1.2.1 Sport UTVs
- 5.1.2.2 Multi-purpose UTVs
- 5.1.1 All-Terrain Vehicles (ATVs)
- 5.2 By Propulsion/Fuel Type
- 5.2.1 Gasoline
- 5.2.2 Diesel
- 5.2.3 Electric
- 5.3 By End-use Industry
- 5.3.1 Hybrid
- 5.3.2 Recreation & Sports
- 5.3.3 Agriculture & Forestry
- 5.3.4 Industrial & Construction
- 5.3.5 Military & Government
- 5.3.6 Search, Rescue & Emergency Services
- 5.4 By Seating/Capacity
- 5.4.1 Single-seat
- 5.4.2 2 - 3 seat
- 5.4.3 4 - 6 seat
- 5.5 By Drive Type
- 5.5.1 2-Wheel Drive
- 5.5.2 4-Wheel Drive
- 5.5.3 All-Wheel Drive
- 5.6 By Country
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 Rest of North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Polaris Inc.
- 6.4.2 BRP Inc. (Can-Am)
- 6.4.3 American Honda Motor Co.
- 6.4.4 Yamaha Motor Co.
- 6.4.5 Kawasaki Heavy Industries
- 6.4.6 Textron Inc. (Arctic Cat & Tracker Off-Road)
- 6.4.7 Suzuki Motor Corp.
- 6.4.8 CF Moto Powersports
- 6.4.9 Kubota Corp.
- 6.4.10 Deere & Company (Gator)
- 6.4.11 Mahindra Automotive NA (ROXOR)
- 6.4.12 Segway Powersports
- 6.4.13 Hisun Motors Corp.
- 6.4.14 DRR USA Inc.
- 6.4.15 Intimidator/BAD BOY Off-Road
- 6.4.16 ODES Powersports
- 6.4.17 Club Car LLC
- 6.4.18 Toro Co.
- 6.4.19 Kioti (Daedong-USA)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 全地形車(ATV)市場:按類型、驅動方式、動力來源、引擎排氣量、乘客容量、變速箱類型、銷售管道和應用分類-2026-2032年全球市場預測
 全地形車(ATV)市場分析及至2035年預測:類型、產品類型、技術、組件、應用、最終用戶、功能、安裝配置、設備全地形車 (ATV) 和多用途車 (UTV) 市場分析及至 2035 年預測:類型、產品、技術、組件、應用、最終用戶、功能、安裝類型、設備、模式
 全地形車引擎市場-全球產業規模、佔有率、趨勢、機會及預測(2021-2031):依類型、需求類別、功率、地區及競爭格局分類電動全地形車市場-全球產業規模、佔有率、趨勢、機會與預測:按應用、驅動類型、地區和競爭格局分類,2021-2031年
 全地形車(ATV)市場報告:按類型、應用、引擎類型、車輪數量、驅動系統、燃料類型、乘客容量和地區分類(2026-2034 年)
 全地形車(ATV)市場:按引擎排氣量、應用和地區分類
 全球全地形車(ATV)市場:按類型、驅動方式、燃料類型、電池容量、引擎排氣量、乘客容量、車輪數量、應用和地區分類-預測至2035年
 全球全地形車(ATV)市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 全地形車(ATV)市場機會、成長要素、產業趨勢分析及2026-2035年預測