


 |
市場調查報告書
商品編碼
2123154
歐洲自行車:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Europe Bicycle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,歐洲自行車市場規模預計在 2026 年達到 333.7 億美元,到 2031 年達到 503.8 億美元,預測期內複合年成長率為 8.59%。
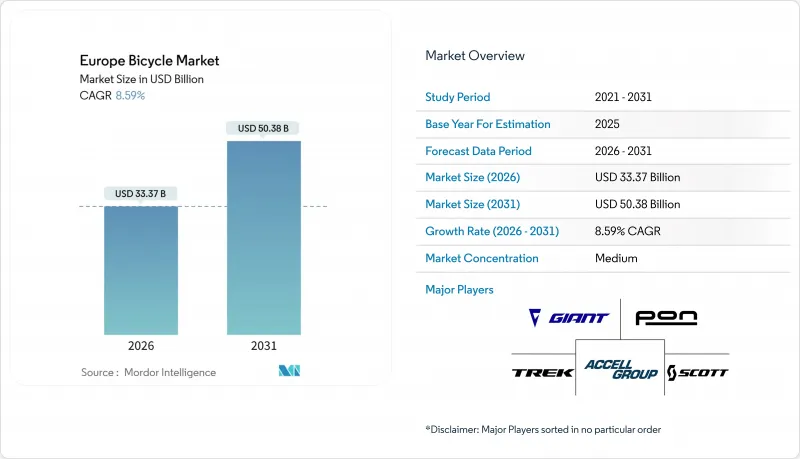
本報告按產品類型(公路/城市自行車、山地/全地形自行車、混合動力自行車、電動自行車及其他)、設計(標準型和折疊式)、最終用戶(男性、女性和兒童)、配銷通路(實體店和線上零售商)以及地區(英國、德國、法國、義大利、西班牙等)進行細分。市場預測以價值(美元)和銷售(輛)兩種形式呈現。
歐洲自行車市場的趨勢和洞察
都市區的交通擁擠促使騎自行車通勤變得越來越受歡迎。
歐洲城市正透過重新定義「最後一公里」和「第一公里」的出行經濟模式來應對交通堵塞問題。巴黎計畫在2021年至2026年間投資2.5億歐元(約2.72億美元),興建1,400公里的專用自行車道。這一轉變反映了市政當局對「誘導需求」的重視,他們優先發展貨運電動自行車和高速電動自行車,而非休閒車款。都市區密度的增加和燃油成本的上漲,使得自行車成為經濟實惠的出行選擇。尤其是電動自行車,正吸引那些通勤距離更長、需要靈活且低排放交通方式的商務人士。歐盟的「永續城市交通計劃」和各國政府的補貼等政策,正將自行車融入公共交通系統,改善「第一公里」和「最後一公里」的連通性,並減少人們對汽車的依賴。世界銀行預測,到2024年,歐盟75%的人口將居住在都市區,這將進一步加劇都市區擁擠。這種人口趨勢增加了人們對日常交通的需求,自行車和電動自行車作為在擁擠的都市區穿梭和最大限度減少旅行時間的有效解決方案,正變得越來越受歡迎。
人們日益增強的健康和健身意識正在推動騎自行車這項休閒的發展。
根據英國體育協會(Sport England)2024年的報告,英格蘭有716.97萬人享受騎行的樂趣,這凸顯了騎行從單純的交通工具向健康健身核心要素的顯著轉變。這種轉變主要源自於後疫情時代人們對健康和福祉日益成長的關注。因此,注重健身的消費者越來越傾向於選擇高階配置,例如輕量化碳纖維車架以提升性能、電子變速系統以實現平順換檔以及內置功率計以進行精準的性能監測,而非價格因素。這種對高級產品日益成長的需求使得製造商即使在總銷量趨於穩定的情況下也能維持較高的利潤率。此外,這個消費族群對價格的敏感度較低,這使得製造商能夠更好地應對政策變化,例如法國決定在2025年2月取消自行車購買補貼計畫。
其他交通途徑的興起給自行車市場佔有率帶來了壓力。
電動滑板車的日益普及和高速交通網路的擴張,正日益加劇都市區交通預算的分散。共享電動滑板車不僅取代了自行車和步行,也取代了公共交通工具。這凸顯出,微型出行方式與自行車的競爭比與汽車的競爭更為直接。在荷蘭,電動滑板車禁止在公共道路上行駛,保護了自行車市場。相較之下,西班牙和法國允許電動滑板車上路,加劇了二者之間的直接競爭。在義大利,濃厚的摩托車文化使情況更加複雜。在羅馬和米蘭等城市,即使徵收堵塞費,摩托車仍因其防風雨和速度優勢而備受歡迎,這限制了自行車的普及。對於自行車製造商而言,戰略重點應該放在提升實用性上,例如載重能力和耐候性,而不是優先考慮速度和便利性,因為這些領域已被電動滑板車和公共交通所佔據。
細分市場分析
預計到2025年,電動自行車將佔據歐洲50.17%的市場佔有率,並預計在2031年之前以9.56%的複合年成長率成長。在中檔車型中,磷酸鋰鐵鋰電池正逐漸取代鎳錳鈷電池,雖然能量密度略低,但循環壽命更長,成本更低。第二大類是公路車和都市自行車,主要針對注重速度和效率的通勤者,尤其是在鋪面路面上。山地自行車和全地形自行車則主要面向阿爾卑斯山和北歐地區的休閒騎行者。混合型自行車兼具公路和越野性能,曾一度受到多用途用戶的青睞。然而,隨著電動自行車馬達的普及,混合型自行車的市場佔有率有所下降,因為電動自行車馬達無需在性能上做出妥協。如今,騎乘者更傾向於選擇專用車架,並利用腳踏助力來應對各種地形。貨運自行車和躺式自行車雖然仍屬於小眾市場,但成長迅速,尤其是在城市物流領域。
隨著電動自行車持續佔據市場主導地位,缺乏馬達和電池整合能力的傳統自行車製造商正面臨利潤率下滑的壓力。博世和禧瑪諾等公司已實現垂直整合,使零件供應商能夠獲得原本屬於車架製造商的附加價值。這一趨勢迫使Canyon和Specialized等品牌在自主研發電子元件和麵臨產品同質化之間做出選擇。歐盟的「替代燃料基礎設施法規」強制要求在職場安裝充電樁,這正在消除電動自行車普及的一大障礙。這項政策不僅反映了前瞻性,也顛覆了傳統的市場動態,使政策能預見消費者需求。
截至2025年,傳統設計的自行車佔了83.35%的市場。然而,折疊式自行車正經歷快速成長,預計從2026年到2031年將以10.21%的複合年成長率成長,成為成長最快的細分市場。 Brompton於2024年推出的「G-Line」系列清晰地展現了人們對折疊式自行車的認知轉變。這些自行車配備20吋車輪、8速變速箱和液壓碟煞,不再只是實用工具,更具備了卓越的性能。同樣,「Electric P-Line」系列採用輕量化的15.6公斤鈦合金車架,是Brompton歷經八年自主研發並獲得UL2849認證的成果。這項成就體現了更嚴格的安全標準,也意味著低成本競爭對手的進入門檻更高。折疊式自行車尤其適用於需要結合多種交通途徑的通勤,例如從火車到辦公室或從汽車到山路的轉換。這項優勢解釋了它們在倫敦、巴黎和柏林等人口稠密城市中為何成長迅速。在這些城市,即使擁有完善的公共交通網路,交通「最後一公里」的銜接也常常存在缺口。
傳統設計因其卓越的騎乘舒適性、零件相容性和高保值率而保持主流地位。自行車愛好者和長途通勤者更重視車架剛性和輪徑而非便攜性,這使得傳統幾何結構的需求持續存在。關鍵在於,折疊式自行車並非取代傳統車型,而是開闢了一個平行類別。它們滿足了都市區商務人士結合騎行和公共交通出行的需求,而不是直接與之競爭。製造商應避免將折疊式自行車定位為「一刀切」的解決方案,而應專注於針對特定通勤群體的細緻行銷和分銷策略。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 由於都市區交通堵塞日益嚴重,騎自行車作為日常通勤方式的人數正在增加。
- 人們日益增強的健康和健身意識正在推動騎行活動的增加。
- 政府為促進永續交通途徑採取的措施正在鼓勵使用自行車。
- 日益增強的環保意識和永續性目標正在推動自行車使用量的增加。
- 企業健康計劃鼓勵員工騎自行車。
- 由於燃油價格飆升,自行車作為一種經濟的交通方式越來越受到關注。
- 市場限制因素
- 摩托車和高速公車系統等其他交通途徑的出現降低了自行車的普及率。
- 電動自行車價格持續高企,阻礙了其在各個地區的廣泛普及。
- 假冒自行車產品的氾濫對市場擴張產生了負面影響。
- 鄉村地區道路基礎設施不足,影響了騎乘體驗。
- 消費行為分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 道路/城市
- 山地/全地形
- 混合
- 電動自行車
- 其他類型
- 有意為之
- 常規的
- 折疊式
- 最終用戶
- 男性
- 女士
- 孩子們
- 透過分銷管道
- 實體店面
- 線上零售商店
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 瑞典
- 比利時
- 波蘭
- 荷蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accell Group NV
- Trek Bicycle Corporation
- Pon Holdings BV
- Giant Manufacturing Co. Ltd
- Scott Sports SA
- Merida Industry Co. Ltd
- Riese and Muller GmbH
- Canyon Bicycles GmbH
- Decathlon SA
- Bosch eBike Systems(Robert Bosch GmbH)
- Shimano Inc.
- VanMoof BV
- Orbea S. Coop.
- KTM Fahrrad GmbH
- myStromer AG
- Bianchi SpA
- Bulls Bikes(ZEG eG)
- Ribble Cycles
- Simplon Fahrrad GmbH
- Specialized Bicycle Components Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe bicycle market size stands at USD 33.37 billion in 2026 and is projected to reach USD 50.38 billion by 2031, registering an 8.59% CAGR over the forecast period.
This report is Segmented by Product Type (Road/City, Mountain/All-Terrain, Hybrid, E-Bicycle, and Other Types), Design (Regular and Folding), End-User (Men, Women, and Children), Distribution Channel (Offline Retail Stores and Online Retail Stores), and Geography (United Kingdom, Germany, France, Italy, Spain, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units)
Europe Bicycle Market Trends and Insights
Urban congestion drives commuter bicycle adoption
European cities are addressing traffic saturation by redefining first-mile and last-mile mobility economics. Paris allocated EUR 250 million (USD 272 million) between 2021 and 2026 to develop 1,400 kilometers of bike lanes. This shift reflects municipalities' focus on induced demand, favoring cargo e-bikes and speed pedelecs over leisure models. Increasing urban density and rising fuel costs position bicycles as a cost-efficient alternative. E-bikes, in particular, extend commuting distances and attract professionals seeking flexible, low-emission travel options. Policies such as the European Union's Sustainable Urban Mobility Plans and national subsidies are integrating cycling into public transit systems, enhancing first and last-mile connectivity while reducing car dependency. In 2024, 75% of the European Union's population resides in cities, according to the World Bank, intensifying urban congestion . This demographic trend increases daily mobility needs, driving the adoption of bikes and e-bikes as efficient solutions for navigating crowded urban areas and minimizing travel times.
Health and fitness awareness fuels recreational cycling
In 2024, Sport England reported that 7,169,700 individuals in England engaged in cycling, highlighting a significant shift where cycling has evolved from being merely a mode of transportation to becoming a core component of wellness and fitness routines. This transformation has been largely driven by the growing emphasis on health and well-being in the post-pandemic era. As a result, fitness-focused consumers are increasingly seeking high-end features, such as lightweight carbon frames for enhanced performance, electronic shifting systems for smoother gear transitions, and integrated power meters for accurate performance monitoring, over prioritizing affordability. This growing demand for premium products allows manufacturers to maintain strong profit margins, even as overall sales volumes begin to stabilize. Moreover, this consumer segment exhibits lower price sensitivity, offering manufacturers a degree of insulation against policy changes, such as France's decision to terminate its bike bonus subsidy in February 2025.
Alternative transportation options constrain bicycle market share
Urban mobility budgets are becoming increasingly fragmented due to the growing popularity of e-scooters and the expansion of rapid transit networks. Shared e-scooters are replacing not only cycling trips and walking but also public transport journeys. This highlights that micro-mobility options are competing more directly with bicycles than with cars. In the Netherlands, the prohibition of e-scooters on public roads protects its cycling market. Conversely, Spain and France allow e-scooters, which intensifies direct competition. In Italy, the strong motorcycle culture adds another layer of complexity: in cities like Rome and Milan, motorcycles remain popular for their weather protection and speed, even with congestion charges, limiting bicycle adoption. For bicycle manufacturers, the strategic focus should be on enhancing utility, such as cargo capacity and weather resistance, rather than prioritizing speed or convenience, as e-scooters and transit options already dominate those areas.
Other drivers and restraints analyzed in the detailed report include:
- Government sustainable transportation policies accelerate market growth
- Environmental consciousness and sustainability goals drive adoption
- Elevated e-bicycle prices limit mass-market penetration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, e-bicycles accounted for 50.17% of the European market share and are expected to grow at a 9.56% CAGR through 2031. Mid-tier models are increasingly using lithium-iron-phosphate batteries instead of nickel-manganese-cobalt chemistries, offering a longer cycle life and lower costs, though with a slight reduction in energy density. The second-largest category, road and city bicycles, serves commuters who value speed and efficiency on paved roads. On the other hand, mountain and all-terrain models cater to recreational users in the Alpine and Nordic regions. Hybrid bicycles, which combine road and off-road features, were once popular among versatile riders. However, their market share is declining as e-bike motors remove the need for compromise. Riders can now choose specialized frames and rely on pedal assistance to handle diverse terrains. While cargo and recumbent models remain niche, they are growing rapidly, particularly in urban logistics.
As e-bicycles continue to dominate, traditional bicycle manufacturers without motor and battery integration capabilities are experiencing compressed margins. Companies like Bosch and Shimano demonstrate vertical integration, allowing component suppliers to capture value that previously belonged to frame builders. This trend is pressuring brands such as Canyon and Specialized to either develop proprietary electronics or face commoditization. The EU's Alternative Fuels Infrastructure Regulation, which requires workplace charging points, is removing a major barrier to e-bike adoption. This policy not only highlights a forward-thinking approach but also reverses traditional market dynamics, with policy now outpacing consumer demand.
In 2025, regular-design bicycles accounted for 83.35% of the market. However, folding variants are experiencing rapid growth, with a 10.21% CAGR projected for 2026-2031, making them the fastest-growing segment. Brompton's G Line, launched in 2024, highlights the evolving perception of folding models. Featuring 20-inch wheels, 8-speed gearing, and hydraulic disc brakes, these bicycles are now competing on performance rather than being seen solely as utilitarian. Similarly, the Electric P Line, equipped with a lightweight titanium frame weighing 15.6 kilograms, underwent 8 years of in-house research and development to achieve UL2849 certification. This achievement reflects stricter safety standards, which are raising entry barriers for low-cost competitors. Folding bicycles are particularly effective for intermodal commuting, such as transitioning from train to office or car to trail. This advantage explains their significant growth in densely populated cities like London, Paris, and Berlin, where extensive public transit systems often leave last-mile gaps.
Regular designs maintain their dominance due to superior ride quality, component compatibility, and higher resale value. Enthusiasts and long-distance commuters prioritize frame stiffness and wheel size over portability, ensuring continued demand for traditional geometries. The key insight is that folding bicycles are not replacing regular models but are instead establishing a parallel category. They cater to urban professionals who integrate cycling with public transit rather than competing directly. Manufacturers should avoid positioning folding bikes as universal solutions and instead focus on targeting specific commuter profiles with tailored marketing and distribution strategies.
Complete Report Scope:
- By Product Type
- Road/City
- Mountain/All-Terrain
- Hybrid
- E-Bicycle
- Other Types
- By Design
- Regular
- Folding
- By End-User
- Men
- Women
- Children
- By Distribution Channel
- Offline Retail Stores
- Online Retail Stores
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Sweden
- Belgium
- Poland
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Accell Group NV
- Trek Bicycle Corporation
- Pon Holdings BV
- Giant Manufacturing Co. Ltd
- Scott Sports SA
- Merida Industry Co. Ltd
- Riese and Muller GmbH
- Canyon Bicycles GmbH
- Decathlon SA
- Bosch eBike Systems (Robert Bosch GmbH)
- Shimano Inc.
- VanMoof BV
- Orbea S. Coop.
- KTM Fahrrad GmbH
- myStromer AG
- Bianchi S.p.A.
- Bulls Bikes (ZEG eG)
- Ribble Cycles
- Simplon Fahrrad GmbH
- Specialized Bicycle Components Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing traffic congestion in urban areas is leading to higher adoption of bicycles for daily commuting.
- 4.2.2 Growing awareness of health and fitness is driving a rise in cycling activities.
- 4.2.3 Government efforts to promote sustainable transportation are encouraging bicycle usage.
- 4.2.4 Rising environmental consciousness and sustainability goals are boosting bicycle adoption.
- 4.2.5 Corporate wellness initiatives are fostering greater use of bicycles among employees.
- 4.2.6 Escalating fuel prices are positioning bicycles as an economical mode of transportation.
- 4.3 Market Restraints
- 4.3.1 Alternative transportation options such as motorcycles and rapid transit systems reduce bicycle adoption rates
- 4.3.2 Elevated prices of electric bicycles limit widespread consumer acceptance across regions
- 4.3.3 Proliferation of fake bicycle products negatively impacts market expansion
- 4.3.4 Inadequate road infrastructure in rural regions affects bicycle riding experience
- 4.4 Consumer Behaviour Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Product Type
- 5.1.1 Road/City
- 5.1.2 Mountain/All-Terrain
- 5.1.3 Hybrid
- 5.1.4 E-Bicycle
- 5.1.5 Other Types
- 5.2 By Design
- 5.2.1 Regular
- 5.2.2 Folding
- 5.3 By End-User
- 5.3.1 Men
- 5.3.2 Women
- 5.3.3 Children
- 5.4 By Distribution Channel
- 5.4.1 Offline Retail Stores
- 5.4.2 Online Retail Stores
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Russia
- 5.5.7 Sweden
- 5.5.8 Belgium
- 5.5.9 Poland
- 5.5.10 Netherlands
- 5.5.11 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accell Group NV
- 6.4.2 Trek Bicycle Corporation
- 6.4.3 Pon Holdings BV
- 6.4.4 Giant Manufacturing Co. Ltd
- 6.4.5 Scott Sports SA
- 6.4.6 Merida Industry Co. Ltd
- 6.4.7 Riese and Muller GmbH
- 6.4.8 Canyon Bicycles GmbH
- 6.4.9 Decathlon SA
- 6.4.10 Bosch eBike Systems (Robert Bosch GmbH)
- 6.4.11 Shimano Inc.
- 6.4.12 VanMoof BV
- 6.4.13 Orbea S. Coop.
- 6.4.14 KTM Fahrrad GmbH
- 6.4.15 myStromer AG
- 6.4.16 Bianchi S.p.A.
- 6.4.17 Bulls Bikes (ZEG eG)
- 6.4.18 Ribble Cycles
- 6.4.19 Simplon Fahrrad GmbH
- 6.4.20 Specialized Bicycle Components Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

 北美自行車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)自行車:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 自行車市場-2026-2032年全球市場預測自行車及騎乘裝備市場:2026-2032年全球市場預測(產品類型、自行車類型、車架材料、煞車類型、應用、最終用戶、客戶類型、分銷管道和安裝方式分類)
 2026年全球自行車市場報告
 2026-2030年全球自行車市場
 自行車市場規模、佔有率、趨勢和預測:按類型、技術、價格、銷售管道、最終用戶和地區分類,2026-2034 年
 自行車裝備市場規模、佔有率、成長、全球產業分析、區域洞察及2026-2034年預測。
 自行車市場報告:趨勢、預測和競爭分析(至2035年)
 自行車市場機會、成長要素促進因素、產業趨勢分析及2026-2035年預測。