


 |
市場調查報告書
商品編碼
2122888
電子書:市佔率分析、產業趨勢與統計、成長預測(2026-2031)E-book - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
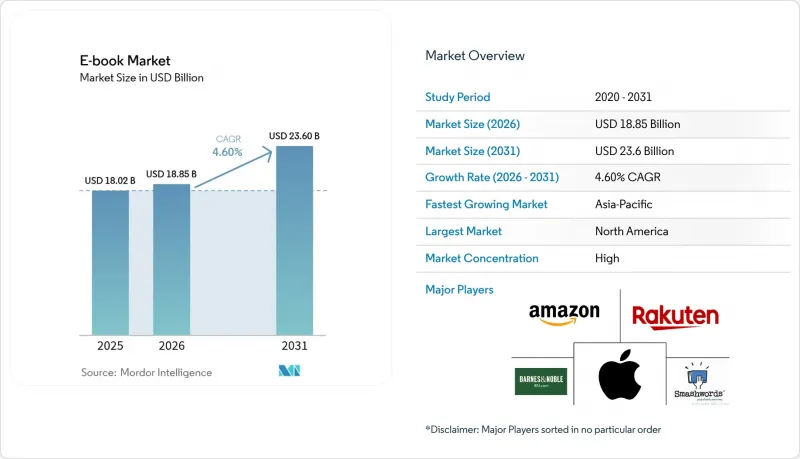
預計電子書市場將從 2025 年的 180.2 億美元成長到 2026 年的 188.5 億美元,然後在 2031 年達到 236 億美元,2026 年至 2031 年的複合年成長率為 4.6%。
本報告按收入模式(訂閱、下載收費、免費增值/廣告、機構授權)、類型(小說、非小說、教育/學術、漫畫/圖像小說、專業/技術書籍)、最終用戶(個人消費者、機構)和地區進行細分。市場預測以美元計價。
全球電子書市場趨勢與洞察
行動裝置的廣泛普及
隨著智慧型手機的日益普及,數位閱讀的重心正從專用電子閱讀器轉向始終線上連網裝置。出版商正利用這一趨勢,透過分發短篇故事章節、最佳化垂直滾動體驗以及融入遊戲化元素來強化日常閱讀習慣。顯示器製造商正在改進OLED螢幕,使其具備防反射特性和自適應更新率,以減少長時間閱讀造成的眼部疲勞。人工智慧建議引擎的興起進一步提升了應用程式內內容發現的個人化程度,提高了閱讀完成率和平均每次閱讀時長。在設備更換週期較短的亞太地區,閱讀應用程式如今已預先安裝在高階設備上,使其成為進入電子書市場的預設入口。
全球網路連線擴展
新一代寬頻的部署和對5G回程傳輸的投資正在擴大先前受頻寬連線將使出版商能夠整合高解析度插圖、音訊片段和短影片,而不會造成無法接受的載入時間。基於區域頻寬品質的動態定價也越來越普遍。使用較慢網路的讀者可以選擇價格更低、比特率更低的套餐,在考慮基礎設施實際情況的同時確保可訪問性。此外,網路連接的改善消除了雲端同步的障礙,從而可以在多個裝置上無縫追蹤閱讀進度。
電子書經銷商和作者之間的隱私和版權問題
圍繞數位版權管理和數據使用的複雜問題有可能使發行生態系統分崩離析。歐洲監管機構正在根據《一般資料保護規範》(GDPR)實施處罰,這可能會使那些努力維持合規基礎設施的小規模出版商損失超過其年度數位收入的10%。有關受控數位借閱的訴訟凸顯了合理使用界限方面仍然存在的模糊性,這導致機構採購決策延遲,並透過圖書館管道抑制了電子書市場的短期成長。作者們越來越質疑人工智慧公司是否在未經同意的情況下抓取全文,而像約翰霍普金斯大學出版社這樣的早期採用者則被敦促制定清晰的人工智慧授權框架,以確保模型訓練獲得回報。具有遠見的出版商正在探索基於區塊鏈的內容交易時間戳技術,透過記錄每個副本的訪問時間、地點和方式,提高透明度和可審計性。
細分市場分析
預計到2025年,訂閱服務將佔電子書收入的55.72%,並將繼續成為推動電子書市場擴張的主要動力。這些數據豐富的環境正被用於新系列的演算法規劃,確保書籍能精準送達預先選定的讀者群。機構授權(主要面向圖書館和企業培訓入口網站)的成長速度最快,複合年成長率達5.05%,這主要得益於較高的單一用戶支出。儘管機構授權用戶數量仍小於消費者訂閱用戶數量,但這一成長趨勢已顯著擴大了電子書市場的規模。對於需要永久存取權限的學術專著和專業教材而言,按下載量收費模式仍然普遍存在;而在對成本較為敏感的地區,諸如廣告位變現和社交媒體共用後解鎖章節等免費增值模式正逐漸興起。
出版商正圍繞著「內容即服務」建立工作流程,透過即時校對和添加多媒體內容來更新其數位書目。這種延長的生命週期有助於穩定收入確認,並增強書目永續性。對平台而言,訂閱解約率管理已成為一門科學。預測分析能夠識別參與度下降的讀者,並在流失風險達到高峰之前推送精心策劃的通知和忠誠度獎勵。整合的支付系統簡化了套餐升級流程,並引導忠實讀者升級到包含有聲讀物和圖文內容的付費方案。這些舉措強化了一個良性循環:用戶參與度的提高帶動了訂閱電子書市場佔有率的逐年成長。
區域分析
北美地區憑藉其成熟的電子閱讀器使用習慣、高寬頻普及率以及龐大的圖書館和學術機構採購生態系統,預計到2025年將保持39.45%的市場佔有率。各大平台正投資開發人工智慧輔助閱讀工具,這些工具能夠即時概括章節內容並翻譯文本,從而提升時間緊迫的商務人士的使用體驗。儘管監管機構對平台壟斷行為的調查尚未導致結構性糾正措施,但這些調查正在遏制平台的收購策略,並迫使現有公司將重心從積極收購內容轉向以客戶為中心的功能升級。
亞太地區預計將成為成長最快的地區,到2031年將以4.72%的複合年成長率持續成長,這主要得益於智慧型手機的普及和靈活的行動支付系統的推動。自2020年以來,日本數位漫畫的銷量加倍,而韓國網路漫畫則透過改編成電視劇和遊戲,提升了其IP的價值,吸引消費者回歸原作。據GSMA稱,新加坡、韓國和澳洲的5G網路覆蓋率接近100%,為頻寬密集型互動電子書創造了有利條件。東南亞的新創公司正在嘗試“分段定價”,以幾美分的價格出售章節,從而拓寬價格區間,重振電子書市場。
在歐洲,受機構強制數位化和跨境內容監管的推動,出版業呈現穩定成長態勢。 GDPR合規性在提升訂閱轉換率的同時,也增強了消費者信任,並帶來了成本高昂的資料處理安全措施。隨著對多語言支援需求的不斷成長,出版商正加速投資人工智慧翻譯流程,以縮短在地化前置作業時間。在德國和荷蘭,基於區塊鏈的先導計畫正在實施,旨在測試更透明的版稅支付方式,將支付週期從數月縮短至數天。同時,英國正應對脫歐後複雜的授權問題,並利用其強大的獨立出版業,嘗試整合客製印刷附加服務的「直接面向讀者捆綁銷售」模式。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 行動裝置普及率不斷提高
- 全球網路連線擴展
- 數位教育和數位學習的發展
- 訂閱式閱讀平台的擴張
- 基於區塊鏈的版權管理和微支付
- 出版商整合D2C店面和CRM數據
- 市場限制因素
- 電子書經銷商和作者之間的隱私和版權問題
- 新興市場對紙本書的強烈偏好
- 電子閱讀器生態系間互通性的局限性
- 「數位疲勞」正在推動人們減少螢幕使用時間。
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按收入模式
- 定期訂閱(無限閱讀)
- 下載收費
- 免費增值/廣告收入模式
- 機構許可
- 按類型
- 小說
- 非虛構類
- 教育和學術
- 漫畫和圖像小說
- 專業/技術領域
- 最終用戶
- 個人消費者
- 成人
- 兒童和青少年
- 機構
- K-12教育機構
- 高等教育
- 企業/專業培訓
- 公共圖書館
- 個人消費者
- 按地區
- 北美洲
- 美國
- 加拿大
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 印尼
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amazon.com, Inc.
- Rakuten Kobo Inc.
- Apple Inc.
- Barnes and Noble, LLC
- Smashwords, Inc.
- Blurb, Inc.
- DIY Media Group, Inc.
- Lulu Press, Inc.
- Macmillan Publishers Ltd
- Scribd, Inc.
- Google LLC
- Hachette Livre SA
- HarperCollins Publishers LLC
- Penguin Random House LLC
- Draft2Digital, LLC
- OverDrive, Inc.
- Storytel AB
- Wattpad Corp.
- Inkitt GmbH
- John Wiley and Sons, Inc.
- Pearson plc
- Cengage Learning, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the e-book market size is expected to grow from USD 18.02 billion in 2025 to USD 18.85 billion in 2026 and is forecast to reach USD 23.6 billion by 2031 at 4.6% CAGR over 2026-2031.
This report is Segmented by Revenue Model (Subscription, Pay-Per-Download, Freemium/Ad-supported, and Institutional Licensing), Genre (Fiction, Non-Fiction, Education and Academic, Comics and Graphic Novels, and Professional and Technical), End-User (Individual Consumers, and Institutional), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global E-book Market Trends and Insights
Increasing Penetration of Mobile Devices
Smartphone saturation has shifted the center of gravity for digital reading away from dedicated e-readers and toward always-connected handsets. Publishers capitalize on this reality by releasing bite-sized content episodes, optimizing for vertical scrolling, and layering in gamified achievements that reinforce daily reading streaks. Display manufacturers are refining glare-free OLED screens and adaptive refresh rates that reduce eye strain during extended reading sessions. The rise of AI-driven recommendation engines further personalizes in-app discovery, boosting completion rates and average reading time per session. In Asia Pacific, where handset upgrades occur on rapid cycles, premium devices now ship with pre-installed reading apps that create a default pathway into the e-book market.
Expanding Global Internet Connectivity
Next-generation broadband rollouts and 5G backhaul investments expand addressable audiences in markets historically constrained by bandwidth cost. GSMA's Digital Nations framework shows 18 Asia Pacific governments prioritizing ubiquitous coverage as a pillar of economic competitiveness. Faster, cheaper connections enable publishers to embed high-resolution artwork, audio snippets, and short-form video without incurring intolerable load times. Dynamic pricing tied to regional bandwidth quality is also gaining traction: readers on slower networks can opt for lower-bitrate packages at reduced prices, preserving accessibility while respecting infrastructure realities. Enhanced connectivity likewise removes frictions for cloud synchronization, ensuring seamless progress tracking across multiple devices.
Privacy and Copyright Issues Among E-sellers and Authors
Complexities around digital rights management and data usage threaten to fragment distribution ecosystems. European regulators enforce GDPR penalties that can absorb more than 10% of annual digital revenue for small presses struggling to maintain compliant infrastructure. Controlled digital lending lawsuits underscore lingering ambiguity over fair-use boundaries, delaying institutional purchasing decisions and depressing near-term e-book market growth in library channels. Authors increasingly question whether AI companies scrape full texts without consent, prompting early adopters like Johns Hopkins University Press to craft explicit AI licensing frameworks that guarantee compensation for model training. Forward-looking publishers explore blockchain timestamping of content transactions to record when, where, and how each copy is accessed, enhancing transparency and auditability.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Digital Education and E-learning
- Rising Adoption of Subscription-Based Reading Platforms
- Persistent Preference for Print Books in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Subscription services commanded 55.72% of 2025 revenue and remain the engine behind the e-book market expansion. Their data-rich environments inform algorithmic commissioning of new series, ensuring that titles debut with pre-qualified audiences. Institutional licensing, chiefly libraries and corporate training portals, shows the sharpest momentum, growing at 5.05% CAGR on a base of high per-user spending. That uptrend contributes meaningfully to the e-book market size even though its user count trails consumer subscriptions. Pay-per-download persists for academic monographs and professional references where perpetual access is mandatory, while freemium models gain traction in cost-sensitive territories by monetizing advertising inventory or unlocking chapters after social sharing actions.
Publishers are engineering workflows around "content-as-a-service," refreshing digital backlists with real-time errata fixes and multimedia add-ons. This lifecycle extension smooths revenue recognition and strengthens catalog durability. For platforms, subscription churn management has become a science: predictive analytics flag disengaging readers so that curated push notifications or loyalty rewards arrive before cancellation risk peaks. Integrated payment rails simplify tier upgrades, nudging heavy readers toward premium plans that bundle audiobooks or graphic content. These measures reinforce a virtuous loop wherein higher engagement elevates the e-book market share of subscription formats year over year.
Complete Report Scope:
- By Revenue Model
- Subscription (all-you-can-read)
- Pay-per-download
- Freemium / Ad-supported
- Institutional licensing
- By Genre
- Fiction
- Non-fiction
- Education and Academic
- Comics and Graphic Novels
- Professional and Technical
- By End-user
- Individual Consumers
- Adults
- Children and Young Adults
- Institutional
- K-12 Schools
- Higher Education
- Corporate / Professional Training
- Public Libraries
- Individual Consumers
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained its 39.45% share in 2025 owing to entrenched e-reader habits, high broadband penetration, and a dense ecosystem of library and academic buyers. Leading platforms invest in AI-generated reading companions that summarize chapters and translate passages on the fly, raising engagement among time-pressed professionals. Regulatory inquiries into platform exclusivity have not yet produced structural remedies, but they do temper acquisition strategies, pushing incumbents to focus on customer-centric feature upgrades rather than aggressive content hoarding.
Asia Pacific charts the fastest regional expansion at a 4.72% CAGR through 2031, propelled by smartphone ubiquity and flexible mobile payment systems. Japanese digital manga revenue has doubled since 2020, while Korean webtoons add recurring IP value thanks to drama and gaming adaptations that rebound consumers back into source titles. GSMA notes that Singapore, South Korea, and Australia achieve near-total 5G coverage, creating fertile ground for bandwidth-heavy interactive books. South-East Asian start-ups experiment with sachet-pricing, selling single chapters for cents, thereby broadening affordability and bolstering the e-book market.
Europe grows steadily on the back of institutional digitization mandates and cross-border content regulation. GDPR compliance engenders consumer trust, elevating subscription conversion rates though it imposes costly data-handling safeguards. Multilingual requirements spur publishers to invest in AI-translation pipelines that reduce localization timelines. Blockchain pilots in Germany and the Netherlands test transparent royalty disbursement, aiming to shorten payment cycles from months to days. In parallel, the UK navigates post-Brexit licensing complexities, leveraging its robust independent press scene to experiment with direct-to-reader bundles that integrate print-on-demand add-ons.
- Amazon.com, Inc.
- Rakuten Kobo Inc.
- Apple Inc.
- Barnes and Noble, LLC
- Smashwords, Inc.
- Blurb, Inc.
- DIY Media Group, Inc.
- Lulu Press, Inc.
- Macmillan Publishers Ltd
- Scribd, Inc.
- Google LLC
- Hachette Livre SA
- HarperCollins Publishers LLC
- Penguin Random House LLC
- Draft2Digital, LLC
- OverDrive, Inc.
- Storytel AB
- Wattpad Corp.
- Inkitt GmbH
- John Wiley and Sons, Inc.
- Pearson plc
- Cengage Learning, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing penetration of mobile devices
- 4.2.2 Expanding global internet connectivity
- 4.2.3 Growth of digital education and e-learning
- 4.2.4 Rising adoption of subscription-based reading platforms
- 4.2.5 Blockchain-enabled rights management and micropayments
- 4.2.6 Publisher D2C storefront integration with CRM data
- 4.3 Market Restraints
- 4.3.1 Privacy and copyright issues among e-sellers and authors
- 4.3.2 Persistent preference for print books in emerging markets
- 4.3.3 Interoperability limitations across e-reader ecosystems
- 4.3.4 Digital fatigue driving screen-time reduction initiatives
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Revenue Model
- 5.1.1 Subscription (all-you-can-read)
- 5.1.2 Pay-per-download
- 5.1.3 Freemium / Ad-supported
- 5.1.4 Institutional licensing
- 5.2 By Genre
- 5.2.1 Fiction
- 5.2.2 Non-fiction
- 5.2.3 Education and Academic
- 5.2.4 Comics and Graphic Novels
- 5.2.5 Professional and Technical
- 5.3 By End-user
- 5.3.1 Individual Consumers
- 5.3.1.1 Adults
- 5.3.1.2 Children and Young Adults
- 5.3.2 Institutional
- 5.3.2.1 K-12 Schools
- 5.3.2.2 Higher Education
- 5.3.2.3 Corporate / Professional Training
- 5.3.2.4 Public Libraries
- 5.3.1 Individual Consumers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Indonesia
- 5.4.4.6 Rest of Asia Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Egypt
- 5.4.5.2.4 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amazon.com, Inc.
- 6.4.2 Rakuten Kobo Inc.
- 6.4.3 Apple Inc.
- 6.4.4 Barnes and Noble, LLC
- 6.4.5 Smashwords, Inc.
- 6.4.6 Blurb, Inc.
- 6.4.7 DIY Media Group, Inc.
- 6.4.8 Lulu Press, Inc.
- 6.4.9 Macmillan Publishers Ltd
- 6.4.10 Scribd, Inc.
- 6.4.11 Google LLC
- 6.4.12 Hachette Livre SA
- 6.4.13 HarperCollins Publishers LLC
- 6.4.14 Penguin Random House LLC
- 6.4.15 Draft2Digital, LLC
- 6.4.16 OverDrive, Inc.
- 6.4.17 Storytel AB
- 6.4.18 Wattpad Corp.
- 6.4.19 Inkitt GmbH
- 6.4.20 John Wiley and Sons, Inc.
- 6.4.21 Pearson plc
- 6.4.22 Cengage Learning, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 電子書閱讀器:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)歐洲電子書:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 電子書閱讀器市場-2026-2032年全球市場預測電子書市場:2026-2032年全球市場預測(按類型、文件格式、設備、定價模式、年齡層、最終用戶和通路分類)
 全球線上圖書服務市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 美國自助出版市場規模、佔有率和趨勢分析報告:按類型、格式、主要參與者、競爭分析和細分市場預測(2026-2033 年)
 線上圖書服務市場-全球產業規模、佔有率、趨勢、機會與預測:按產品、應用、地區和競爭對手分類,2021-2031年
 電子閱讀器市場報告:按螢幕類型、螢幕大小、連接方式、價格範圍、最終用戶、分銷管道和地區分類(2026-2034 年)
 2026年全球電子閱讀器市場報告2026年全球線上圖書服務市場報告