


 |
市場調查報告書
商品編碼
2122670
印刷感測器:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Printed Sensor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,列印感測器市場規模將從 2025 年的 121 億美元成長到 2026 年的 129.2 億美元,然後在 2031 年達到 178.9 億美元,2026 年至 2031 年的複合年成長率為 6.74%。
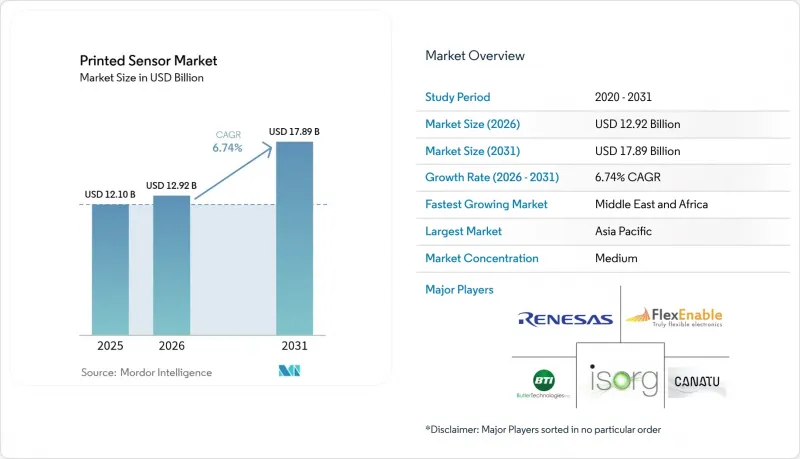
本報告按感測器類型(觸控/電容式、溫度感測器等)、印刷技術(網版印刷、噴墨印刷等)、基材(塑膠薄膜(PET、PEN)、紙張和紙板等)、最終用戶(家用電子電器、醫療保健和醫療設備等)以及地區進行細分。市場預測以價值(美元)表示。
全球列印感測器市場趨勢與洞察
軟性穿戴醫療設備的快速普及
在亞太地區的醫療保健系統中,遠端監測計畫正在擴展,推動了對可舒適地貼附於皮膚或織物上的生物感測器的需求。目前,基於汗液的平台無需穿刺即可測量發炎標記、水分含量和血糖值。軟性混合電子裝置 (FHE) 整合了印刷陣列和矽邏輯電路,形成貼片,並透過藍牙將即時生命徵象傳輸至醫院的儀表板。預計到 2030 年,這項功能將推動 FHE 市場規模超過 670 億美元。醫院網路正在利用這些連續的數據流來縮短住院時間並及早發現併發症。由於單價低於 3 美元,即使是中等收入的醫療機構也能負擔得起為術後出院患者佩戴這些設備,從而加速了該地區的普及。日本、韓國和中國的監管機構已正式推出穿戴式診斷設備的快速核准程序,進一步促進了銷售。
汽車產業向曲面人機互動儀錶板的過渡
全球汽車製造商正用光滑的觸控面板取代機械旋鈕,這些面板能夠完美貼合內裝的曲線。 KURZ 的「PolyTC®」金屬網電容層採用捲對卷工藝模壓在 PET 基材上,即使隔著 2.5 毫米厚的裝飾塑膠也能檢測到觸摸,滿足 OEM 的設計要求。這些感測器經認證可承受 85 度C和 40 度C的循環溫度,在車輛的整個使用壽命期間保持靈敏的反應。一級供應商還將印刷在方向盤和扶手中的感測器陣列整合到車輛中,以檢測駕駛員的操作並相應地調整安全氣囊和警報系統。軟體定義駕駛座平台利用統一的感測器網格,支援空中下載 (OTA) 升級,無需更換硬體即可更新控制佈局。雖然目前歐洲和北美主導這項技術的應用,但中國電動車品牌正在迎頭趕上,並計劃在 2026 年推出整合式電容面板。
缺乏標準化的測試方案
可拉伸生物感測器會根據人體運動而彎曲、扭轉和壓縮,而傳統的IEC 60601衝擊和振動測試無法涵蓋這些行為。每個品牌都需要開發自己的拉伸性、耐洗滌性和皮膚接觸生物相容性測試系統,這導致設計週期延長。 UL Solutions正在應對因產品類別和地區而異的CE、FDA和IEC要求所帶來的複雜局面。產業組織正在製定通用的負載工況矩陣,但由於每種產品(例如步態監測器、新生兒貼片和智慧運動服)都表現出獨特的應變模式,因此尚未達成一致。認證延遲增加了營運資金需求,阻礙了中小企業進入市場,並限制了短期市場滲透。
細分市場分析
預計到2025年,觸控/電容式感測器將佔據31.12%的列印感測器市場佔有率,成為該市場的主要驅動力。其主導地位主要歸功於其在智慧型手機、筆記型電腦和資訊娛樂顯示器等各種應用中的廣泛應用。生物感測器目前規模較小,但隨著醫院轉向持續的院外評估,其複合年成長率(CAGR)正以11.45%的速度成長。這一趨勢主要得益於奈米酶化學技術,該技術能夠對乳酸、葡萄糖和感染標記進行非侵入性檢測。加拿大和德國遠端患者監護報銷方案的監管批准正在擴大目標市場規模。氣體/化學、溫度、壓力/力以及壓電/應變感測器在安全、電池組和結構完整性等領域發揮著重要作用,而諸如122 ppb氨氣檢測等突破性技術則催生了新的合規性解決方案。整合式多模態堆疊將觸控、壓力和生物識別結合到一個堆疊中,而不會增加面積,並且擴大被應用於空間受限的設計中,例如智慧戒指和耳機。
成本低於10美元的生物感測器貼片正在推動東南亞各地診所進行大規模篩檢項目,並改善慢性病追蹤。印製在TPU薄膜上的壓力陣列可將力數據提供給人工智慧步態分析引擎,用於檢測養老機構的跌倒風險。嵌入鋰離子電池模組的氣體感測器可提供早期氣體洩漏警報,幫助包裝製造商遵守聯合國38.3安全法規。織入工廠傳送帶的壓電線可偵測應變,使預測性維護軟體能夠在災難性故障發生前安排停機時間。這種功能的多樣性使供應商能夠保持靈活性。由於定製油墨的化學成分、基板選擇和電極形狀因專案而異,因此需要實施模組化生產工具包。
絲網印刷預計到2025年將佔銷售額的41.55%,這得益於其成熟的產能、厚膜沉積能力以及陶瓷和PCB行業數十年來積累的設備成本。約100µm的標準線寬可滿足大多數電容式和電阻式元件的需求,而網孔技術的改進已將解析度提升至近50µm。噴墨印刷對於設計每週都在變化的小批量生產仍然至關重要,它使品牌能夠快速調整方向而無需製作新的網版。氣溶膠噴射、動態噴射和MEMS微噴嘴陣列透過在3D輪廓上沉積小於10µm的線路,實現了13.25%的最高複合年成長率,使其成為在機殼內蜿蜒佈置的天線和電池內部細間距溫度柵格的理想選擇。
柔版印刷機在處理數百公尺長的長度以及對色彩匹配精度要求極高的應用領域表現卓越。凹版印刷則更適合在光學清晰度至關重要的應用中實現均勻的奈米級厚度塗層,例如抬頭顯示器(HUD) 擋風玻璃上的透明加熱器。混合式生產線融合了多種技術:噴墨印刷用於底層,雷射燒結用於銅沉積,絲網塗佈用於保護性介電面塗層。這種選擇決定了成本、特徵密度和可靠性,因此一級製造商擴大在同一地點安裝多台設備。新興的人工智慧視覺系統能夠即時調整刮刀角度和噴嘴停留時間,以保持精確度,從而將良率提升至 98% 以上。
區域分析
到2025年,亞太地區將佔據全球印刷感測器市場39.05%的佔有率,主要得益於中國大規模的產能、日本深厚的材料科學實力以及韓國的顯示器巨頭。當地的研發聯盟正迅速將突破性的實驗室成果轉化為中試生產線,縮短了從概念到出口的週期。政府津貼抵銷了用於OLED觸控矩陣的新型凹版印刷機的折舊免稅額成本,同時,各大學也紛紛孵化出專注於醫院穿戴式裝置的新創公司。該地區的開發平臺還包括嵌入紡織品的折疊式感測器和用於電子紙閱讀器的可折疊觸控薄膜,從而拓展了智慧型手機以外的收入來源。
在北美,《晶片與科學法案》(CHIPS & Science Act)正在發揮作用,該法案撥款用於印刷電子測試平台,並幫助晶圓廠克服高昂的資本投入。材料供應商與航太巨頭合作,正在生產厚度僅25微米的壓力感測器陣列,用於測量機翼偏轉,同時又不影響空氣動力性能。醫療保健生態系統正在推動這項技術的應用,診所正在進行由聯邦醫療保險(Medicare)報銷的家庭監測試點項目,以驗證生物感測器貼片的商業可行性。波士頓和矽谷的研究中心正在不斷改進與熱敏熱塑性塑膠相容且可在70 度C下燒結的油墨配方。
中東地區展現最高的成長速度,預計2031年年複合成長率(CAGR)將達到9.18%,主要得益於海灣國家將石油收入投入智慧城市建設。杜拜的2020號地鐵線路正在軌道上安裝印刷應變計,用於預測性維護;而利雅德的一個大型專案則在整個施工現場部署了空氣品質測量陣列,以滿足新的環保標準。由外國公司組成的合資企業在傑貝阿里附近建立了一條卷對卷生產線,利用免稅區向歐洲和非洲市場供應產品。歐洲也維持著強勁的發展基礎,尤其是德國的第一線企業正在不斷改進其曲面人機介面(HMI)面板的製造技術。歐盟的「歐洲晶片」舉措正在為半導體產能(包括軟性混合晶片)增加79億歐元的投資,為長期競爭力奠定基礎。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場促進因素
- 亞太地區軟性穿戴醫療設備的快速普及
- 汽車產業向曲面人機互動儀表板的轉變需要大面積電容式印刷感測器。
- 智慧工廠中從機械式氣體檢測技術向半導體式氣體檢測技術的過渡(歐洲主導)
- 採用卷對卷製程製造MEMS在大規模生產的消費性物聯網節點中具有成本優勢。
- 市場限制因素
- 汽車熱循環條件下導電油墨長期穩定性的限制。
- 可拉伸生物感測器缺乏標準化的測試規程,導致OEM認證延遲。
- 將現有PCB生產線改造為卷對卷混合生產線需要投入大量資金。
- PEDOT:與PSS配方相關的智慧財產權分散是導致專利費增加的因素。
- 價值供應鏈分析
- 監理展望
- 技術展望
- 波特五力分析
- 技術概述
- 噴墨列印
- 網版印刷
- 柔版印刷
- 凹版印刷
- 氣溶膠噴射和其他新興技術
- 投資分析
- 創業投資(VC)資金籌措趨勢
- 併購趨勢
第5章 市場規模與成長預測
- 依感測器類型
- 觸控/電容式
- 壓力/力
- 生物感測器
- 氣體/化學品
- 壓電/失真
- 溫度
- 透過印刷技術
- 螢幕
- 噴墨
- 柔版印刷
- 凹版印刷
- 氣溶膠噴射器和其他
- 按基礎材料
- 塑膠薄膜(PET、PEN)
- 紙張和紙板
- 玻璃
- 纖維和彈性體
- 最終用戶
- 家用電子產品
- 醫療保健和醫療設備
- 工業和製造業
- 汽車和運輸業
- 航太/國防
- 其他(智慧包裝、農業)
- 按地區
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 南美洲
- 巴西
- 其他南美國家
- 中東
- GCC
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 策略趨勢
- Partnerships and Licensing
- Capacity Expansions
- 市佔率分析
- 公司簡介
- FlexEnable Ltd.
- ISORG SA
- Plastic Logic HK Ltd.
- Renesas Electronics Corp.
- Butler Technologies Inc.
- Canatu Oy
- SPEC Sensors LLC
- Peratech Holdco Ltd.
- Pressure Profile Systems Inc.
- Tekscan Inc.
- Thin Film Electronics ASA
- Molex LLC
- Interlink Electronics Inc.
- Fujifilm Dimatix Inc.
- Heraeus Noblelight GmbH
- Nissha Co. Ltd.
- T+Ink Inc.
- GSI Technologies LLC
- Brewer Science Inc.
- Henkel AG and Co. KGaA
第7章 市場機會與未來展望
According to Mordor Intelligence, the printed sensor market size is expected to grow from USD 12.1 billion in 2025 to USD 12.92 billion in 2026 and is forecast to reach USD 17.89 billion by 2031 at 6.74% CAGR over 2026-2031.
This report is Segmented by Sensor Type (Touch / Capacitive, Temperature, and More), Printing Technology (Screen, Inkjet, and More), Substrate (Plastic Films (PET, PEN), Paper and Paperboard, and More), End-User (Consumer Electronics, Healthcare and Medical Devices, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Printed Sensor Market Trends and Insights
Rapid Adoption of Flexible & Wearable Medical Devices
Asia-Pacific healthcare systems are scaling remote monitoring programs, elevating demand for biosensors that wrap comfortably around skin and textiles. Sweat-based platforms now profile inflammation markers, hydration, and glucose without puncturing the body. Flexible hybrid electronics integrate printed arrays with silicon logic, forming patches that relay real-time vitals over Bluetooth to hospital dashboards, a capability forecast to lift the FHE market past USD 67 billion by 2030. Hospital networks use these continuous data streams to shorten inpatient stays and flag complications early. With unit prices falling under USD 3, even mid-income providers can equip postoperative patients at discharge, accelerating regional adoption. Regulatory bodies in Japan, Korea, and China are formalizing fast-track approvals for wearable diagnostics, further supporting volume growth.
Automotive Shift to Curved HMI Dashboards
Global automakers are replacing mechanical knobs with sweeping touch surfaces that follow interior contours. PolyTC(R) metal-mesh capacitive layers from KURZ are deposited on PET using roll-to-roll lines and still register touch through 2.5 mm of decorative plastic, satisfying OEM styling goals. These sensors survive the 85 °C heat and 40 °C cold of qualification cycles, preserving responsiveness over vehicle life. Tier-1s are also embedding printed arrays into steering wheels and armrests to detect driver engagement and adjust airbags or alerts accordingly. Software-defined cockpit platforms capitalize on the uniform sensor grid, allowing over-the-air upgrades that refresh control layouts without hardware swaps. Europe and North America lead deployments today, but Chinese EV brands are close behind with fully moulded capacitive panels slated for 2026 launches.
Lack of Standardized Test Protocols
Stretchable biosensors bend, twist, and compress with the body, behaviours not covered by legacy IEC 60601 shock or vibration tests. Brands must invent in-house regimes for elongation, wash durability, and skin-contact biocompatibility, slowing design cycles. UL Solutions summarises the maze of CE, FDA, and IEC requirements that differ by product class and geography. Industry groups are drafting common load-case matrices, yet consensus remains elusive because gait monitors, neonatal patches, and smart jerseys all experience unique strain patterns. Qualification delays raise working capital needs and dissuade smaller entrants, capping near-term market penetration.
Other drivers and restraints analyzed in the detailed report include:
- Transition to Solid-State Gas Detection
- Roll-to-Roll Cost Advantage in IoT Applications
- Limited Stability Under Thermal Cycling
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Touch/Capacitive units led the printed sensor market with 31.12% share in 2025, a dominance tied to their ubiquity across phones, laptops, and infotainment displays. Biosensors, though smaller today, are growing at an 11.45% CAGR as hospitals shift to continuous assessment outside clinical walls. This wave is anchored by nanozyme chemistry that enables non-invasive detection of lactate, glucose, and infection markers. Regulatory green lights for remote patient monitoring refund schemes in Canada and Germany widen the addressable base. Gas/Chemical, Temperature, Pressure/Force, and Piezo/Strain categories fill niche roles in safety, battery packs, and structural health, with breakthroughs such as 122 ppb ammonia detection enabling new compliance solutions. Integrated multi-modal stacks combine touch, pressure, and biometrics in a single laminate without enlarging the footprint, winning space-constrained designs in smart rings and earbuds.
Biosensor patches priced under USD 10 encourage mass screening programs across Southeast-Asian clinics, improving chronic disease tracking. Pressure arrays printed on TPU film feed force data to AI gait engines that flag fall risk in elder-care homes. Gas sensors embedded inside lithium-ion modules offer early venting alerts, helping pack makers comply with UN 38.3 safety rules. Piezo threads woven into factory belts decode strain, letting predictive maintenance software schedule downtimes before catastrophic tears. This functional diversity keeps suppliers agile; custom ink chemistries, substrate picks, and electrode geometries shift from project to project, forcing a modular production toolkit.
Screen printing captured 41.55% of revenue in 2025, thanks to proven throughput, thick-film build-up, and equipment amortized over decades in ceramics and PCBs. Typical line widths around 100 µm satisfy most capacitive and resistive formats, while recent mesh upgrades push resolution nearer 50 µm. Inkjet retains relevance for short runs where designs evolve weekly; brands can pivot without fabricating new screens. Aerosol-Jet, electrohydrodynamic jets, and MEMS micro-nozzle arrays post the fastest 13.25% CAGR by depositing sub-10 µm tracks on 3D contours, perfect for antennas snaking around housings or fine-pitch temperature grids inside batteries.
Flexographic presses win when length hits hundreds of meters and colour registration is forgiving. Gravure excels at uniform nano-thick coatings where optical clarity matters, such as transparent heaters on HUD windshields. Hybrid lines mix methods: inkjet prints seed layers, laser sintering fuses copper, and screen coating applies protective dielectric topcoats. The choice shapes cost, feature density, and reliability, so tier-1s increasingly co-locate multiple machines. Emerging AI vision systems adjust squeegee angle and jet dwell time in real time to hold tolerance, lifting yield beyond 98%.
Complete Report Scope:
- By Sensor Type
- Touch/Capacitive
- Pressure / Force
- Biosensors
- Gas/Chemical
- Piezo/Strain
- Temperature
- By Printing Technology
- Screen
- Inkjet
- Flexographic
- Gravure
- Aerosol-Jet and Others
- By Substrate
- Plastic Films (PET, PEN)
- Paper and Paperboard
- Glass
- Textiles and Elastomers
- By End-User
- Consumer Electronics
- Healthcare and Medical Devices
- Industrial and Manufacturing
- Automotive and Transportation
- Aerospace and Defense
- Others (Smart Packaging, Agriculture)
- By Geography
- North America
- United States
- Canada
- Europe
- Germany
- France
- United Kingdom
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific commanded 39.05% of the printed sensor market in 2025, backed by China's large-scale production capacity, Japan's material science depth, and South Korea's display majors. Local R&D consortia turn lab breakthroughs into pilot lines fast, shortening the cycle from concept to export. Government grants offset depreciation on new gravure presses that print OLED touch matrices, while universities spin off start-ups targeting hospital wearables. The regional pipeline includes textile-integrated respiration sensors and foldable touch foils for e-paper readers, diversifying revenue beyond phones.
North America leverages the CHIPS & Science Act, which earmarked funds for printed electronics testbeds, helping fabs overcome high capex. Partnerships between material suppliers and aerospace primes produce pressure arrays as thin as 25 µm to measure wing flex without aerodynamic penalty. The healthcare ecosystem anchors adoption: clinics run at-home monitoring pilots reimbursed by Medicare, validating business cases for biosensor patches. Research centers in Boston and Silicon Valley iterate ink formulations that sinter at 70 °C, compatible with heat-sensitive thermoplastics.
The Middle East posts the swiftest 9.18% CAGR through 2031 as Gulf states channel oil revenue into smart city blueprints. Dubai's Route 2020 Metro deploys printed strain gauges on tracks for predictive maintenance, while Riyadh's giga projects embed air-quality arrays across construction sites to meet new environmental codes. Foreign joint ventures set up roll-to-roll lines near Jebel Ali, exploiting duty-free zones to serve Europe and Africa. Europe retains a strong foothold, notably Germany where Tier-1s refine curved HMI panels. The EU's Chips for Europe Initiative adds EUR 7.9 billion to semiconductor capacity including flexible hybrids, anchoring long-term competitiveness.
- FlexEnable Ltd.
- ISORG SA
- Plastic Logic HK Ltd.
- Renesas Electronics Corp.
- Butler Technologies Inc.
- Canatu Oy
- SPEC Sensors LLC
- Peratech Holdco Ltd.
- Pressure Profile Systems Inc.
- Tekscan Inc.
- Thin Film Electronics ASA
- Molex LLC
- Interlink Electronics Inc.
- Fujifilm Dimatix Inc.
- Heraeus Noblelight GmbH
- Nissha Co. Ltd.
- T+Ink Inc.
- GSI Technologies LLC
- Brewer Science Inc.
- Henkel AG and Co. KGaA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Drivers
- 4.1.1 Rapid adoption of flexible and wearable medical devices across Asia-Pacific
- 4.1.2 Automotive shift to curved HMI dashboards requiring large-area capacitive printed sensors
- 4.1.3 Transition from mechanical to solid-state gas detection in smart factories (Europe-led)
- 4.1.4 Roll-to-roll cost advantage versus MEMS in high-volume consumer IoT nodes
- 4.2 Market Restraints
- 4.2.1 Limited long-term stability of conductive inks under automotive thermal cycling
- 4.2.2 Lack of standardized test protocols for stretchable biosensors slows OEM qualification
- 4.2.3 Capital intensity of converting existing PCB lines to roll-to-roll hybrid lines
- 4.2.4 Intellectual-property fragmentation around PEDOT:PSS formulations driving royalty costs
- 4.3 Value / Supply-Chain Analysis
- 4.4 Regulatory Outlook
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Rivalry
- 4.7 Technology Snapshot
- 4.7.1 Inkjet Printing
- 4.7.2 Screen Printing
- 4.7.3 Flexographic Printing
- 4.7.4 Gravure Printing
- 4.7.5 Aerosol-Jet and Other Emerging Methods
- 4.8 Investment Analysis
- 4.8.1 VC Funding Trends
- 4.8.2 MandA Landscape
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sensor Type
- 5.1.1 Touch/Capacitive
- 5.1.2 Pressure / Force
- 5.1.3 Biosensors
- 5.1.4 Gas/Chemical
- 5.1.5 Piezo/Strain
- 5.1.6 Temperature
- 5.2 By Printing Technology
- 5.2.1 Screen
- 5.2.2 Inkjet
- 5.2.3 Flexographic
- 5.2.4 Gravure
- 5.2.5 Aerosol-Jet and Others
- 5.3 By Substrate
- 5.3.1 Plastic Films (PET, PEN)
- 5.3.2 Paper and Paperboard
- 5.3.3 Glass
- 5.3.4 Textiles and Elastomers
- 5.4 By End-User
- 5.4.1 Consumer Electronics
- 5.4.2 Healthcare and Medical Devices
- 5.4.3 Industrial and Manufacturing
- 5.4.4 Automotive and Transportation
- 5.4.5 Aerospace and Defense
- 5.4.6 Others (Smart Packaging, Agriculture)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 United Kingdom
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 GCC
- 5.5.5.2 Turkey
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Moves
- 6.1.1 Partnerships and Licensing
- 6.1.2 Capacity Expansions
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 FlexEnable Ltd.
- 6.3.2 ISORG SA
- 6.3.3 Plastic Logic HK Ltd.
- 6.3.4 Renesas Electronics Corp.
- 6.3.5 Butler Technologies Inc.
- 6.3.6 Canatu Oy
- 6.3.7 SPEC Sensors LLC
- 6.3.8 Peratech Holdco Ltd.
- 6.3.9 Pressure Profile Systems Inc.
- 6.3.10 Tekscan Inc.
- 6.3.11 Thin Film Electronics ASA
- 6.3.12 Molex LLC
- 6.3.13 Interlink Electronics Inc.
- 6.3.14 Fujifilm Dimatix Inc.
- 6.3.15 Heraeus Noblelight GmbH
- 6.3.16 Nissha Co. Ltd.
- 6.3.17 T+Ink Inc.
- 6.3.18 GSI Technologies LLC
- 6.3.19 Brewer Science Inc.
- 6.3.20 Henkel AG and Co. KGaA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet Need Analysis

 軟性感測器市場:商業機會、成長要素、產業趨勢分析及2026-2035年預測
 印刷軟性感測器市場:按感測器類型、技術、材料類型、終端用戶產業和應用分類-2026-2032年全球市場預測
 印刷感測器市場規模、佔有率、趨勢和預測:按類型、印刷技術、應用和地區分類,2026-2034年
 印刷軟性感測器市場分析及預測(至2035年):按類型、產品、技術、組件、應用、材料類型、裝置、最終用戶和功能分類
 印刷軟性感測器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 印刷感測器市場規模、佔有率和成長分析(按類型、印刷技術、應用和地區分類)—產業預測(2026-2033 年)
 全球印刷和嵌入式感測器電子市場:預測至 2032 年—按組件、感測器、印刷、製造流程、應用、最終用戶和地區進行分析
 軟性微奈米感測器市場報告:至2031年的趨勢、預測與競爭分析印刷感測器市場報告:2031 年趨勢、預測與競爭分析