

 |
市場調查報告書
商品編碼
2038272
軟性感測器市場:商業機會、成長要素、產業趨勢分析及2026-2035年預測Flexible Sensor Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

預計到 2025 年,全球軟性感測器市場規模將達到 64 億美元,並預計以 7.2% 的複合年成長率成長,到 2035 年達到 128 億美元。
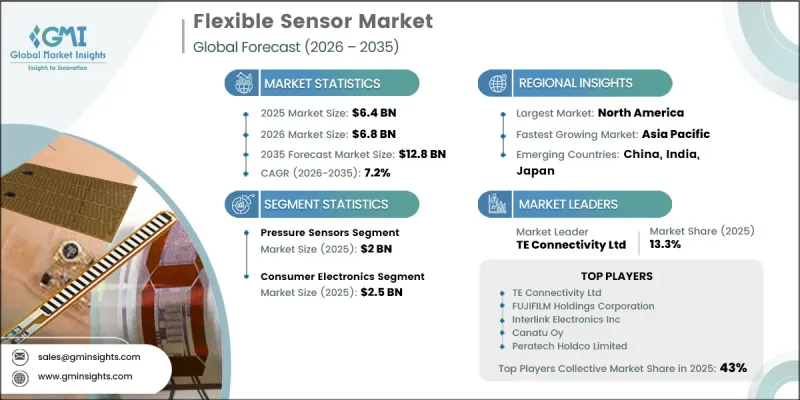
隨著全球對穿戴式電子產品和持續健康監測解決方案的需求加速成長,該產業正蓬勃發展。預防醫學意識的提高以及文明病的增加,促使消費者採用能夠即時追蹤生命徵象的設備。軟性感測器使得開發輕巧、親膚、非侵入性的設備成為可能,這些設備能夠提供精準的測量結果,且不會在長時間佩戴時造成不適。醫療保健系統向遠端患者監護的轉變正在推動此類設備的普及,而材料科學和感測器設計的不斷進步則提升了設備的性能。同時,與家用電子電器和下一代顯示技術的日益整合也在推動市場擴張,製造商正致力於創新,以滿足不斷變化的用戶期望和功能需求。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 64億美元 |
| 預測金額 | 128億美元 |
| 複合年成長率 | 7.2% |
預計到2025年,壓力感測器市場規模將達到20億美元,這主要得益於穿戴式裝置、汽車應用和高階家用電子電器中壓力感測器應用的日益廣泛。這些感測器能夠精確測量力、運動和觸覺,進而提升設備的反應速度和使用者互動。此外,市場對緊湊、輕巧和高性能組件的需求不斷成長,進一步推動了該領域的發展,並鞏固了主導地位。
預計到2035年,醫療保健產業將以8.4%的複合年成長率成長,這主要得益於穿戴式醫療技術和遠端監測系統的快速發展。軟性感測器在持續追蹤患者健康指標方面發揮著至關重要的作用,有助於改善臨床療效並提高醫療服務效率。它們在醫院、居家照護機構和診斷應用中的日益普及,反映了市場對即時、數據驅動型醫療保健解決方案日益成長的需求。
預計到2025年,北美軟性感測器市場佔有率將達到37.9%。這主要得益於積極的技術應用以及製造商和終端用戶之間成熟的生態系統。穿戴式裝置的高滲透率、智慧工業系統的不斷擴展部署以及對先進健康監測解決方案的強勁需求,進一步鞏固了該地區的主導地位。經濟成長和創新主導的投資將繼續推動軟性感測器技術在多個行業的廣泛應用。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 對穿戴式電子設備和健康監測設備的需求日益成長
- 在家用電子電器和折疊式顯示器領域的應用日益廣泛。
- 在汽車電子和智慧內裝領域的應用日益廣泛
- 物聯網 (IoT) 生態系的擴展
- 在醫療和生物醫學設備領域不斷拓展應用。
- 產業潛在風險與挑戰
- 高昂的製造成本和原料成本
- 與剛性感測器相比,其耐用性和可靠性有限。
- 市場機遇
- 智慧紡織品和電子紡織品的應用日益廣泛
- 開發下一代軟性可拉伸材料
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特五力分析
- PESTEL 分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格趨勢(基於付費資料庫)
- 歷史價格分析(2022-2025)
- 影響價格趨勢的因素
- 區域價格波動
- 價格預測(2026-2035)
- 貿易數據分析(基於初步調查)
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 細分市場生成式人工智慧用例和實施藍圖
- 風險、限制和監管考量
- 生產能力和生產趨勢(基於初步調查)
- 按地區和主要生產商分類的設備產能
- 運轉率和擴張計劃
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 企業級分層基準測試
- 層級分類標準與選擇標準
- 按收入、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:依感測器類型分類,2022-2035年
- 壓力感測器
- 壓阻式壓力感測器
- 電容式壓力感測器
- 生物感測器
- 電化學生物感測器
- 光學生物感測器
- 其他
- 溫度感測器
- 電阻式溫度感測器
- 熱電偶感測器
- 紅外線溫度感測器
- 化學感測器
- 氣體感測器
- 濕度感測器
- 應變感測器
- 光學感測器
- 其他
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 監測和檢測
- 品管和回饋
- 測量
- 診斷
- 其他
第7章 市場估計與預測:依最終用戶產業分類,2022-2035年
- 家用電子電器
- 衛生保健
- 車
- 航太/國防
- 能源與公共產業
- 食品/飲料
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 其他歐洲地區
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 亞太其他地區
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲地區
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東和非洲地區
第9章:公司簡介
- 全球主要公司
- TE Connectivity Ltd
- FUJIFILM Holdings Corporation
- FlexEnable Limited
- Plastic Logic Limited
- 當地公司
- Canatu Oy
- Isorg SA
- Thin Film Electronics ASA
- ElastiSense
- 利基公司
- Tekscan Inc
- Interlink Electronics Inc
- KWJ Engineering Inc
- BeBop Sensors Inc
- T+Ink Inc
- SynTouch LLC
- Peratech Holdco Limited
- NextInput Inc
- Flexpoint Sensor Systems Inc
- Sensitronics LLC
- GSI Technologies Inc.
The Global Flexible Sensor Market was valued at USD 6.4 billion in 2025 and is estimated to grow at a CAGR of 7.2% to reach USD 12.8 billion by 2035.
The industry is gaining traction as demand for wearable electronics and continuous health monitoring solutions accelerates worldwide. Increasing awareness around preventive healthcare and the rising prevalence of lifestyle-related conditions are encouraging consumers to adopt devices that enable real-time tracking of vital parameters. Flexible sensors are enabling the development of lightweight, skin-friendly, and non-invasive devices that deliver accurate readings without discomfort over extended periods. The shift toward remote patient monitoring across healthcare systems is supporting adoption, while ongoing advancements in material science and sensor design are enhancing performance capabilities. In parallel, growing integration in consumer electronics and next-generation display technologies is reinforcing market expansion, as manufacturers focus on innovation to meet evolving user expectations and functionality requirements.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.4 Billion |
| Forecast Value | $12.8 Billion |
| CAGR | 7.2% |
The pressure sensors segment generated USD 2 billion in 2025, supported by increasing utilization across wearable devices, automotive applications, and advanced consumer electronics. These sensors enable precise measurement of force, motion, and touch, improving device responsiveness and user interaction. Rising demand for compact, lightweight, and high-performance components is further strengthening the segment's growth trajectory, reinforcing its leading position in the global market.
The healthcare segment is anticipated to grow at a CAGR of 8.4% through 2035, driven by rapid advancements in wearable medical technologies and remote monitoring systems. Flexible sensors play a critical role in enabling continuous tracking of patient health metrics, contributing to improved clinical outcomes and enhanced efficiency in healthcare delivery. Their growing adoption across hospitals, home care environments, and diagnostic applications reflects the increasing need for real-time, data-driven healthcare solutions.
North America Flexible Sensor Market accounted for 37.9% share in 2025, supported by strong technological adoption and a well-established ecosystem of manufacturers and end users. The region's leadership is further reinforced by high penetration of wearable devices, increasing deployment of intelligent industrial systems, and strong demand for advanced health monitoring solutions. Economic growth and innovation-driven investments continue to support the widespread integration of flexible sensor technologies across multiple industries.
Key players operating in the Global Flexible Sensor Industry include Tekscan Inc, Interlink Electronics Inc, FlexEnable Limited, KWJ Engineering Inc, TE Connectivity Ltd, FUJIFILM Holdings Corporation, Canatu Oy, BeBop Sensors Inc, Isorg SA, Thin Film Electronics ASA, T+Ink Inc, SynTouch LLC, Plastic Logic Limited, Peratech Holdco Limited, ElastiSense, NextInput Inc, Flexpoint Sensor Systems Inc, and Sensitronics LLC. Companies in the flexible sensor market are focusing on continuous innovation, strategic collaborations, and advanced material development to strengthen their competitive position. They are investing heavily in research and development to enhance sensor accuracy, flexibility, and durability while reducing production costs. Partnerships with healthcare providers, consumer electronics manufacturers, and automotive firms are enabling broader application integration and faster commercialization. Many players are also expanding their product portfolios to cater to emerging use cases such as wearable healthcare and smart devices.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Sensor Type trends
- 2.2.2 Application trends
- 2.2.3 End-user industry trends
- 2.2.4 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing demand for wearable electronics and health monitoring devices
- 3.2.1.2 Growing adoption in consumer electronics and foldable displays
- 3.2.1.3 Rising use in automotive electronics and smart interiors
- 3.2.1.4 Expansion of internet of things (IoT) ecosystems
- 3.2.1.5 Growing applications in healthcare and biomedical devices
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High manufacturing and material costs
- 3.2.2.2 Limited durability and reliability compared to rigid sensors
- 3.2.3 Market opportunities
- 3.2.3.1 Growing adoption in smart textiles and e-textiles
- 3.2.3.2 Development of next-generation flexible and stretchable materials
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends (Based on paid Database)
- 3.8.1 Historical Price Analysis (2022-2025)
- 3.8.2 Price Trend Drivers
- 3.8.3 Regional Price Variations
- 3.8.4 Price Forecast (2026-2035)
- 3.9 Trade Data Analysis (Driven by Primary Research)
- 3.9.1 Import/Export Volume & Value Trends
- 3.9.2 Key Trade Corridors & Tariff Impact
- 3.10 Impact of AI & Generative AI on the Market
- 3.10.1 AI-Driven Disruption of Existing Business Models
- 3.10.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10.3 Risks, Limitations & Regulatory Considerations
- 3.11 Capacity & Production Landscape (Driven by Primary Research)
- 3.11.1 Installed Capacity by Region & Key Producer
- 3.11.2 Capacity Utilization Rates & Expansion Pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Sensor Type, 2022 - 2035 (USD Million & Units)
- 5.1 Key trends
- 5.2 Pressure sensors
- 5.2.1 Piezoresistive pressure sensors
- 5.2.2 Capacitive pressure sensors
- 5.3 Biosensors
- 5.3.1 Electrochemical biosensors
- 5.3.2 Optical biosensors
- 5.3.3 Others
- 5.4 Temperature sensors
- 5.4.1 Resistive temperature sensors
- 5.4.2 Thermocouple-based sensors
- 5.4.3 Infrared temperature sensors
- 5.5 Chemical sensors
- 5.5.1 Gas sensors
- 5.5.2 Humidity sensors
- 5.6 Strain sensors
- 5.7 Optical sensors
- 5.8 Others
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million & Units)
- 6.1 Key trends
- 6.2 Monitoring & detection
- 6.3 Quality control & feedback
- 6.4 Measurement
- 6.5 Diagnostics
- 6.6 Others
Chapter 7 Market Estimates and Forecast, By End-User Industry, 2022 - 2035 (USD Million & Units)
- 7.1 Key trends
- 7.2 Consumer electronics
- 7.3 Healthcare
- 7.4 Automotive
- 7.5 Aerospace & defense
- 7.6 Energy & utilities
- 7.7 Food & beverage
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million & Units)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Netherlands
- 8.3.7 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
- 8.6.4 Rest of MEA
Chapter 9 Company Profiles
- 9.1 Global Key Players
- 9.1.1 TE Connectivity Ltd
- 9.1.2 FUJIFILM Holdings Corporation
- 9.1.3 FlexEnable Limited
- 9.1.4 Plastic Logic Limited
- 9.2 Regional players
- 9.2.1 Canatu Oy
- 9.2.2 Isorg SA
- 9.2.3 Thin Film Electronics ASA
- 9.2.4 ElastiSense
- 9.3 Niche players
- 9.3.1 Tekscan Inc
- 9.3.2 Interlink Electronics Inc
- 9.3.3 KWJ Engineering Inc
- 9.3.4 BeBop Sensors Inc
- 9.3.5 T+Ink Inc
- 9.3.6 SynTouch LLC
- 9.3.7 Peratech Holdco Limited
- 9.3.8 NextInput Inc
- 9.3.9 Flexpoint Sensor Systems Inc
- 9.3.10 Sensitronics LLC
- 9.3.11 GSI Technologies Inc.

 印刷感測器:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 印刷軟性感測器市場:按感測器類型、技術、材料類型、終端用戶產業和應用分類-2026-2032年全球市場預測
 印刷感測器市場規模、佔有率、趨勢和預測:按類型、印刷技術、應用和地區分類,2026-2034年
 印刷軟性感測器市場分析及預測(至2035年):按類型、產品、技術、組件、應用、材料類型、裝置、最終用戶和功能分類印刷軟性感測器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 印刷感測器市場規模、佔有率和成長分析(按類型、印刷技術、應用和地區分類)—產業預測(2026-2033 年)
 全球印刷和嵌入式感測器電子市場:預測至 2032 年—按組件、感測器、印刷、製造流程、應用、最終用戶和地區進行分析
 軟性微奈米感測器市場報告:至2031年的趨勢、預測與競爭分析印刷感測器市場報告:2031 年趨勢、預測與競爭分析