


 |
市場調查報告書
商品編碼
2122662
射頻氮化鎵:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)RF GaN - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年射頻氮化鎵市場價值為 20.1 億美元,預計到 2031 年將從 2026 年的 24.1 億美元成長至 59 億美元,預測期(2026-2031 年)複合年成長率為 19.61%。
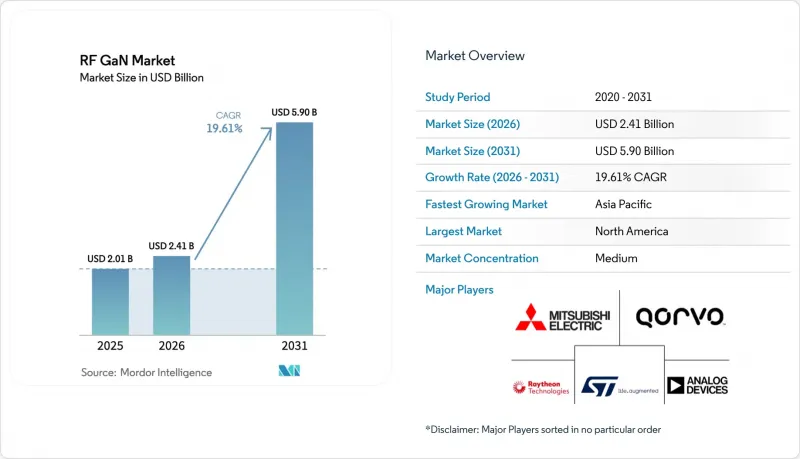
本報告按應用領域(軍事、電信基礎設施、衛星通訊、有線寬頻及其他)、材料類型(GaN-on-Si、GaN-on-SiC及其他材料類型)、裝置類型(分離式電晶體、MMIC、功率放大器模組及其他)、頻段(低於3GHz、3-6GHz、6-18GHz、高於18GHz)和地區進行細分。市場預測以美元(USD)計價。
全球射頻氮化鎵市場趨勢與洞察
Sub-6GHz 5G mMIMO 基地台的部署正在迅速增加。
2025年,行動電信商部署了120萬個新的5G基地台,其中68%的基地台配備了大規模MIMO無線電設備,每個設備包含64個收發器,每個收發器至少包含64個GaN功率放大器。 2025年6月,三菱電機出貨了一款200瓦的C波段模組,該模組在6dB回退下實現了50%的漏極效率,比上一代產品提高了12個百分點。 2025年,中國電信業者在5G無線電設備方面的投資額達到870億元人民幣,實現了40%的國內GaN產能佔比,符合「中國製造2025」的目標。印度監管機構強制要求大型基地台從2026年1月起採用三頻段載波聚合,將使每個站點的擴大機數量增加一倍。這些規定導致短期需求集中在3.3-3.8GHz頻段,而射頻GaN市場則持續得到Sub-6GHz頻段出貨量的強勁支撐。
加速國防平台上AESA雷達的升級
2025年,14個國家的國防部投資83億美元用於AESA雷達升級,加速從砷化鎵收發器模組到氮化鎵收發器模組的過渡。這將使探測距離翻倍,同時降低雷達機隊的功耗。 2025年9月,雷神公司開始向F-15EX和F-16V戰鬥機交付X波段。每個陣列包含1200個氮化鎵單片微波積體電路(MMIC)。 2025年3月,日本防衛省向三菱電機訂購價值3.1億美元的國產火控雷達,用於其下一代戰鬥機。諾斯羅普·格魯曼公司透露,其 AN/APG-83 雷達中的氮化鎵含量將從 2023 年的 22% 增加到 2025 年的 61%。根據《國際武器貿易條例》(ITAR) 的出口限制,該產品的銷售僅限於盟國,這有助於維持較高的平均售價,從而覆蓋持續的製程研發成本。
外延晶片中高缺陷密度會影響成品率。
預計到2025年,商用GaN-on-SiC外延的螺位錯密度將接近5 × 10⁸ cm⁻²,約為成熟GaAs產品線的10倍,這將導致高功率元件良率下降高達25%。 Wolfspeed公司透露,其位於達勒姆的工廠的返工率佔晶圓投入的8%,使其2025會計年度的毛利率下降了220個基點。 AIXTRON和Veeco公司推出了附加元件,單價為120萬美元。該組件使工程師能夠更早停止有缺陷的生產流程,但到2025年,只有不到三分之一的反應器升級到了這項功能。美國於2024年10月對先進的MOCVD設備實施出口限制,進一步限制了中國晶圓廠進行這些升級的能力,並擴大了與西方供應商的良率差距。除非密度降至 1 × 10⁸ cm⁻² 以下,否則射頻氮化鎵市場的成本優勢預計將是有限的。
細分市場分析
到2025年,電信基礎設施收入佔比將達到46.62%,營運商將在全球部署520萬個5G基地台。然而,衛星通訊預計將以20.44%的複合年成長率成長,並預計在2031年縮小與電信基礎設施收入的差距,這主要得益於低地球軌道(LEO)衛星星系發射數量的增加。國防領域保持第二的位置,主要得益於諸如AESA雷達維修等軍事項目的推動。同時,隨著DOCSIS 4.0的升級,有線寬頻節點訂單小規模成長,但成長緩慢。霍尼韋爾採用氮化鎵(GaN)技術並將天線尺寸縮小了40%,使得商用雷達和航空電子設備形成了一個規模雖小但盈利的細分市場。
電信業者為了追求更高的吞吐量,目前已將Ka波段有效載荷視為標準配置,這既能確保每顆衛星配備高功率放大器,又能為供應商提供多年穩定的市場需求。相較之下,射頻能量應用仍處於試驗階段,儘管三菱電機在2025年6月宣布推出一款用於工業烤箱、效率高達70%的915MHz模組。監理政策的變化,例如美國聯邦通訊委員會(FCC)對C波段的重新分配,也促使部分頻段重新分配給5G,間接推動了3.7-3.98GHz頻段氮化鎵(GaN)的需求。總體而言,目前的消費主要由通訊領域主導,但預計在整個預測期內,衛星通訊仍將推動射頻氮化鎵市場的成長。
預計到2025年,GaN-on-SiC基板將佔據72.73%的市場佔有率,SiC高達490 W/m·K的熱導率確保即使在結溫超過200 度C的情況下也能無故障運作。雖然GaN-on-Si在3 GHz以下頻寬仍具有應用價值,因為該頻段對擊穿電壓的要求較低,但許多電信業者正在轉向使用SiC以最大限度地提高功率附加效率。在高頻率,GaN-on-SiC在射頻GaN市場的主導地位預計將進一步擴大,預計到2031年,該類別的複合年成長率將達到21.12%。
Wolfspeed 將 200 毫米 SiC 晶圓的價格從 2024 年的 850 美元降至 2025 年的 610 美元,此舉緩解了成本壓力,縮小了與矽的價格差距,並促進了更廣泛的應用。其他方案,例如鑽石基氮化鎵 (GaN-on-Diamond),雖然結溫低 40-50 度C,但其 4 英寸晶圓 2400 美元的價格仍然限制了其在高階國防應用領域的應用。隨著代工廠擴大生產直徑,SiC 的性能優勢以及更低的基板成本預計將使其繼續成為射頻氮化鎵市場高功率密度設計的首選。
區域分析
北美在2025年仍維持39.74%的市場佔有率,這得益於8,860億美元的國防費用以及《晶片技術創新法案》(CHIPS Act)提供的超過9億美元的獎勵,這些激勵措施旨在支持Wolfspeed、Skyworks和BAE Systems等公司擴大產能。加拿大在抗輻射氮化鎵(GaN)研究方面追加投資8,800萬美元,而墨西哥則憑藉接近性美國設計機構的地理優勢,在組裝領域吸引了小規模的投資。
預計到2031年,亞太地區的年複合成長率將達到20.67%。中國計劃在2025年建成90萬個5G基地台,並在外延晶圓研發領域投資500億元。日本經濟產業省已為寬能隙晶圓廠累計補貼,而印度的生產連結獎勵計畫計畫(最高可涵蓋50%的資本成本)也吸引了塔塔集團的注意。東協,尤其是越南和泰國,正憑藉著低廉的人事費用和出口獎勵政策,努力打造自身作為組裝中心的地位。
歐洲的市佔率約為15%。根據《歐洲晶片法案》,歐洲已撥款12億歐元用於建設一條試點生產線,英飛凌科技也以8.3億美元完成了對GaN Systems的收購,因此,歐洲市場的關注點仍然主要集中在1GHz以下頻段。意法半導體位於卡塔尼亞的工廠正在加強區域產能,儘管其射頻產量僅佔不到10%。在中東和非洲,阿拉伯聯合大公國和沙烏地阿拉伯的衛星閘道器專案對氮化鎵晶片有需求,但拉丁美洲仍處於起步階段,目前僅有一些零星的國防項目,例如巴西航空工業公司(Embraer)的氮化鎵飛機無線電項目。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- Sub-6GHz 5G mMIMO 基地台的部署正在迅速增加。
- 加速國防平台上AESA雷達的升級
- 由於向 6 英寸和 8 英寸 GaN-on-SiC 晶圓過渡,$/W 的價格下降。
- 在低地球軌道/地球同步軌道衛星有效載荷中採用氮化鎵前端
- 毫米波回程回程傳輸對超寬頻功率放大器的需求
- 政府對國內化合物半導體供應鏈的資助
- 市場限制因素
- 外延晶片中高缺陷密度會影響成品率。
- 高密度陣列中超過 10 W/mm 的溫度控管限制
- 氮化鎵裝置和金屬有機化學氣相沉積設備的出口限制
- 採用低於 3GHz 的先進 LDMOS 技術的競爭
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 透過使用
- 軍隊
- 通訊基礎設施(回程傳輸、RRH、大規模MIMO、小型基地台)
- 衛星通訊
- 有線寬頻
- 商用雷達和航空電子設備
- 射頻能量
- 依材料類型
- GaN-on-Si
- GaN-on-SiC
- 其他材料類型(GaN-on-GaN、GaN-on-Diamond)
- 依設備類型
- 分立電晶體(HEMT)
- 單晶微波積體電路(MMIC)
- 功率放大器模組
- 驅動擴大機
- 按頻段
- 3GHz以下(L波段、S波段)
- 3-6GHz(C頻段,5G Sub-6)
- 6–18GHz(X波段, Ku波段)
- 18GHz以上(Ka波段,毫米波)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- ASEAN
- 大洋洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 北非
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Aethercomm Inc.
- Ampleon Netherlands BV
- Analog Devices Inc.
- Broadcom Inc.
- Efficient Power Conversion Corp.
- Guerrilla RF Inc.
- HRL Laboratories LLC
- Infineon Technologies AG
- Integra Technologies Inc.
- MACOM Technology Solutions Holdings Inc.
- Mercury Systems Inc.
- Mitsubishi Electric Corp.
- NXP Semiconductors NV
- Northrop Grumman Corp.
- Qorvo Inc.
- Raytheon Technologies Corp.
- RFHIC Corp.
- Skyworks Solutions Inc.
- STMicroelectronics NV
- Sumitomo Electric Device Innovations Inc.
- Tagore Technology Inc.
- Teledyne Technologies Inc.
- Toshiba Corp.
- WIN Semiconductors Corp.
- Wolfspeed Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the RF GaN market size was valued at USD 2.01 billion in 2025 and is estimated to grow from USD 2.41 billion in 2026 to reach USD 5.90 billion by 2031, at a CAGR of 19.61% during the forecast period (2026-2031).
This report is Segmented by Application (Military, Telecom Infrastructure, Satellite Communication, Wired Broadband, and More), Material Type (GaN-On-Si, GaN-On-SiC, and Other Material Types), Device Type (Discrete Transistors, MMIC, Power-Amplifier Modules, and More), Frequency Band (Below 3 GHz, 3-6 GHz, 6-18 GHz, and Above 18 GHz), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global RF GaN Market Trends and Insights
Surge in Sub-6 GHz 5G mMIMO Base-Station Deployments
Mobile operators installed 1.2 million new 5G sites in 2025, of which 68% included 64-transceiver massive MIMO radios that each embed at least 64 GaN power amplifiers. Mitsubishi Electric shipped a 200-watt C-band module in June 2025, which achieved 50% drain efficiency at a 6 dB back-off, representing a 12 percentage-point improvement over the prior generation. China's operators spent CNY 87 billion on 5G radios in 2025, specifying 40% indigenous GaN content in line with Made in China 2025 targets. India's regulator mandated triple-band carrier aggregation for macro cells from January 2026, implicitly doubling the amplifier count per site. Together these mandates concentrate near-term demand in the 3.3-3.8 GHz window, keeping the RF GaN market firmly anchored in sub-6 GHz shipments.
Accelerating AESA Radar Upgrades Across Defense Platforms
Fourteen defense ministries committed USD 8.3 billion to AESA radar refresh programs during 2025, moving from gallium arsenide to GaN transmit-receive modules that double detection range while lowering fleet power draw. Raytheon began X-band APG-82(V)X deliveries for F-15EX and F-16V jets in September 2025, each array integrating 1,200 GaN MMICs. Japan's Ministry of Defense awarded Mitsubishi Electric USD 310 million in March 2025 to develop an indigenous fire-control radar for its next-generation fighter. Northrop Grumman disclosed that GaN content inside its AN/APG-83 radar rose from 22% in 2023 to 61% in 2025. Export rules under the International Traffic in Arms Regulations channel sales to allied nations, sustaining premium average selling prices that finance ongoing process R&D.
High Epitaxial-Wafer Defect Density Affecting Yield
Commercial GaN-on-SiC epitaxy posted threading dislocation densities near 5 X 108 cm-2 in 2025, about ten times higher than mature GaAs lines, depressing yields by up to 25% on high-power parts. Wolfspeed disclosed that rework consumed 8% of wafer starts at its Durham site and compressed gross margin by 220 basis points in fiscal 2025. AIXTRON and Veeco launched in-situ optical reflectometry add-ons priced at USD 1.2 million per reactor that let engineers abort defective runs early, yet fewer than one-third of reactors were retrofitted in 2025. United States export controls on advanced MOCVD tools introduced in October 2024 further limited Chinese fabs' ability to adopt these upgrades, widening the yield gap with Western suppliers. Until densities fall below 1 X 108 cm-2 the RF GaN market gains in cost will be tempered.
Other drivers and restraints analyzed in the detailed report include:
- Transition to 6-Inch and 8-Inch GaN-on-SiC Wafers Lowering USD per Watt
- GaN Front-End Adoption in LEO and GEO Satellite Payloads
- Thermal-Management Limits Above 10 W/mm in Dense Arrays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Telecom infrastructure accounted for 46.62% of revenue in 2025 as operators supported 5.2 million 5G base stations worldwide. Satellite communication, however, is on track to register a 20.44% CAGR and will narrow the gap by 2031, powered by rising LEO constellation launches. Military programs such as AESA radar retrofits kept defense in the second position, while wired broadband nodes within DOCSIS 4.0 upgrades delivered steady but low-growth orders. Commercial radar and avionics created a small yet profitable niche, as Honeywell adopted GaN to shrink antenna size by 40%.
Operators chasing higher throughput now view Ka-band payloads as standard, which keeps amplifier counts per satellite high and secures multi-year visibility for suppliers. In contrast, RF energy applications stayed experimental although Mitsubishi Electric showcased a 70% efficient 915 MHz module for industrial ovens in June 2025. Regulatory shifts such as the United States FCC C-band repack also redirect spectrum toward 5G, indirectly boosting GaN demand in the 3.7-3.98 GHz slice. Overall, telecom dominates present consumption, yet satellite communication is likely to carry the growth banner for the RF GaN market through the forecast horizon.
GaN-on-SiC substrates held 72.73% revenue in 2025, underscoring SiC's thermal conductivity of 490 W/m K that allows junction temperatures above 200 °C without failure. GaN-on-Si remains relevant below 3 GHz where lower breakdown voltage is acceptable, but many operators are shifting to SiC to maximize power-added efficiency. The RF GaN market size advantage for GaN-on-SiC widens further at high frequencies, and the category is set for a 21.12% CAGR to 2031.
Cost pressure is easing as Wolfspeed lowered the 200-millimeter SiC wafer price from USD 850 in 2024 to USD 610 in 2025, narrowing the gap with silicon and encouraging broader adoption. Other options, such as GaN-on-diamond, showed a 40-50 °C junction reduction but, at USD 2,400 per 4-inch wafer, remain confined to premium defense applications. As foundries scale to larger diameters, SiC's performance lead, combined with falling substrate costs, will keep it the default choice for high power density designs across the RF GaN market.
Complete Report Scope:
- By Application
- Military
- Telecom Infrastructure (Backhaul, RRH, Massive MIMO, Small Cells)
- Satellite Communication
- Wired Broadband
- Commercial Radar and Avionics
- RF Energy
- By Material Type
- GaN-on-Si
- GaN-on-SiC
- Other Material Types (GaN-on-GaN, GaN-on-Diamond)
- By Device Type
- Discrete Transistors (HEMT)
- Monolithic Microwave ICs (MMIC)
- Power-Amplifier Modules
- Driver Amplifiers
- By Frequency Band
- Below 3 GHz (L, S Bands)
- 3 - 6 GHz (C Band, 5G Sub-6)
- 6 - 18 GHz (X, Ku)
- Above 18 GHz (Ka, mmWave)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Oceania
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 39.74% share in 2025 due to defense outlays of USD 886 billion and CHIPS Act incentives exceeding USD 900 million that underwrite capacity expansion at Wolfspeed, Skyworks, and BAE Systems. Canada added USD 88 million for radiation-hardened GaN research, and Mexico drew modest assembly investment, leveraging proximity to United States design hubs.
Asia Pacific is set for a 20.67% CAGR through 2031. China erected 900,000 5G base stations in 2025 and committed CNY 50 billion to epitaxial wafer R&D. Japan's economic ministry earmarked subsidies for wide-bandgap fabs, while India's production-linked incentive scheme covers up to 50% of capital cost, drawing interest from Tata Group. ASEAN nations, especially Vietnam and Thailand, position themselves as assembly hubs to mix lower labor cost with export privileges.
Europe held a mid-teens stake. The European Chips Act unlocked EUR 1.2 billion for pilot lines, and Infineon Technologies closed its USD 830 million GaN Systems acquisition, though focus remains mainly below 1 GHz. STMicroelectronics' Catania line accounts for sub-10% RF output yet strengthens regional capability. Middle East and Africa saw demand from satellite gateways in the United Arab Emirates and Saudi Arabia, while Latin America stays early stage with isolated defense programs such as Embraer's GaN-enabled aircraft radios.
- Aethercomm Inc.
- Ampleon Netherlands B.V.
- Analog Devices Inc.
- Broadcom Inc.
- Efficient Power Conversion Corp.
- Guerrilla RF Inc.
- HRL Laboratories LLC
- Infineon Technologies AG
- Integra Technologies Inc.
- MACOM Technology Solutions Holdings Inc.
- Mercury Systems Inc.
- Mitsubishi Electric Corp.
- NXP Semiconductors N.V.
- Northrop Grumman Corp.
- Qorvo Inc.
- Raytheon Technologies Corp.
- RFHIC Corp.
- Skyworks Solutions Inc.
- STMicroelectronics N.V.
- Sumitomo Electric Device Innovations Inc.
- Tagore Technology Inc.
- Teledyne Technologies Inc.
- Toshiba Corp.
- WIN Semiconductors Corp.
- Wolfspeed Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in sub-6 GHz 5G mMIMO base-station deployments
- 4.2.2 Accelerating AESA radar upgrades across defense platforms
- 4.2.3 Transition to 6-inch and 8-inch GaN-on-SiC wafers lowering $/W
- 4.2.4 GaN front-end adoption in LEO and GEO satellite payloads
- 4.2.5 Demand for ultra-wide-bandwidth PAs in mmWave backhaul
- 4.2.6 Government funding for domestic compound-semiconductor supply chains
- 4.3 Market Restraints
- 4.3.1 High epitaxial-wafer defect density affecting yield
- 4.3.2 Thermal-management limits above 10 W/mm in dense arrays
- 4.3.3 Export-control regulations on GaN devices and MOCVD tools
- 4.3.4 Competition from advanced LDMOS below 3 GHz
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Military
- 5.1.2 Telecom Infrastructure (Backhaul, RRH, Massive MIMO, Small Cells)
- 5.1.3 Satellite Communication
- 5.1.4 Wired Broadband
- 5.1.5 Commercial Radar and Avionics
- 5.1.6 RF Energy
- 5.2 By Material Type
- 5.2.1 GaN-on-Si
- 5.2.2 GaN-on-SiC
- 5.2.3 Other Material Types (GaN-on-GaN, GaN-on-Diamond)
- 5.3 By Device Type
- 5.3.1 Discrete Transistors (HEMT)
- 5.3.2 Monolithic Microwave ICs (MMIC)
- 5.3.3 Power-Amplifier Modules
- 5.3.4 Driver Amplifiers
- 5.4 By Frequency Band
- 5.4.1 Below 3 GHz (L, S Bands)
- 5.4.2 3 - 6 GHz (C Band, 5G Sub-6)
- 5.4.3 6 - 18 GHz (X, Ku)
- 5.4.4 Above 18 GHz (Ka, mmWave)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 ASEAN
- 5.5.4.6 Oceania
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 UAE
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 North Africa
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Aethercomm Inc.
- 6.4.2 Ampleon Netherlands B.V.
- 6.4.3 Analog Devices Inc.
- 6.4.4 Broadcom Inc.
- 6.4.5 Efficient Power Conversion Corp.
- 6.4.6 Guerrilla RF Inc.
- 6.4.7 HRL Laboratories LLC
- 6.4.8 Infineon Technologies AG
- 6.4.9 Integra Technologies Inc.
- 6.4.10 MACOM Technology Solutions Holdings Inc.
- 6.4.11 Mercury Systems Inc.
- 6.4.12 Mitsubishi Electric Corp.
- 6.4.13 NXP Semiconductors N.V.
- 6.4.14 Northrop Grumman Corp.
- 6.4.15 Qorvo Inc.
- 6.4.16 Raytheon Technologies Corp.
- 6.4.17 RFHIC Corp.
- 6.4.18 Skyworks Solutions Inc.
- 6.4.19 STMicroelectronics N.V.
- 6.4.20 Sumitomo Electric Device Innovations Inc.
- 6.4.21 Tagore Technology Inc.
- 6.4.22 Teledyne Technologies Inc.
- 6.4.23 Toshiba Corp.
- 6.4.24 WIN Semiconductors Corp.
- 6.4.25 Wolfspeed Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 射頻氮化鎵技術專利趨勢分析(2026 年)
 氮化鎵射頻半導體元件:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)2026-2034年全球氮化鎵市場規模、佔有率、趨勢和成長分析報告射頻氮化鎵技術專利監測器
 射頻氮化鎵市場規模、佔有率和成長分析:按應用、產品類型、基板、最終用戶和地區分類-2026-2033年產業預測
 射頻氮化鎵市場:依產品、材料組成、晶圓尺寸、應用和終端用戶產業分類-全球預測,2026-2032年
 射頻氮化鎵(RF GaN)元件市場分析及預測(至2035年):依類型、產品類型、技術、元件、應用、材料類型、製程、部署狀態、最終用戶及功能分類微波氮化鎵 (GaN) 市場分析及預測(至 2035 年):按類型、產品類型、技術、組件、應用、材料類型、裝置、最終用戶、功能和安裝類型分類氮化鎵高頻功率放大器市場分析及預測(至2035年):按類型、產品類型、技術、組件、應用、最終用戶、功能、安裝類型、解決方案和模式分類高頻氮化鎵市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、材料類型、裝置、最終用戶、功能分類