


 |
市場調查報告書
商品編碼
2122661
內容傳遞網路(CDN) 安全性:市場佔有率分析、產業趨勢與統計資料以及成長預測 (2026-2031)Content Delivery Network (CDN) Security - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年內容傳遞網路(CDN) 安全市場價值為 56.2 億美元,預計到 2031 年將達到 124.8 億美元,而 2026 年為 64.2 億美元,預測期(2026-2031 年)的複合年成長率為 14.2%。
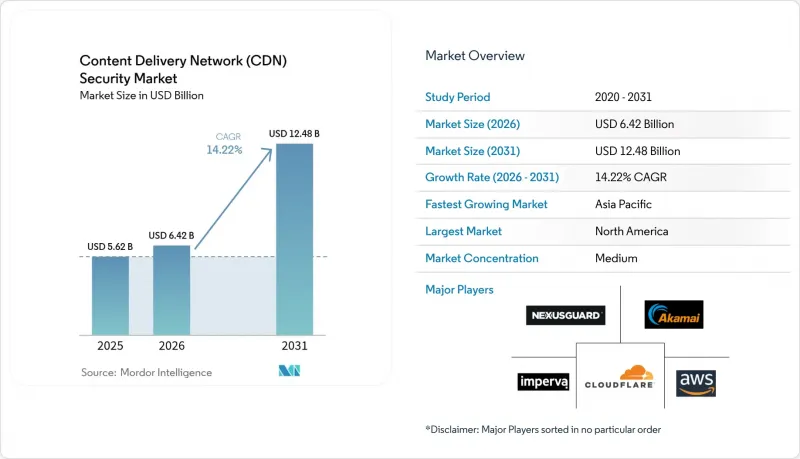
本報告按組織規模(中小企業、大型企業)、安全類型(DDoS防護、 網路應用程式防火牆(WAF)、其他)、最終用戶產業(媒體和娛樂、銀行、金融服務和保險(BFSI)、其他)、部署模式(雲端、本地部署)和地區進行細分。市場預測以美元(USD)計價。
全球內容傳遞網路(CDN) 安全市場趨勢與洞察
DDoS/L-7攻擊的頻率和複雜性日益增加
根據 Cloudflare 的遙測數據,預計 2025 年第一季網路層攻擊將年增 509%, Terabit級泛光攻擊將變得司空見慣。多向量攻擊結合了 SYN泛光和 Mirai 殭屍網路,而 CLDAP 和 ESP 等反射技術分別激增 3488% 和 2301%。 「地毯式轟炸」策略在 2024 年佔所有攻擊的 82.78%,迫使企業採用全天候運作而非流量分流方法。在地緣政治緊張局勢加劇駭客行動主義的背景下,金融服務業仍然是主要目標。 Akamai 記錄顯示,2023 年針對該產業的攻擊事件增加了 154%。 CDN 安全廠商目前正在將機器學習 (ML) 驅動的異常評分功能整合到邊緣存取點 (PoP) 中,以區分合法的微突發流量和惡意泛光攻擊。
OTT影片和即時串流媒體流量的快速成長
由於用戶流失率與串流緩衝直接相關,各大平台紛紛部署多 CDN 配置和 DRM 浮水印技術。 ContentArmor 和 Limelight 已升級其浮水印以打擊盜版,並將其直接整合到分送層。 Qwilt 的邊緣原生基礎設施降低了首幀延遲,但其靠近用戶也擴大了憑證人員編制和令牌竊取的攻擊面。因此,此安全堆疊整合了會話熵檢查和令牌綁定,同時又不會對直播體育賽事所需的延遲預算造成過大的影響。
全球網路安全專家短缺
在已通報的資料外洩事件中,46%針對員工人數少於1000人的公司;勒索軟體攻擊事件中,82%針對類似規模的公司。大學平均擁有多達1580個外部域名,但往往缺乏安全團隊來加強這些域名的安全防護。雖然供應商現在提供一鍵式配置預設和人工智慧驅動的安全分流功能,但長期存在的人才短缺問題正在減緩資源有限的買家對CDN安全市場的接受度。
細分市場分析
大型企業擁有涵蓋DDoS、WAF、機器人和零信任層等複雜基礎設施,以及充足的安全預算,預計2025年將佔總收入的74.85%。 NEC為其全球12萬名員工部署了Zscaler,集中管理網際網路和私人應用程式的存取。同時,中小企業(SME)的複合年成長率(CAGR)最高,達到14.31%,曾經僅限於財富500強企業使用的工具透過託管雲模式得以普及。 Cloudflare與樂天移動(Rakuten Mobile)合作,為日本中小企業提供打包的零信任服務。儘管人才短缺和成本敏感度依然存在,但簡化的控制面板和付費使用制正在推動這些服務的普及。
受PCI DSS v4.0強制腳本監控的推動, 網路應用程式防火牆(WAF)預計到2025年將佔據46.65%的市場佔有率。 Fortinet的「FortiAppSec Cloud」將WAF與效能分析結合,簡化了部署流程。反機器人措施正以15.02%的複合年成長率成長,用於應對人工智慧驅動的網頁抓取和憑證濫用。 Cloudflare的「AI Labyrinth」產生誘餌頁面來捕捉惡意爬蟲。同時,HUMAN Security聲稱其智慧指紋辨識技術可實現99.9%的偵測準確率。隨著攻擊者將機器學習武器化,結合WAF、反機器人措施和API保護的多層防禦有望塑造CDN安全市場的未來。
區域分析
到2025年,北美將佔全球收入的32.55%。成熟的合規體系和高人均網路安全支出正在推動網路安全技術的普及。 Zscaler在奧克拉荷馬州州的部署攔截了34,000次加密威脅和1760萬次策略違規,證明了大規模零信任架構的可行性。
亞太地區正以14.86%的複合年成長率快速成長。根據Akamai的數據,到2024年,亞太地區網站遭受的網路應用攻擊將達到510億次,年增73%。澳洲、印度和新加坡受到的衝擊尤其嚴重。樂天行動和Cloudflare的合作正在將零信任管理模式商業化,服務日本本土中小企業。此外,日本網路保險市場正以每年約50%的速度成長。
在歐洲,儘管DORA和GDPR等法規對營運和資料保護的要求日益嚴格,但CDN市場仍維持穩定成長。銀行正在改造API和WAF控制功能以進行彈性測試,愛沙尼亞資訊系統管理局則利用Cloudflare來保護該國的數位服務。拉丁美洲和非洲市場仍在發展中,但CDNetworks目前已在20個拉丁美洲國家運營接入點(PoP),服務6億用戶,為CDN安全市場的未來發展奠定了基礎。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- DDoS/L-7攻擊的頻率和複雜性日益增加
- OTT影片和即時串流媒體流量的快速成長
- 企業向多重雲端和邊緣架構遷移
- 監管運作要求和資料保護義務(例如,DORA、PCI DSS v4)
- 透過邊緣 PoP 整合實現嵌入式零信任控制。
- 透過驅動安全整合 CDN 的演算法來控制網路成本。
- 市場限制因素
- 全球網路安全專家短缺
- 中小企業持續運作的因應措施總擁有成本較高
- IPv6流量暴露了傳統過濾設備的漏洞。
- 由於邊緣接入點的能源成本上升,基地擴張速度放緩。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 按組織規模
- 中小企業
- 大公司
- 按安全類型
- DDoS防護
- 網路應用程式防火牆(WAF)
- 防止機器人攻擊和螢幕擷取攻擊
- 資料安全和內容完整性
- 其他
- 按最終用戶行業分類
- 媒體與娛樂
- 零售與電子商務
- BFSI
- 資訊科技/通訊
- 醫療保健和生命科學
- 政府/公共部門
- 教育
- 其他
- 部署模式
- 雲
- 現場
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 東南亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Akamai Technologies Inc.
- Amazon Web Services Inc.(CloudFront)
- Cloudflare Inc.
- Google LLC(Cloud CDN)
- Microsoft Corp.(Azure Front Door)
- Imperva Inc.
- Fastly Inc.
- Edgio Inc.(Limelight Networks)
- Verizon Media Platform
- Radware Ltd.
- F5 Inc.
- StackPath LLC
- G-Core Labs SA
- Alibaba Cloud(Alibaba Group)
- Corero Network Security plc
- Nexusguard Ltd.
- CDNetworks Inc.
- Neustar Security Services
- Akamai(Prolexic)
- NETSCOUT Systems(Arbor)
第7章 市場機會與未來展望
According to Mordor Intelligence, the CDN security market size was valued at USD 5.62 billion in 2025 and estimated to grow from USD 6.42 billion in 2026 to reach USD 12.48 billion by 2031, at a CAGR of 14.22% during the forecast period (2026-2031).
This report is Segmented by Organization Size (SMBs, Large Enterprises), Security Type (DDoS Protection, Web Application Firewall (WAF), and More), End-User Industry (Media and Entertainment, BFSI, and More), Deployment Mode (Cloud, On-Premises), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Content Delivery Network (CDN) Security Market Trends and Insights
Rising Frequency and Sophistication of DDoS / L-7 Attacks
Cloudflare's telemetry shows network-layer assaults ballooned 509% year-over-year in Q1 2025, while terabit-scale floods are now routine. Multi-vector campaigns combine SYN floods with Mirai botnets, and reflection methods such as CLDAP and ESP have spiked 3,488% and 2,301% respectively.Carpet-bombing tactics, 82.78% of all observed attacks in 2024, force organizations to adopt always-on defenses instead of traffic-divert approaches. Financial services remain the primary target as geopolitical tensions spur hacktivism; Akamai logged a 154% rise in sector-focused events in 2023. CDN security vendors now embed ML-driven anomaly scoring at edge PoPs to distinguish legitimate microbursts from malicious floods.
Rapid Growth in OTT Video and Real-Time Streaming Traffic
Subscriber churn correlates directly with stream buffering, prompting platforms to deploy multi-CDN setups plus DRM watermarking. ContentArmor and Limelight upgraded forensic watermarking to curb piracy, integrating directly into delivery layers. Edge-native infrastructure from Qwilt reduces first-frame latency, but its proximity to viewers exposes surface area to credential-stuffing and token theft. Security stacks therefore integrate per-session entropy checks and token binding without inflating latency budgets crucial for live sports.
Global Shortage of Skilled Cyber-Security Practitioners
Forty-six percent of reported breaches hit firms with under 1,000 staff, and 82% of ransomware incidents target the same cohort. Universities average up to 1,580 public-facing domains yet often lack security teams to harden them. Providers now ship point-and-click configuration presets and AI triage, but a persistent talent gap slows CDN Security market adoption among resource-constrained buyers.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise Shift to Multi-Cloud and Edge Architectures
- Regulatory Uptime and Data-Protection Mandates
- High TCO of Always-On Mitigation for SMEs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large enterprises controlled 74.85% of 2025 revenue thanks to complex infrastructures and deep security budgets that span DDoS, WAF, bot and zero-trust layers. NEC rolled out Zscaler for 120,000 global employees to centralize internet and private-app access. Conversely, SMEs show the strongest 14.31% CAGR as managed cloud models democratize tools once reserved for Fortune 500. Cloudflare's partnership with Rakuten Mobile offers packaged zero-trust services aimed at Japan's small-business segment. Talent shortages and cost sensitivities persist, yet simplified dashboards and usage-based pricing unlock adoption.
Web Application Firewalls held 46.65% share in 2025, bolstered by PCI DSS v4.0 script-monitoring mandates. Fortinet's FortiAppSec Cloud combines WAF with performance analytics to streamline deployment. Bot mitigation, expanding 15.02% CAGR, addresses AI-driven scraping and credential abuse. Cloudflare's AI Labyrinth generates decoy pages to trap illegal crawlers, while HUMAN Security claims 99.9% detection accuracy via intelligent fingerprinting. As attackers weaponize machine learning, layered defenses that join WAF, bot and API protection will shape the CDN Security market trajectory.
Complete Report Scope:
- By Organization Size
- Small and Medium-Sized Businesses (SMBs)
- Large Enterprises
- By Security Type
- DDoS Protection
- Web Application Firewall (WAF)
- Bot Mitigation and Screen-Scraping Protection
- Data Security and Content Integrity
- Others
- By End-user Industry
- Media and Entertainment
- Retail and E-commerce
- BFSI
- IT and Telecom
- Healthcare and Life Sciences
- Government and Public Sector
- Education
- Others
- By Deployment Mode
- Cloud
- On-Premise
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 32.55% of global revenue in 2025. Mature compliance regimes and high per-capita cyber spend underpin adoption. Oklahoma's statewide Zscaler roll-out blocked 34,000 encrypted threats and 17.6 million policy violations, proving zero-trust viability at scale.
Asia-Pacific is expanding at a 14.86% CAGR. Akamai logged 51 billion web-app attacks against APAC sites in 2024, a 73% jump, with Australia, India and Singapore worst hit. Rakuten Mobile's partnership with Cloudflare commercializes managed zero-trust for local SMEs, while Japan's cyber insurance market is growing nearly 50% a year.
Europe sees steady growth as DORA and GDPR tighten operational and data-protection requirements. Banks retrofit API and WAF controls for resilience testing, and Estonia's Information System Authority relies on Cloudflare to safeguard sovereign digital services. Latin America and Africa remain nascent; CDNetworks now operates PoPs in 20 LATAM countries to reach 600 million subscribers, laying groundwork for future CDN Security market uptake.
- Akamai Technologies Inc.
- Amazon Web Services Inc. (CloudFront)
- Cloudflare Inc.
- Google LLC (Cloud CDN)
- Microsoft Corp. (Azure Front Door)
- Imperva Inc.
- Fastly Inc.
- Edgio Inc. (Limelight Networks)
- Verizon Media Platform
- Radware Ltd.
- F5 Inc.
- StackPath LLC
- G-Core Labs S.A.
- Alibaba Cloud (Alibaba Group)
- Corero Network Security plc
- Nexusguard Ltd.
- CDNetworks Inc.
- Neustar Security Services
- Akamai (Prolexic)
- NETSCOUT Systems (Arbor)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising frequency and sophistication of DDoS / L-7 attacks
- 4.2.2 Rapid growth in OTT video and real-time streaming traffic
- 4.2.3 Enterprise shift to multi-cloud and edge architectures
- 4.2.4 Regulatory uptime and data-protection mandates (e.g., DORA, PCI DSS v4)
- 4.2.5 Edge PoP consolidation enabling embedded zero-trust controls
- 4.2.6 Algorithmic network-cost steering driving security-integrated CDNs
- 4.3 Market Restraints
- 4.3.1 Global shortage of skilled cyber-security practitioners
- 4.3.2 High TCO of always-on mitigation for SMEs
- 4.3.3 IPv6 traffic exposing gaps in legacy filtering appliances
- 4.3.4 Rising energy costs at edge PoPs slowing footprint expansion
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Organization Size
- 5.1.1 Small and Medium-Sized Businesses (SMBs)
- 5.1.2 Large Enterprises
- 5.2 By Security Type
- 5.2.1 DDoS Protection
- 5.2.2 Web Application Firewall (WAF)
- 5.2.3 Bot Mitigation and Screen-Scraping Protection
- 5.2.4 Data Security and Content Integrity
- 5.2.5 Others
- 5.3 By End-user Industry
- 5.3.1 Media and Entertainment
- 5.3.2 Retail and E-commerce
- 5.3.3 BFSI
- 5.3.4 IT and Telecom
- 5.3.5 Healthcare and Life Sciences
- 5.3.6 Government and Public Sector
- 5.3.7 Education
- 5.3.8 Others
- 5.4 By Deployment Mode
- 5.4.1 Cloud
- 5.4.2 On-Premise
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Southeast Asia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Akamai Technologies Inc.
- 6.4.2 Amazon Web Services Inc. (CloudFront)
- 6.4.3 Cloudflare Inc.
- 6.4.4 Google LLC (Cloud CDN)
- 6.4.5 Microsoft Corp. (Azure Front Door)
- 6.4.6 Imperva Inc.
- 6.4.7 Fastly Inc.
- 6.4.8 Edgio Inc. (Limelight Networks)
- 6.4.9 Verizon Media Platform
- 6.4.10 Radware Ltd.
- 6.4.11 F5 Inc.
- 6.4.12 StackPath LLC
- 6.4.13 G-Core Labs S.A.
- 6.4.14 Alibaba Cloud (Alibaba Group)
- 6.4.15 Corero Network Security plc
- 6.4.16 Nexusguard Ltd.
- 6.4.17 CDNetworks Inc.
- 6.4.18 Neustar Security Services
- 6.4.19 Akamai (Prolexic)
- 6.4.20 NETSCOUT Systems (Arbor)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 全球內容傳遞網路(CDN) 市場規模、佔有率、趨勢和成長分析報告,2026-2034 年
 2026-2030年全球內容傳遞網路(CDN)市場
 OTT內容傳遞網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)內容傳送:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 商業P2P CDN市場-2026-2032年全球市場預測雲端內容傳遞網路市場:按元件、內容類型、部署模式、組織規模和最終用戶分類-2026-2032年全球市場預測內容傳遞網路(CDN) 市場:2026-2032 年全球市場預測(按服務類型、內容類型、部署模式、組織規模和最終用戶分類)
 2026年全球固定內容及應用市場報告全球商業P2P CDN市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 內容傳遞網路市場 - 全球產業規模、佔有率、趨勢、機會、預測:按組件、類型、服務供應商類型、最終用戶、內容類型、地區和競爭格局分類,2021-2031年