


 |
市場調查報告書
商品編碼
2122656
功率半導體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Power Semiconductor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年功率半導體市值為 568.7 億美元,預計到 2031 年將達到 782.5 億美元,而 2026 年為 599.8 億美元,預測期(2026-2031 年)的複合年成長率為 5.46%。
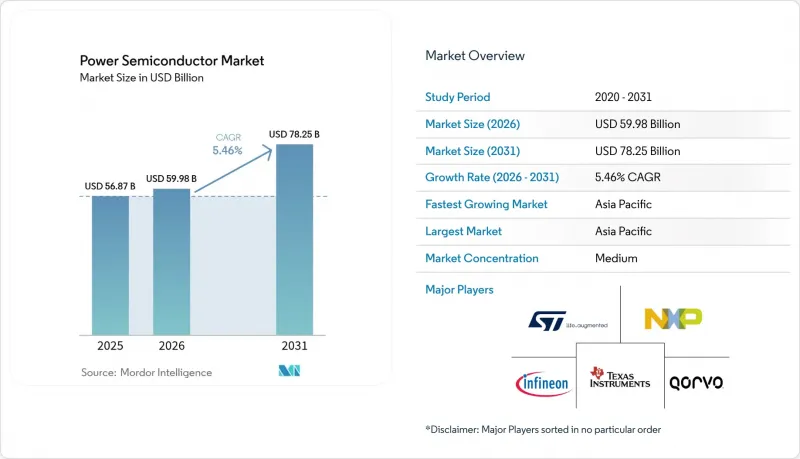
本報告按組件(分離元件、模組、功率積體電路)、材料(矽、碳化矽、氮化鎵及其他)、終端用戶產業(汽車、消費性電子、資訊通訊技術、工業製造、能源電力、航太與國防、醫療設備及其他)和地區進行細分。市場預測以美元計價。
全球功率半導體市場趨勢與洞察
電動車和充電基礎設施需求激增
電動車 (EV) 越來越依賴碳化矽 (SiC) MOSFET 來提高動力系統效率並縮短充電時間。汽車製造商在向 800V 系統過渡時,指定使用 SiC 來降低逆變器損耗,例如安森美半導體 (ON Semiconductor) 和大眾汽車 (Volkswagen) 之間的 FORVIA(供應保證協議)就證明了這一點。 FORVIA 協定確保了從晶片到模組的垂直整合和穩定供應,從而降低了分配風險。並聯直流快速充電器的引入需要功率範圍從 8 kW 到 1 MW 的功率模組,這實際上使僅汽車應用就需要的 SiC 需求加倍。由於汽車級產品的良率仍然是一個挑戰,整合元件製造商 (IDM) 正在提高其內部基板生產能力,以穩定成本曲線並確保利潤率。
5G基地台的分佈
在6GHz以下和毫米波頻段,氮化鎵(GaN)高電子移動性電晶體的增益和效率均高於LDMOS。隨著電信業者應對不斷飆升的能源成本和日益成長的小型基地台密度,預計到2010年底,GaN的出貨量將增加四倍。恩智浦半導體(NXP)提供結合了矽LDMOS和GaN晶片的多晶片大規模MIMO模組,這些模組整合了天線陣列並簡化了散熱設計。功率半導體供應商正在採用燒結晶片黏接材料來應對超過225 度C的熱點溫度。隨著通訊業日益關注整體擁有成本(TCO),效率的逐步提升正在降低營運成本(OPEX),從而鞏固GaN在下一階段部署中的應用。
矽晶圓供應短缺的週期
目前晶圓總需求已超過核定產能,記憶體供應商的庫存削減正在扭曲短期採購行為。地緣政治摩擦推高了晶圓廠建設成本,而用水限制則限制了在乾旱地區購買新廠址。來自中國的新參與企業正展開價格戰,擠壓整個供應鏈的利潤空間。儘管前端設備訂單已顯現復甦跡象,但個人電腦和智慧型手機等終端市場的低迷正在減緩產量的復甦,這反映出一種結構性失衡,而非週期性波動。
細分市場分析
預計到2025年,功率積體電路將顯著提升功率半導體市場規模,並預計2031年將以6.02%的複合年成長率成長。汽車電池管理單元需要在緊湊的電源管理積體電路(PMIC)封裝內整合多軌穩壓器和功能安全診斷功能。英飛凌符合ISO 26262標準的產品OPTIREG TLF35585支援安全相關的電控系統,體現了單晶片電源管理的發展趨勢。分立元件在高電流路徑中仍然至關重要,佔據44.60%的市場。然而,隨著設計人員在空間受限的子系統中越來越傾向於選擇成本最佳化的模組和積體電路解決方案,分立元件的市場佔有率正在逐漸下降。
供應商的藍圖正在將GaN或SiC晶片整合到智慧功率模組中,這些模組集柵極驅動、感測和保護功能於一體,從而縮短逆變器和充電器組件的上市時間。模組整合使缺乏內部封裝技術的中型工業和住宅能源客戶受益。同時,家用電子電器ODM廠商持續在轉接器設計中採購分離式MOSFET,以利用基板級柔軟性和價格優勢。分離式、模組和積體電路形式的共存豐富了功率半導體市場,從而實現了性能和成本之間的最佳平衡。
區域分析
預計到2025年,亞太地區將佔據功率半導體市場51.35%的佔有率,並在2031年之前保持6.74%的複合年成長率。中國在政府補貼和垂直整合供應鏈的支持下,正大力推動碳化矽(SiC)和氮化鎵(GaN)產能的擴張。印度正在加速建設其OSAT園區,該園區耗資7600印度盧比,目標是日產1500萬顆晶片,顯示其有意將組裝製程遷回國內。台灣和韓國分別繼續保持其在先進封裝和記憶體領域的領先地位,而日本則在上游材料領域鞏固主導。
北美正受惠於《晶片創新與生產法案》(CHIPS Act)提供的500億美元激勵措施,這些措施正在加速現有工廠的改造以及Wolfspeed、博世和其他國際新參與企業新建晶圓廠的進程。汽車、國防和資料中心叢集正在集中需求,並提升在地採購需求。 SEMI預測,到2027年,該地區晶圓廠的資本投資將加倍,達到247億美元,從而支持長期規模成長。
歐洲正利用其汽車和可再生能源政策的協調一致,加速碳化矽(SiC)和氮化鎵(GaN)技術的應用。德國德勒斯登核准的價值50億歐元的工廠項目,便是公私合營提升能源自給自足能力的典範。法國和義大利也提供額外津貼,以維持尖端組件和基板的專業水平。在中東、非洲和拉丁美洲等新興市場,成本意識依然很強,寬禁帶(WBG)技術正逐步應用於公用事業規模的太陽能發電和鐵路電氣化項目,同時仍繼續採用成熟的矽平台。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電動車和充電基礎設施需求激增
- 5G基地台的分佈
- 可再生能源主導的電力轉換市場成長
- 工業自動化和電機驅動系統的升級
- 高空平台系統與全電動飛機動力傳動系統
- 亞洲快速充電相容型兩輪/三輪電動車架構
- 市場限制因素
- 矽晶圓供應短缺週期
- WBG元件設計高成本/複雜
- 高密度電動車逆變器的熱極限
- 氮化鎵外延設備的出口限制
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資分析
第5章 市場規模與成長預測
- 按組件
- 離散的
- 整流器
- 雙極
- MOSFET
- IGBT
- 其他分立元件(閘流體、HEMT 等)
- 模組
- 閘流體模組
- IGBT模組
- MOSFET模組
- 智慧型電源模組(IPM)
- 功率積體電路
- PMIC(多通道)
- 開關穩壓器(AC/DC、DC/DC、隔離式/非隔離式)
- 線性穩壓器
- 電池管理積體電路
- 其他電源積體電路
- 離散的
- 材料
- 矽
- 碳化矽(SiC)
- 氮化鎵(GaN)
- 其他
- 按最終用戶行業分類
- 車
- 家用電子產品和家用電器
- 資訊通訊科技(ICT)
- 工業和製造業
- 能源與電力(可再生能源、電網)
- 航太/國防
- 醫療設備
- 其他(鐵路、船)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Infineon Technologies AG
- Texas Instruments Incorporated
- Qorvo Inc.
- STMicroelectronics NV
- NXP Semiconductors NV
- ON Semiconductor Corporation
- Renesas Electronics Corporation
- Broadcom Inc.
- Toshiba Corporation
- Mitsubishi Electric Corporation
- Fuji Electric Co., Ltd.
- Semikron Danfoss GmbH and Co. KG
- Wolfspeed Inc.
- ROHM Co., Ltd.
- Vishay Intertechnology Inc.
- Nexperia BV
- Alpha and Omega Semiconductor Ltd.
- Magnachip Semiconductor Corp.
- Microchip Technology Inc.
- Littelfuse Inc.
- Navitas Semiconductor Corp.
- Power Integrations Inc.
- Monolithic Power Systems Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the power semiconductor market size was valued at USD 56.87 billion in 2025 and estimated to grow from USD 59.98 billion in 2026 to reach USD 78.25 billion by 2031, at a CAGR of 5.46% during the forecast period (2026-2031).
This report is Segmented by Component (Discrete, Modules, Power IC), Material (Silicon, Silicon Carbide, Gallium Nitride, Others), End-User Industry (Automotive, Consumer Electronics and Appliances, ICT, Industrial and Manufacturing, Energy and Power, Aerospace and Defense, Healthcare and Equipment, Others), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Power Semiconductor Market Trends and Insights
Surging Demand for EVs and Charging Infrastructure
Electric vehicles increasingly rely on SiC MOSFETs that raise drivetrain efficiency and shorten charging times. Automakers shifting to 800 V systems specify SiC to trim inverter losses, evidenced by FORVIAs, such as onsemi's agreement with Volkswagen, secure vertically integrated chip-to-module deliveries, mitigating allocation risks. Parallel DC fast-charger roll-outs require 8 kW to 1 MW power blocks, effectively doubling SiC demand from vehicle content alone. Automotive-grade yields stay challenging, so IDMs add captive substrate capacity to stabilize cost curves and safeguard margins.
Proliferation of 5G Base-Stations
GaN high-electron-mobility transistors deliver higher gain and efficiency than LDMOS at sub-6 GHz and mmWave frequencies. Small-cell densification pushes GaN shipments to quadruple by decade-end as operators combat escalating energy bills. NXP couples Si LDMOS with GaN die in multichip massive-MIMO modules that integrate antenna arrays and simplify thermal design. Power semiconductor suppliers add sintered die-attach materials to cope with hot-spot temperatures above 225 °C. The telecom sector's focus on total-cost-of-ownership converts incremental efficiency gains into reduced opex, cementing GaN adoption in next-phase rollouts.
Silicon Wafer Supply Tightness Cycles
Total wafer demand now eclipses qualified capacity, and inventory drawdown at memory suppliers distorts short-term purchasing behavior . Geopolitical friction inflates fab-construction costs, while water-usage limits restrict greenfield sites in drought-prone zones. Chinese entrants pursue price competition that compresses margins across the chain. Although front-end equipment bookings hint at recovery, end-market weakness in PCs and smartphones tempers volume pick-up, exposing structural rather than cyclical imbalances.
Other drivers and restraints analyzed in the detailed report include:
- Renewables-Led Power Conversion Growth
- Industrial Automation and Motor-Drive Upgrades
- High Cost / Design Complexity of WBG Devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Power integrated circuits contributed significantly to the power semiconductor market size in 2025 and will climb at a 6.02% CAGR through 2031. Automotive battery-management units require multi-rail regulators and functional-safety diagnostics delivered in a compact PMIC footprint. Infineon's ISO 26262-compliant OPTIREG TLF35585 underpins safety-related electronic control units, illustrating the trend toward single-chip power management . Discrete devices remain indispensable for high-current paths, preserving 44.60% revenue share; nevertheless, the discrete share edges lower as designers favor cost-optimized module or IC solutions in space-constrained subsystems.
Supplier roadmaps bundle GaN or SiC dies within intelligent power modules that integrate gate drive, sensing, and protection, shortening time-to-market for inverter and charger assemblies. Module consolidation benefits mid-volume industrial and residential energy customers who lack in-house packaging expertise. Conversely, consumer-electronics ODMs still procure discrete MOSFETs for adapter designs to exploit board-level flexibility and price advantages. The coexistence of discrete, module, and IC formats enriches the power semiconductor market, enabling tailored performance-cost trade-offs.
Complete Report Scope:
- By Component
- Discrete
- Rectifier
- Bipolar
- MOSFET
- IGBT
- Other Discrete Components (Thyristor, HEMT, etc.)
- Modules
- Thyristor Module
- IGBT Module
- MOSFET Module
- Intelligent Power Module (IPM)
- Power IC
- PMIC (Multichannel)
- Switching Regulators (AC/DC, DC/DC, Iso/Non-iso)
- Linear Regulators
- Battery Management IC
- Other Power ICs
- Discrete
- By Material
- Silicon
- Silicon Carbide (SiC)
- Gallium Nitride (GaN)
- Others
- By End-user Industry
- Automotive
- Consumer Electronics and Appliances
- ICT (IT and Telecom)
- Industrial and Manufacturing
- Energy and Power (Renewables, Grid)
- Aerospace and Defense
- Healthcare Equipment
- Others (Rail, Marine)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia Pacific accounted for 51.35% of the power semiconductor market share in 2025 and sustained a 6.74% CAGR through 2031. China spearheads SiC and GaN capacity ramps, aided by state subsidies and vertically integrated supply chains. India fast-tracks an INR 7,600 crore OSAT campus targeting 15 million units per day, signaling intent to onshore assembly. Taiwan and South Korea guard leadership in advanced packaging and memory, respectively, while Japan fortifies upstream materials command.
North America benefits from USD 50 billion in CHIPS Act incentives that unlock brownfield conversions and greenfield fabs by Wolfspeed, Bosch, and overseas entrants. Automotive, defense, and data-center clusters concentrate demand, boosting local content requirements. SEMI projects regional fab-equipment outlays doubling to USD 24.7 billion by 2027, underscoring long-term scale-up .
Europe leverages its automotive and renewable energy policy alignment to catalyze SiC and GaN uptake. Germany's EUR 5 billion Dresden fab approval exemplifies public-private alignment to elevate self-sufficiency. France and Italy offer additional grant packages to preserve leading-edge module and substrate know-how. Emerging markets across the Middle East, Africa, and Latin America stay value-conscious, adopting mature silicon platforms while gradually trialing WBG for utility-scale solar and railway electrification.
- Infineon Technologies AG
- Texas Instruments Incorporated
- Qorvo Inc.
- STMicroelectronics N.V.
- NXP Semiconductors N.V.
- ON Semiconductor Corporation
- Renesas Electronics Corporation
- Broadcom Inc.
- Toshiba Corporation
- Mitsubishi Electric Corporation
- Fuji Electric Co., Ltd.
- Semikron Danfoss GmbH and Co. KG
- Wolfspeed Inc.
- ROHM Co., Ltd.
- Vishay Intertechnology Inc.
- Nexperia B.V.
- Alpha and Omega Semiconductor Ltd.
- Magnachip Semiconductor Corp.
- Microchip Technology Inc.
- Littelfuse Inc.
- Navitas Semiconductor Corp.
- Power Integrations Inc.
- Monolithic Power Systems Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for EVs and charging infrastructure
- 4.2.2 Proliferation of 5G base-stations
- 4.2.3 Renewables-led power conversion growth
- 4.2.4 Industrial automation and motor-drive upgrades
- 4.2.5 HAPS and all-electric aircraft powertrains
- 4.2.6 Fast-charging 2-/3-wheeler EV architectures in Asia
- 4.3 Market Restraints
- 4.3.1 Silicon wafer supply tightness cycles
- 4.3.2 High cost / design complexity of WBG devices
- 4.3.3 Thermal limits in high-density EV inverters
- 4.3.4 Export controls on GaN epitaxy tools
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Discrete
- 5.1.1.1 Rectifier
- 5.1.1.2 Bipolar
- 5.1.1.3 MOSFET
- 5.1.1.4 IGBT
- 5.1.1.5 Other Discrete Components (Thyristor, HEMT, etc.)
- 5.1.2 Modules
- 5.1.2.1 Thyristor Module
- 5.1.2.2 IGBT Module
- 5.1.2.3 MOSFET Module
- 5.1.2.4 Intelligent Power Module (IPM)
- 5.1.3 Power IC
- 5.1.3.1 PMIC (Multichannel)
- 5.1.3.2 Switching Regulators (AC/DC, DC/DC, Iso/Non-iso)
- 5.1.3.3 Linear Regulators
- 5.1.3.4 Battery Management IC
- 5.1.3.5 Other Power ICs
- 5.1.1 Discrete
- 5.2 By Material
- 5.2.1 Silicon
- 5.2.2 Silicon Carbide (SiC)
- 5.2.3 Gallium Nitride (GaN)
- 5.2.4 Others
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Consumer Electronics and Appliances
- 5.3.3 ICT (IT and Telecom)
- 5.3.4 Industrial and Manufacturing
- 5.3.5 Energy and Power (Renewables, Grid)
- 5.3.6 Aerospace and Defense
- 5.3.7 Healthcare Equipment
- 5.3.8 Others (Rail, Marine)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 United Kingdom
- 5.4.2.4 Italy
- 5.4.2.5 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 South Korea
- 5.4.3.4 India
- 5.4.3.5 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East
- 5.4.5.1 Israel
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 United Arab Emirates
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Infineon Technologies AG
- 6.4.2 Texas Instruments Incorporated
- 6.4.3 Qorvo Inc.
- 6.4.4 STMicroelectronics N.V.
- 6.4.5 NXP Semiconductors N.V.
- 6.4.6 ON Semiconductor Corporation
- 6.4.7 Renesas Electronics Corporation
- 6.4.8 Broadcom Inc.
- 6.4.9 Toshiba Corporation
- 6.4.10 Mitsubishi Electric Corporation
- 6.4.11 Fuji Electric Co., Ltd.
- 6.4.12 Semikron Danfoss GmbH and Co. KG
- 6.4.13 Wolfspeed Inc.
- 6.4.14 ROHM Co., Ltd.
- 6.4.15 Vishay Intertechnology Inc.
- 6.4.16 Nexperia B.V.
- 6.4.17 Alpha and Omega Semiconductor Ltd.
- 6.4.18 Magnachip Semiconductor Corp.
- 6.4.19 Microchip Technology Inc.
- 6.4.20 Littelfuse Inc.
- 6.4.21 Navitas Semiconductor Corp.
- 6.4.22 Power Integrations Inc.
- 6.4.23 Monolithic Power Systems Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 汽車智慧功率元件市場:依產品類型、應用、車輛類型、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 世界功率半導體市場、材料與技術分離式功率電子市場:按應用、類型、最終用途、技術、國家和地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測汽車智慧功率元件市場:全球產業分析、市場規模及佔有率和預測(2026-2033 年),按元件整合度、額定功率、應用、電壓範圍、國家和地區分類藍寶石功率元件市場:全球產業分析、市場規模、市場佔有率及2026年至2033年預測(依元件類型、應用、最終用戶、國家及地區分類)
 功率半導體市場:2026-2032年全球市場預測(依元件類型、材料、電壓範圍、晶圓尺寸、終端用戶產業及通路分類)
 DRAM封裝產業的熱界面材料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031年)
 功率半導體市場預測至2034年-按裝置類型、材料類型、封裝類型、應用和地區分類的全球分析
 提高人工智慧伺服器的電源完整性:矽電容器和MLCC的演進作用。
 新一代功率半導體市場-全球產業規模、佔有率、趨勢、機會與預測:按類型、組件、應用、地區和競爭格局分類,2021-2031年