


 |
市場調查報告書
商品編碼
2122642
計程車:市場佔有率分析、產業趨勢和統計數據、成長預測(2026-2031 年)Taxi - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
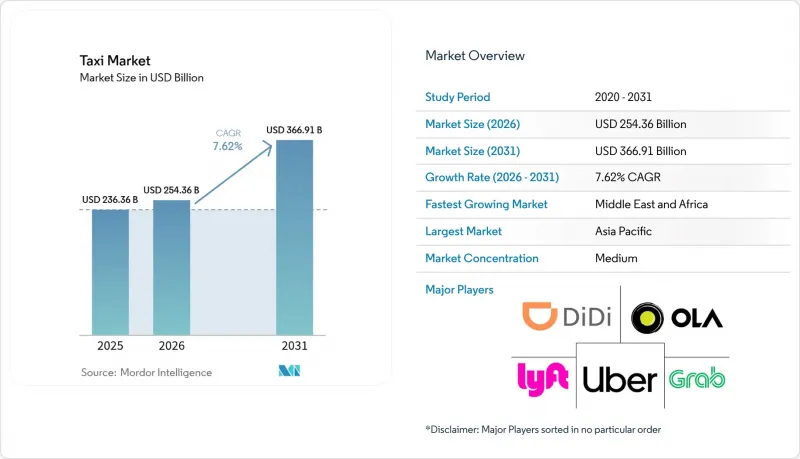
據 Mordor Intelligence 稱,2025 年計程車市場價值為 2363.6 億美元,預計到 2031 年將達到 3669.1 億美元,而 2026 年為 2543.6 億美元,預測期內(2026-2031 年)的複合成長率預計為 7.62%。
本報告按預訂類型(線上和線下預訂)、服務類型(叫車、共乘、企業/機構合約)、車輛類型(乘用車、摩托車/踏板車、廂型車/MPV、自動三輪車/嘟嘟車)、動力類型(內燃機、電動、混合)和地區進行細分。市場預測以美元計價。
全球計程車市場趨勢及洞察
智慧型手機和網路的快速普及
隨著智慧型手機在主要大都市地區的普及率超過五分之四,平台可以利用演算法更快地匹配乘客和司機,將主要城市的平均等待時間從15-20分鐘縮短到5分鐘內。 5G的廣泛部署使得更精確的定位資訊成為可能,從而提高了車輛運轉率並減少了車輛的空轉里程。更快的資料通訊速度支援應用程式內影片廣告和即時司機導航,進而催生了多元化的收入來源。在已開發市場,整合到叫車應用中的行動錢包交易量已占到總交易量的五分之四以上,這不僅降低了現金交易的風險,也縮短了機場的等待時間。在新興市場,網路存取的改善正推動著人們向數位化預訂方式的轉變,從而繞過了傳統的叫車系統。
都市區擁擠和汽車擁有率下降
在人口密集的城市,車輛使用率往往略有下降,促使居民以無需支付停車費的叫車服務取代私家車。不斷上漲的燃油價格,加上地方政府徵收的擁擠費,推高了汽車擁有成本,使得計程車服務更具吸引力。尤其是共乘服務,可以節省高達40%的費用,因此越來越受歡迎。 25至35歲的年輕消費者對此趨勢最為敏感,他們更傾向於選擇「交通行動服務(MaaS)」的捆綁式訂閱服務,這類服務將計程車、鐵路、公車和微出行整合到一個應用程式中。在美國,交通堵塞造成的損失每年超過1000億美元,城市當局面臨優先發展高載客率交通途徑的政治壓力,間接刺激了計程車市場的需求。
許可證制度改革和監管力道加強
各地監管機構正在對其計程車牌照系統進行現代化改造,並收緊背景調查規定,這增加了叫車平台和傳統計程車業者的合規成本。西雅圖計劃在2026年3月前逐步淘汰其牌照系統,而紐約市則強制要求到2025年3月前,其一半的計程車必須配備無障礙設施。在新加坡,監管機構以反壟斷為由阻止了Grab對Trans-Cab的收購計劃,這表明平台整合正受到更嚴格的審查。各地標準不一,增加了法律的複雜性,並可能減緩市場准入速度,從而抑制短期成長動能。
細分市場分析
預計到2025年,線上通路將佔計程車市場佔有率的63.78%,這顯示市場結構正向基於應用程式的需求聚合模式轉變。數位化預訂的興起強化了商業智慧循環,提高了需求預測的準確性,從而提高了資產利用率並縮短了乘客的等待時間。線下通路仍然重要,尤其是在老年人群以及仍允許在計程車牌照制度下街頭招手攔車的地區,但其成長速度落後於整體計程車市場。因此,營運商除了應用程式外,還在整合語音互動語音應答(IVR)和自助服務終端介面,以留住傳統用戶,同時引導他們使用數位化服務。
預計未來線上預訂量將以7.92%的複合年成長率成長。整合出行、支付和電子商務的超級應用將推動出行量的成長,尤其是在智慧型手機普及率超過五分之四的亞太地區特大城市。線上管道透過提供每次行程的詳細數據,支援精準的會員忠誠度計畫和動態定價,進而提升市場佔有率。基於合約的企業帳戶、機場營運權和強制性無障礙服務支撐著線下管道的複合年成長率。然而,預計到2031年,線下通路的收入構成比將降至計程車市場規模的三分之一以下。
預計到2025年,叫車將佔據計程車市場74.85%的佔有率,這主要得益於網路效應,它能確保更快的匹配速度和更透明的定價。領先的平台正在大力投資安全檢驗、即時監控和司機培訓,使其服務比非正規競爭對手更可靠。共乘服務預計將以7.78%的複合年成長率成長,超過整個計程車市場的成長速度,因為它們緩解了交通堵塞,並透過乘客分攤成本降低了單座費用。此外,各公司為減少車隊碳排放而設定的環保目標,也進一步推動了共乘的成長。
企業出行合約曾經主要由豪華車隊(黑色轎車)主導,如今卻擴大外包給提供電子收據和按座位計費的應用程式供應商。這些嵌入式數據使得建立碳排放報告儀錶板變得更加容易,而這已成為注重環境、社會和治理(ESG)的董事會的必備要求。雖然叫車在總預訂價值方面仍然佔據優勢,共乘正在實現更高的載客率和更優的資產利用率,尤其是在高峰時段,單人出行需要額外費用。
區域分析
到2025年,亞太地區將佔據全球計程車市場佔有率的37.42%。這主要得益於快速的都市化、超過五分之四的智慧型手機普及率以及摩托車計程車在人口密集地區的蓬勃發展。印度、越南和泰國等國政府推出的電動車補貼和營運許可證豁免等政策,正加速這些國家的車輛更新換代。日本現有的計程車業者正透過與優步(Uber)合作,將2萬輛計程車整合到其平台,以加強跨境數位化標準化。
預計到2031年,中東和非洲地區的複合年成長率將達到7.88%,這主要得益於各國數位經濟計畫和特大城市特大城市的推動。杜拜計程車公司計劃在2029年將約五分之四的乘車請求藍圖到電子預訂,並實現四分之一車隊的電氣化,以響應阿拉伯聯合大公國「2050年淨零排放」路線圖。在埃及、沙烏地阿拉伯和奈及利亞,叫車應用程式正在迅速普及,年輕且精通科技的群體正在超越傳統的調度模式。像Careem這樣的跨區域超級應用將支付、配送和交通運輸整合到一個平台上,從而提高了用戶留存率。由於合規遵循成本高昂,各國政府正在收緊對網路存取和資料隱私的監管,這為大型營運商創造了有利的環境。 Lyft於2025年4月收購FREENOW,使其在歐洲的業務範圍擴大了一倍,達到11個國家,每年可覆蓋約3000億次個人車輛出行。同時,德國各地市政委員會正在試行零排放區,這可能會比企業預期更快提高電動車的閾值。因此,成長速度將會放緩,但該平台仍保持正成長,因為它正將業務多元化,拓展至配送服務和訂閱式旅遊通行證領域。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 智慧型手機和網路的快速普及
- 都市區交通擁擠和私家車數量減少。
- 新興市場叫車平台的擴張
- 人工智慧驅動的動態路線規劃與定價最佳化
- 無障礙設施法規正在推動車輛現代化。
- 超級應用 API 整合正在推動嵌入式系統需求的成長。
- 市場限制因素
- 許可證制度的改革和監理機關執法力度的加大
- 日益激烈的價格競爭給司機的收入帶來了壓力。
- 公共電動車充電站數量有限,減緩了電動計程車的普及速度。
- 涉及追蹤行動軌跡的資料隱私訴訟
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按預訂類型
- 線上預訂
- 線下預訂
- 按服務類型
- 叫車
- 共乘
- 公司和機構的合約
- 車輛類型
- 搭乘用車
- 摩托車和踏板車
- 廂型車和多用途汽車
- 自動人力車和嘟嘟車
- 依推進類型
- 內燃機(ICE)
- 電的
- 混合
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 越南
- 其他亞太國家
- 中東和非洲
- GCC
- 土耳其
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Uber Technologies Inc.
- Beijing Xiaoju Technology Co. Ltd(DiDi)
- Lyft Inc.
- Grab Holdings Inc.
- Bolt Technology OU
- ANI Technologies Pvt Ltd(Ola)
- Gojek Tech
- FREE NOW(Intelligent Apps GmbH)
- BlaBlaCar
- Curb Mobility LLC
- Flywheel Software Inc.
- Kabbee Exchange Ltd
- Addison Lee Group
- Gett Inc.
- Yandex Go(Yandex NV)
- Careem Networks FZ-LLC
- Via Transportation Inc.
- Beat Mobility Services Ltd
- Easy Taxi(Tappsi SAS)
- Cabify Espana SL
第7章 市場機會與未來展望
According to Mordor Intelligence, the taxi market size was valued at USD 236.36 billion in 2025 and estimated to grow from USD 254.36 billion in 2026 to reach USD 366.91 billion by 2031, at a CAGR of 7.62% during the forecast period (2026-2031).
This report is Segmented by Booking Type (Online Booking and Offline Booking), Service Type (Ride-Hailing, Ride-Sharing, and Corporate & Institutional Contracts), Vehicle Type (Passenger Cars, Motorcycles & Scooters, Vans & MPVs, and Auto-Rickshaws & Tuk-Tuks), Propulsion Type (ICE, Electric, and Hybrid), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Taxi Market Trends and Insights
Rapid Smartphone & Internet Penetration
Smartphone penetration above four-fifths in leading urban centers lets platforms algorithmically match riders and drivers faster, shrinking average wait times from 15-20 minutes to under 5 minutes in top-tier cities. Ubiquitous 5G coverage allows richer location data, which boosts fleet utilisation and lowers deadhead mileage. Higher data speeds also mean in-app video ads and real-time driver coaching, unlocking diversified revenue streams. Mobile wallets embedded in ride-hailing apps now account for more than four-fifths of transactions in developed markets, lowering cash-handling risk and reducing airport queue times. In emerging economies, internet upgrades bypass legacy dispatch systems, enabling leap-frog adoption of digital bookings.
Urban Congestion & Declining Private-Car Ownership
Vehicle utilisation in dense cities often falls slightly, motivating residents to replace private cars with on-demand rides that eliminate parking fees. Municipal congestion charges plus rising fuel prices raise the total cost of car ownership, reinforcing the appeal of taxi services, especially pooled formats that can cut per-trip fares by up to 40%. Younger consumers aged 25-35 are most receptive, preferring bundled mobility-as-a-service subscriptions integrating taxis with rail, bus, and micro-mobility in one app. Congestion costs topping USD 100 billion annually in the U.S. place political pressure on cities to privilege high-occupancy modes, indirectly boosting taxi market demand.
Evolving Licensing & Regulatory Crack-Downs
City regulators are modernising medallion structures and tightening background-check rules, raising compliance costs for app-based and traditional operators. Seattle plans to phase out its medallion regime by March 2026, while New York City requires half of all cabs to be wheelchair-ready by March 2025. The Singaporean watchdog blocked Grab's planned acquisition of Trans-Cab over antitrust concerns, signalling closer scrutiny of platform consolidation. Divergent regional standards increase legal complexity and can delay market entries, suppressing near-term growth momentum.
Other drivers and restraints analyzed in the detailed report include:
- Ride-Hailing Platform Expansion In Emerging Economies
- AI-Based Dynamic Routing & Pricing Optimisation
- Intensifying Price Wars Eroding Driver Earnings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Online channels delivered 63.78% of the taxi market share in 2025, illustrating the structural pivot toward app-based demand aggregation. The dominance of digital bookings strengthened business intelligence loops that sharpen demand prediction, resulting in higher asset utilisation and lower passenger wait times. The offline segment remains relevant among older demographics and jurisdictions where medallion systems still confer street-hail privilege, yet its growth trajectory lags the broader taxi market. Operators are therefore integrating voice-based IVR and kiosk interfaces alongside apps to preserve legacy users while nudging them toward digital interactions.
Looking forward, online bookings are forecast to grow at an 7.92% CAGR. Super-apps bundling mobility with payments and e-commerce will underpin incremental trip volumes, especially in APAC megacities where smartphone penetration exceeds four-fifths. Online channels also furnish granular trip-level data that powers targeted loyalty and dynamic pricing, reinforcing share gains. Contractual corporate accounts, airport concessions, and mandated accessibility services sustain the offline channel's CAGR. Yet, its revenue mix is expected to shrink below one-third of the taxi market size by 2031.
Ride-hailing controlled 74.85% of taxi market size in 2025, owing to network effects that ensure quicker matches and transparent pricing. Market-leading platforms invest heavily in safety verification, real-time monitoring, and driver training that elevate service reliability above informal rivals. Pooled rides are projected to outpace overall taxi market expansion with an 7.78% CAGR because they ease congestion and lower per-seat fares by sharing costs among passengers. Environmental compliance agendas further catalyse pooled demand as corporates set fleet-wide carbon reduction targets.
Corporate mobility contracts, once dominated by black-car fleets, are increasingly awarded to app-based providers offering digital receipts and per-seat expense allocation. The embedded data facilitates carbon-reporting dashboards now demanded by ESG-focused boards. Although ride-hailing maintains gross-booking supremacy, pooled formats generate higher occupancy and superior asset productivity, especially during peak hours when single-occupancy trips face surge pricing.
Complete Report Scope:
- By Booking Type
- Online Booking
- Offline Booking
- By Service Type
- Ride-hailing
- Ride-sharing (pooled)
- Corporate & Institutional Contracts
- By Vehicle Type
- Passenger Cars
- Motorcycles & Scooters
- Vans & MPVs
- Auto-Rickshaws & Tuk-tuks
- By Propulsion Type
- Internal Combustion Engine (ICE)
- Electric
- Hybrid
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific contributed 37.42% taxi market share in 2025, sustained by rapid urbanisation, smartphone usage above four-fifth, and widespread two-wheeler taxis that thrive in dense corridors. Government policies offering EV subsidies and medallion exemptions accelerate fleet turnover throughout India, Vietnam, and Thailand. Japan's taxi incumbents partner with Uber to integrate 20,000 vehicles on the platform, reinforcing cross-border digital standardisation.
The Middle East and Africa is projected to register an 7.88% CAGR through 2031, due to national digital-economy programmes and mega-city infrastructure. Dubai Taxi Company aims to migrate around four-fifth of rides to e-booking by 2029 while electrifying one-quarter of its fleet, aligning with the UAE Net-Zero 2050 roadmap. Ride-hailing apps proliferate in Egypt, Saudi Arabia, and Nigeria where youthful, tech-savvy populations leapfrog legacy dispatch models. Pan-regional super-apps such as Careem integrate payments, delivery, and transport under one umbrella, enhancing user retention. Authorities impose stricter accessibility and data-privacy mandates, requiring material compliance outlays that favor scaled operators. Lyft's acquisition of FREENOW in April 2025 doubled its European reach to 11 countries and opened access to nearly 300 billion annual personal vehicle trips. Meanwhile, city councils across Germany are testing zero-emission zones that could bump EV adoption thresholds earlier than corporate plans anticipate. Net effect: growth slows but remains positive as platforms diversify into deliveries and subscription mobility passes.
- Uber Technologies Inc.
- Beijing Xiaoju Technology Co. Ltd (DiDi)
- Lyft Inc.
- Grab Holdings Inc.
- Bolt Technology OU
- ANI Technologies Pvt Ltd (Ola)
- Gojek Tech
- FREE NOW (Intelligent Apps GmbH)
- BlaBlaCar
- Curb Mobility LLC
- Flywheel Software Inc.
- Kabbee Exchange Ltd
- Addison Lee Group
- Gett Inc.
- Yandex Go (Yandex NV)
- Careem Networks FZ-LLC
- Via Transportation Inc.
- Beat Mobility Services Ltd
- Easy Taxi (Tappsi SAS)
- Cabify Espana SL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Smartphone & Internet Penetration
- 4.2.2 Urban Congestion & Declining Private-Car Ownership
- 4.2.3 Ride-Hailing Platform Expansion In Emerging Economies
- 4.2.4 AI-Based Dynamic Routing & Pricing Optimisation
- 4.2.5 Accessibility Mandates Driving Fleet Renewal
- 4.2.6 Super-App Api Integrations Boosting Embedded Demand
- 4.3 Market Restraints
- 4.3.1 Evolving Licensing & Regulatory Crack-Downs
- 4.3.2 Intensifying Price Wars Eroding Driver Earnings
- 4.3.3 Limited Public Ev-Charging Slowing E-Taxi Uptake
- 4.3.4 Data-Privacy Litigation Around Trip-Tracking
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Booking Type
- 5.1.1 Online Booking
- 5.1.2 Offline Booking
- 5.2 By Service Type
- 5.2.1 Ride-hailing
- 5.2.2 Ride-sharing (pooled)
- 5.2.3 Corporate & Institutional Contracts
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Motorcycles & Scooters
- 5.3.3 Vans & MPVs
- 5.3.4 Auto-Rickshaws & Tuk-tuks
- 5.4 By Propulsion Type
- 5.4.1 Internal Combustion Engine (ICE)
- 5.4.2 Electric
- 5.4.3 Hybrid
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 Turkey
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Uber Technologies Inc.
- 6.4.2 Beijing Xiaoju Technology Co. Ltd (DiDi)
- 6.4.3 Lyft Inc.
- 6.4.4 Grab Holdings Inc.
- 6.4.5 Bolt Technology OU
- 6.4.6 ANI Technologies Pvt Ltd (Ola)
- 6.4.7 Gojek Tech
- 6.4.8 FREE NOW (Intelligent Apps GmbH)
- 6.4.9 BlaBlaCar
- 6.4.10 Curb Mobility LLC
- 6.4.11 Flywheel Software Inc.
- 6.4.12 Kabbee Exchange Ltd
- 6.4.13 Addison Lee Group
- 6.4.14 Gett Inc.
- 6.4.15 Yandex Go (Yandex NV)
- 6.4.16 Careem Networks FZ-LLC
- 6.4.17 Via Transportation Inc.
- 6.4.18 Beat Mobility Services Ltd
- 6.4.19 Easy Taxi (Tappsi SAS)
- 6.4.20 Cabify Espana SL
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 全球計程車和豪華轎車服務市場
 東協計程車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031)電動計程車:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 計程車市場規模、市場佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。
 計程車服務市場:全球市場預測,2026-2032年摩托計程車服務市場-2026-2032年全球市場預測摩托車計程車服務市場-2026-2032年全球市場預測新能源汽車計程車市場:2026-2032年全球市場預測(按車輛類型、車身尺寸、驅動技術、續航里程、服務類型和最終用戶分類)
 2026年全球計程車服務市場報告豪華轎車服務市場:2026-2032年全球市場預測(依服務類型、時間長度、車輛燃料類型、車輛類型、最終用戶和預訂方式分類)