


 |
市場調查報告書
商品編碼
2122571
纖維增強複合材料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Fiber Reinforced Composites - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
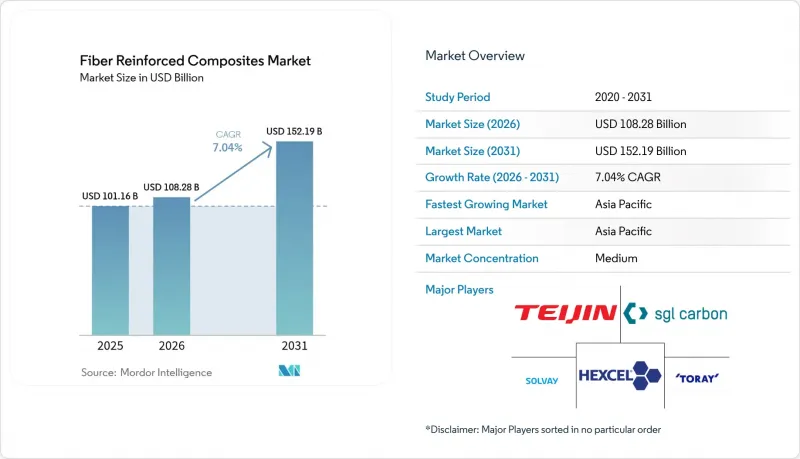
據 Mordor Intelligence 稱,2025 年纖維增強複合材料市值為 1011.6 億美元,預計到 2031 年將達到 1521.9 億美元,而 2026 年為 1082.8 億美元,預測期(2026-2031 年)複合成長率為 7.04%。
本報告按纖維類型(碳纖維、玻璃纖維等)、基體(高分子複合材料、金屬複合材料等)、製造流程(捲繞法、纏繞成型等)、終端用戶產業(航太與國防、汽車等)以及地區(亞太地區、北美地區等)對產業進行細分。市場預測以美元計價。
全球纖維增強複合材料市場趨勢及洞察
航太領域對複合材料的需求不斷成長
商業項目的目標是將複合材料的使用率提高到50%,以降低15-20%的燃油消耗,而電動垂直起降(eVTOL)飛機的設計中,這一比例還在進一步提高。受寬體飛機產量增加的推動,Hexel公司商用航太部門2024年的銷售額成長了21.3%,但供應鏈緊張限制了短期交付。 NASA的HiCAM計畫旨在大幅提高熱固性和熱塑性樹脂機身的生產率,這表明結構件需求正在成長。同時,針對液氫推進系統全複合材料低溫儲槽的研發正在纖維增強複合材料市場開闢一個新的細分領域。這些變化共同鞏固了航太領域作為中期成長驅動力的地位。
增加風力發電機葉片的長度
如今,葉片長度已超過100米,因此需要使用碳纖維槳葉帽來保持剛性而不增加重量。美國的「大型自適應轉子」計畫凸顯了這一趨勢,而天然纖維和合成纖維的混合使用正在提升整個生命週期的永續性。陶氏化學的新型聚氨酯-碳纖維拉擠成型生產線實現了90%的線上固化率,提高了超大尺寸層壓板的生產效率。預計到2030年,全球產能將達到981吉瓦,但廢棄葉片的回收仍是一個尚未解決的難題,這需要循環經濟領域的創新。
原料和加工成本高昂
高能耗的碳化製程會導致更高的投入成本,但曼徹斯特大學開發的木質素基前體有望將成本降低3到5倍。傳統的AFP系統造價在300萬美元到600萬美元之間,但模組化租賃模式降低了准入門檻。 SGL Carbon纖維部門銷售額下降35.2%,顯示對大宗商品價格波動十分敏感。再生碳纖維的生產能耗遠低於新碳纖維,並且可以在保持機械性能的同時,在一定程度上緩解這些壓力。
細分市場分析
到2025年,玻璃纖維將以61.22%的市場佔有率佔據主導地位,這主要得益於其成本效益以及在建築、汽車和風電行業強大的供應鏈。儘管碳纖維的市場佔有率較小,但預計到2031年,其複合年成長率將達到7.86%,這主要受航太和高性能汽車行業需求成長的推動。醯胺纖維以其抗衝擊性和熱穩定性而聞名,主要用於防護設備和航太零件。硼纖維雖然成本較高,但也被用於一些特殊的航太應用。天然纖維的應用正在不斷增加,這主要得益於將合成纖維和天然纖維結合在一起的混合複合材料,在保持性能的同時,也具有環境效益。例如,竹纖維和劍麻纖維就被用於風力發電機機葉片。
製造技術的進步正在改變纖維生產的經濟格局。 「CARBOWAVE」計畫引進了基於微波的碳纖維製造技術,該技術有望透過降低高達70%的能耗,改變成本結構並減少對環境的影響。沙烏地阿拉伯正在建造全球首個工業規模的富石墨烯碳纖維生產設施,其應用領域涵蓋航太、汽車和建築等產業,預計到2030年將創造超過16億美元的收入。玄武岩纖維因其優於天然纖維複合材料的機械性能和環境耐受性,正逐漸成為一種永續的替代材料。此外,與碳纖維相比,玄武岩纖維的成本優勢使其適用於需要在惡劣環境下保持耐久性的離岸風力發電應用。
預計到2025年,聚合物基材料將佔銷售額的69.78%,而金屬基質材料預計將實現7.31%的複合年成長率,凸顯了纖維增強複合材料市場持續成長的重要性,尤其是在航太領域的溫度控管應用方面。通用電氣(GE)的陶瓷基質複合材料可提高噴射引擎的動作溫度,並將燃油效率提高高達20%。此外,碳-碳材料對於暴露於高超音速再入大氣層和核融合反應器的零件至關重要,這些零件需要在2000 度C的高溫下保持耐久性。
聚碳酸酯、PEKK 和 PEEK 等高速循環熱塑性塑膠因其可回收性和一分鐘內即可完成壓製成型的特性而備受關注。科思創宣布推出家用電子電器產業的連續纖維聚碳酸酯面板。此外,美國國家再生能源實驗室 (NREL) 成功展示了一種生物基環氧樹脂,與石油化學樹脂相比,該樹脂在保持生產成本效益的同時,可減少 40% 的溫室氣體排放。三菱化學也開發出一種可承受 1500 度C高溫的陶瓷複合材料,滿足日本宇宙航空研究開發機構 (JAXA) 的火箭發射規格要求,並為國防和航太領域創造了新的商機。
區域分析
預計到2025年,亞太地區將佔全球銷售額的40.46%,複合年成長率達8.16%,並有望繼續維持纖維增強複合材料市場中心的地位。中國HRC公司已在常熟投資3,380萬美元,以擴大其熱固性和熱塑性零件的量產能力。同時,印度Kineco Exel公司正透過位於高爾的工廠向維斯塔斯公司供應拉擠成型碳纖維板。台灣上汽集團正透過實現海上專案樹脂板的在地採購,深化其區域價值鏈。
在北美,強勁的航太工業基礎和燃油效率法規支撐著市場需求。 GKN Aerospace公司將其位於墨西哥奇瓦瓦州的組裝能加倍,創造了200個就業崗位,以支持灣流和本田噴射機計畫。賽峰集團擴大了位於克雷塔羅州的LEAP引擎產能,凸顯了墨西哥作為複合材料製造地的崛起。麻省理工學院的研究人員開發了一種利用奈米碳管的「奈米縫合」技術,將層間剪切強度提高了62%,並表明有可能進一步減輕重量。在歐洲,強制性回收和低碳材料創新正在蓬勃發展。 「清潔天空2框架」專案展示了使用氙氣閃光燈的AFP加熱技術在PEEK和PEKK機翼蒙皮上的有效性。同時,Strata和索爾維在阿拉伯聯合大公國艾因開設了中東和北非地區(MENA)的首家預浸料工廠,為波音777X生產零件。預計到 2024 年,巴西複合材料銷售額將成長 5.6%,達到 5.6 億美元,顯示整個南美洲都有成長潛力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究的先決條件
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 航太領域對複合材料的需求不斷成長
- 增加風力發電機葉片的長度
- 減輕汽車重量的要求
- 利用FRP加固進行基礎設施修復
- 用於快速層壓的熱塑性單向帶生產線
- 從碳回收中獲得的丙烯腈原料
- 市場限制因素
- 原料成本和加工成本上漲
- 回收利用面臨的挑戰
- 吸水和耐火性能差導致的性能缺陷
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依纖維類型
- 碳纖維
- 玻璃纖維
- 醯胺纖維
- 硼纖維
- 其他纖維種類(玄武岩纖維、天然纖維等)
- 矩陣
- 高分子複合材料
- 金屬複合材料
- 陶瓷複合材料
- 碳及碳複合材料
- 混合複合材料
- 透過製造程序
- 積層法(手工/噴塗)
- 纏繞成型
- 冥王星
- 樹脂轉注成形
- 自動化纖維鋪放和膠帶層壓
- 壓縮成型和射出成型
- 3D列印/積層製造
- 按最終用戶行業分類
- 航太/國防
- 車
- 風力
- 建築/施工
- 電氣和電子設備
- 體育用品
- 其他終端用戶產業(海運、石油和天然氣等)
- 按地區
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 中東和非洲
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Avient Corporation
- Covestro AG
- Hexcel Corporation
- Huntsman Corporation
- Mitsubishi Chemical Corporation
- Owens Corning
- Plasan
- SABIC
- SGL Carbon
- Solvay
- Teijin Limited
- Toray Industries Inc.
- TPI Composites
第7章 市場機會與未來展望
According to Mordor Intelligence, the fiber reinforced composites market size was valued at USD 101.16 billion in 2025 and estimated to grow from USD 108.28 billion in 2026 to reach USD 152.19 billion by 2031, at a CAGR of 7.04% during the forecast period (2026-2031).
This report Segments the Industry by Fiber Type (Carbon Fibers, Glass Fibers and More), Matrix (Polymer Matrix Composites, Metal Matrix Composites, and More), Manufacturing Process (Pultrusion, Filament Winding, and More), End-User Industry (Aerospace and Defense, Automotive, and More) and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Fiber Reinforced Composites Market Trends and Insights
Growing Aerospace Composite Demand
Commercial programmes target 50% composite content to secure 15-20% fuel-burn reductions, and eVTOL designs push that ratio even higher. Hexcel's commercial aerospace revenue jumped 21.3% in 2024 on wide-body build rates, yet supply chain tightness tempers near-term deliveries. NASA's HiCAM effort aims to multiply output rates for thermoset and thermoplastic fuselages, signaling a structural demand uplift. Parallel R&D on fully composite cryogenic tanks for liquid-hydrogen propulsion opens new sub-segments for the fiber reinforced composites market. Together, these shifts cement aerospace as a medium-term growth catalyst.
Wind-Turbine Blade Length Upsizing
Blade lengths now exceed 100 meters, demanding carbon spar caps to retain stiffness without weight penalties. The U.S. Big Adaptive Rotor project underscores this trajectory, while hybrid natural-synthetic fibre blends improve lifecycle sustainability. New polyurethane-carbon pultrusion lines from Dow achieve 90% in-line cure, boosting throughput for oversized laminates. Global capacity is forecast to reach 981 GW by 2030, yet recycling end-of-life blades remains unresolved, inviting circular-economy innovation.
High Raw-Material & Processing Costs
Energy-intensive carbonisation drives elevated input costs, although lignin-based precursors from the University of Manchester suggest 3-5 X savings potential. Traditional AFP systems list at USD 3-6 million, but modular leasing models lower the entry barrier. SGL Carbon's 35.2% sales drop in fiber units shows sensitivity to volatile commodity pricing. Recycled carbon fibre, requiring far less energy, can relieve some pressure while preserving mechanical properties.
Other drivers and restraints analyzed in the detailed report include:
- Automotive Lightweighting Mandates
- Infrastructure Rehab with FRP Rebar
- Difficulties in Recycling
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, glass fibers dominated the market with a 61.22% share, driven by cost efficiencies and robust supply chains in the construction, automotive, and wind energy sectors. While holding a smaller share, carbon fibers are projected to grow at a CAGR of 7.86% through 2031, supported by increasing demand in the aerospace and high-performance automotive industries. Aramid fibers, known for their impact resistance and thermal stability, are primarily used in protective equipment and aerospace components. Despite their higher costs, Boron fibers are utilized in specialized aerospace applications. The adoption of natural fibers is increasing through hybrid composites that combine synthetic and natural fibers, offering environmental benefits while maintaining performance. For example, bamboo and sisal fibers are used in wind turbine blades.
Advancements in manufacturing are transforming fiber production economics. The CARBOWAVE project has introduced microwave-assisted carbon fiber production, reducing energy consumption by up to 70%, potentially altering cost structures and environmental impacts. Saudi Arabia has established the first industrial-scale facility for graphene-enriched carbon fiber production, targeting aerospace, automotive, and construction applications, with projected revenues exceeding USD 1.6 billion by 2030. Basalt fibers are emerging as a sustainable alternative, offering superior mechanical properties and environmental resistance compared to natural fiber composites. Additionally, their cost advantages over carbon fibers make them suitable for offshore wind applications requiring durability in harsh environments.
In 2025, polymer systems accounted for 69.78% of the revenue, while metal matrix options are projected to achieve a 7.31% CAGR, highlighting their sustained importance in the fiber-reinforced composites market, particularly for aerospace thermal-management applications. Ceramic matrix composites developed by GE enhance jet engine operating temperatures, improving fuel efficiency by up to 20%. Additionally, carbon-carbon materials are critical for components exposed to hypersonic re-entry and fusion reactors, where endurance at 2,000 °C is essential.
Rapid-cycle thermoplastics, such as polycarbonate, PEKK, and PEEK, are gaining traction due to their recyclability and capability for one-minute press molding. Covestro has introduced continuous-fiber polycarbonate panels targeting the consumer electronics sector. Furthermore, NREL has demonstrated a bio-based epoxy that reduces greenhouse gas emissions by 40% compared to petrochemical-based resins while maintaining production cost efficiency. Mitsubishi Chemical has also developed a ceramic composite capable of withstanding temperatures of 1,500 °C, meeting JAXA specifications for launch vehicles and creating new revenue opportunities in the defense and space sectors.
Complete Report Scope:
- By Fiber Type
- Carbon Fibers
- Glass Fibers
- Aramid Fibers
- Boron Fibers
- Other Fiber Types (Basalt Fibers, Natural Fibers, etc.)
- By Matrix
- Polymer Matrix Composites
- Metal Matrix Composites
- Ceramic Composites
- Carbon-Carbon Composites
- Hybrid Composites
- By Manufacturing Process
- Lay-Up (Hand/Spray)
- Filament Winding
- Pultrusion
- Resin Transfer Molding
- Automated Fiber Placement & Tape Laying
- Compression & Injection Molding
- 3D Printing / Additive Manufacturing
- By End-user Industry
- Aerospace & Defense
- Automotive
- Wind Energy
- Building & Construction
- Electrical & Electronics
- Sporting Goods
- Other End-user Industries (Marine, Oil and Gas, etc.)
- By Geography (Value)
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- South Africa
- Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 40.46% of 2025 sales and is set to post an 8.16% CAGR, ensuring that the fiber reinforced composites market remains anchored in the region. China's HRC invested USD 33.8 million in Changshu to expand serial thermoset and thermoplastic part output, while India's Kineco Exel now supplies pultruded carbon planks to Vestas from its Goa site. Taiwan's Swancor has localised resin plate supply for offshore projects, deepening the regional value chain.
North America leverages an entrenched aerospace base and fuel-economy regulation to maintain demand. GKN Aerospace doubled assembly capacity in Chihuahua, Mexico, adding 200 jobs to serve Gulfstream and HondaJet programmes. Safran expanded LEAP engine capacity in Queretaro, underscoring Mexico's rise as a composites manufacturing node. MIT researchers developed "nanostitching" with carbon nanotubes, lifting interlaminar shear by 62% and hinting at further light-weighting gains. Europe champions recycling mandates and low-carbon material innovation. The Clean Sky 2 FRAMES project validated xenon flashlamp AFP heating for PEEK and PEKK wingskins, while Strata and Solvay opened the first MENA prepreg plant for Boeing 777X parts in Al Ain, UAE. Brazil's composites turnover rose 5.6% to USD 560 million in 2024, pointing to latent growth potential across South America.
- Avient Corporation
- Covestro AG
- Hexcel Corporation
- Huntsman Corporation
- Mitsubishi Chemical Corporation
- Owens Corning
- Plasan
- SABIC
- SGL Carbon
- Solvay
- Teijin Limited
- Toray Industries Inc.
- TPI Composites
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing aerospace composite demand
- 4.2.2 Wind-turbine blade length upsizing
- 4.2.3 Automotive lightweighting mandates
- 4.2.4 Infrastructure rehab with FRP rebar
- 4.2.5 Rapid-layup thermoplastic UD tape lines
- 4.2.6 Carbon-capture derived acrylonitrile feedstock
- 4.3 Market Restraints
- 4.3.1 High raw-material & processing costs
- 4.3.2 Difficulties in Recycling
- 4.3.3 Performance defects due to wate absorption and low fire resistance
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Fiber Type
- 5.1.1 Carbon Fibers
- 5.1.2 Glass Fibers
- 5.1.3 Aramid Fibers
- 5.1.4 Boron Fibers
- 5.1.5 Other Fiber Types (Basalt Fibers, Natural Fibers, etc.)
- 5.2 By Matrix
- 5.2.1 Polymer Matrix Composites
- 5.2.2 Metal Matrix Composites
- 5.2.3 Ceramic Composites
- 5.2.4 Carbon-Carbon Composites
- 5.2.5 Hybrid Composites
- 5.3 By Manufacturing Process
- 5.3.1 Lay-Up (Hand/Spray)
- 5.3.2 Filament Winding
- 5.3.3 Pultrusion
- 5.3.4 Resin Transfer Molding
- 5.3.5 Automated Fiber Placement & Tape Laying
- 5.3.6 Compression & Injection Molding
- 5.3.7 3D Printing / Additive Manufacturing
- 5.4 By End-user Industry
- 5.4.1 Aerospace & Defense
- 5.4.2 Automotive
- 5.4.3 Wind Energy
- 5.4.4 Building & Construction
- 5.4.5 Electrical & Electronics
- 5.4.6 Sporting Goods
- 5.4.7 Other End-user Industries (Marine, Oil and Gas, etc.)
- 5.5 By Geography (Value)
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Avient Corporation
- 6.4.2 Covestro AG
- 6.4.3 Hexcel Corporation
- 6.4.4 Huntsman Corporation
- 6.4.5 Mitsubishi Chemical Corporation
- 6.4.6 Owens Corning
- 6.4.7 Plasan
- 6.4.8 SABIC
- 6.4.9 SGL Carbon
- 6.4.10 Solvay
- 6.4.11 Teijin Limited
- 6.4.12 Toray Industries Inc.
- 6.4.13 TPI Composites
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment
- 7.2 Growing Innovation on Bio-based Resin Systems

 碳纖維增強熱塑性複合材料(CFRTP):市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)天然纖維增強複合材料:市場佔有率分析、產業趨勢與統計、成長預測(2025-2031)
 纖維增強複合材料市場:依纖維類型、樹脂類型、製造流程、增強材料形式和應用分類-2026-2032年全球市場預測
 複合纖維市場規模、佔有率和成長分析:按結構、材料、應用、最終用途和地區分類-2026-2033年產業預測
 天然纖維增強複合材料市場:依纖維類型、基體類型、技術、應用、國家及地區分類-產業分析、市場規模、市佔率及2026年至2033年預測
 連續纖維複合材料市場:按樹脂類型、產品類型、增強材料類型、產業和地區分類(2026-2034 年)
 天然纖維增強複合材料市場:依纖維類型、聚合物、終端用戶產業(航太)及地區分類雙組分纖維:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 碳纖維熱塑性複合材料市場規模、佔有率和趨勢分析報告:按原料、應用、地區和細分市場分類(2026-2033 年)CFRTP市場:2026-2032年全球市場預測(按樹脂類型、產品類型、纖維類型、製造流程、應用和最終用戶分類)