


 |
市場調查報告書
商品編碼
2122524
小型基地台網路:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Small Cell Networks - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
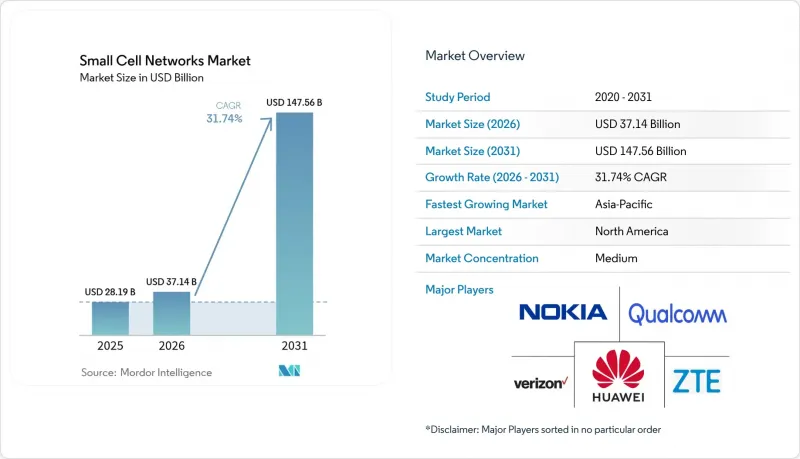
根據 Mordor Intelligence 估計,到 2026 年,小型基地台網路市場價值將達到 371.4 億美元,高於 2025 年的 281.9 億美元,預計到 2031 年將達到 1,475.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 31.74%。
本報告按小區類型(毫微微基地台、微微微微型基地台、微型蜂窩、區域基地台、無線點陣系統)、運行環境(室內和室外)、最終用戶行業(銀行、金融服務和保險、IT和電信、醫療保健、零售、電力和能源、智慧城市和政府)以及地區進行分類。
全球小型基地台網路市場趨勢與洞察
5G頻段競標將加速網路密度的提升。
中頻段分配正在為 5G 創造必要的頻寬。獨立經濟模型表明,每增加 100 MHz頻寬,就能使 GDP 成長 2,640 億美元。即將進行的 AWS-3 銷售將進一步增強此效應。美國的快速核准程序已將核准週期從數年縮短至數月,使營運商能夠將網路規模從宏基站擴展到每個城市數千個街邊節點。由於毫米波訊號衰減迅速,實現連續訂單所需的小型基地台數量可能是傳統大型基地台的 10 倍,這推動了對小型無線電設備和整合天線的需求。
行動數據的爆炸性成長正在推動其廣泛應用。
根據愛立信預測,年流量將成長20%,到2029年,5G預計將佔資料流量的75%。影片串流、XR內容和雲端遊戲正在催生熱點需求模式,給扇區大型基地台帶來壓力。定向小型基地台叢集無需全面覆蓋即可提供在局部容量,使營運商能夠在保持良好用戶體驗的同時降低資本支出。過去十年,此類部署已成長四倍,產業組織預測未來十年將成長八倍。
監管障礙阻礙了實施速度。
即使聯邦層級已經簡化了監管,地方政府的法規仍然高度不一致。歷史街區通常需要進行設計審查,核准可能需要12到24個月,這導致建設預算膨脹。目前,美國約有20個州制定了關於小型基地台的法規,但不同的解讀使得跨州建設變得複雜。電信公司正試圖透過標準化桿頂機櫃和採用街道設備租賃的方式來縮短引進週期,但摩擦仍然阻礙戶外部署。
細分市場分析
由於成本低廉,毫微微基地台)在家庭和小規模辦公室中的應用前景廣闊,預計到2025年,其銷售額將佔總銷售額的36.40%。毫微微蜂窩可在約60英尺(約18公尺)的範圍內為最多6個使用者提供服務,使其成為改善偏遠室內場所連接性的標準選擇。另一方面,微蜂窩(Microcell)預計將以33.75%的複合年成長率(CAGR)實現最快成長,其優勢在於能夠在1000英尺(約305公尺)的範圍內為200個用戶提供服務。這使其成為繁忙的商業街和交通樞紐的理想選擇。隨著營運商將這些節點與邊緣運算相結合,以支援對延遲敏感的應用場景,微蜂窩層的小型基地台網路市場規模預計將迅速擴大。此外,無線設計正日益與開放式無線存取網(Open RAN)標準相融合,從而建構一個多廠商生態系統,減少廠商鎖定並加速創新。
中型設施中覆蓋 750 英尺的微微型基地台的兼容性升級正在促成新的企業契約,而區域基地台正在主幹道沿線部署,以方便行人層面的網路切換。室內 RadioDot 架構已被超過 120 家營運商採用,以最少的現場設備即可實現大型基地台等級的通訊速度。這些趨勢共同凸顯了小型基地台網路市場正從單一設備解決方案轉向多層生態系統的轉變。
區域分析
由於早期C頻段頻率競標和聯邦監管改革,北美預計到2025年將佔全球收入的34.20%。光是在美國,截至2022年就已安裝了超過45.2萬個戶外節點,並透過「美國農村5G基金」累計90億美元,將網路擴展到城市中心以外的地區。一項開創性的140億美元現代化項目正在用開放式架構的無線設備取代傳統的基頻設備,顯示電信業者致力於供應商多元化。
亞太地區預計將實現36.95%的複合年成長率,成為所有地區中成長速度最快的地區。中國已部署超過50萬個5G基地台,印度的「數位通訊政策」正在全國放寬土地徵用限制。預計2023年,該地區的行動生態系統將為GDP貢獻8,800億美元,凸顯其經濟重要性。 KT針對智慧辦公環境推出的「Radio Dot」等室內小型基地台部署案例,充分展現了企業級室內覆蓋的商業價值。
在歐洲,永續性,各方正積極尋求能夠將基地台能耗降低高達45%的解決方案。各國的發展藍圖(例如德國的5G戰略)優先發展高密度小型基地台網路,以支援自動駕駛和工業4.0。該地區的電信業者正在路燈上永久安裝小型無線設備。在倫敦的一個先導計畫中,威斯敏斯特區增設了80個基地台,對周邊環境的影響微乎其微。
在中東和非洲的部分地區,5G 部署正在擴大,用於朝聖地和智慧城市走廊,例如沙烏地阿拉伯的多供應商計劃,該計劃結合了大型基地台和小型基地台台。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 5G頻段競標和強制性網路密度增加
- 行動數據和影片流量的爆炸性成長
- 企業對專用 5G/LTE-A 網路的需求
- 監管機構主導的頻率共用和CBRS的推廣
- 對中立主機和基礎設施共用的投資熱潮
- 透過人工智慧驅動的自最佳化網路降低營運成本
- 市場限制因素
- 地方政府複雜的土地徵用和授權程序
- 回程傳輸光纖/電源缺口
- 遵守能源效率法規的成本不斷上升
- 射頻前端晶片組的出口限制與供應風險
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資和資金籌措分析
第5章 市場規模與成長預測
- 細胞類型
- 毫微微基地台
- 微微型基地台
- 微細胞
- Metrocell
- Radio Dot Systems
- 透過商業環境
- 室內的
- 戶外的
- 按最終用戶行業分類
- BFSI
- 資訊科技/通訊
- 衛生保健
- 零售
- 電力和能源
- 智慧城市與政府
- 按地區
- 北美洲
- 南美洲
- 歐洲
- 亞太地區
- 中東和非洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Huawei Technologies Co. Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- ZTE Corporation
- Samsung Electronics Co. Ltd.
- Cisco Systems Inc.
- CommScope Inc.(incl. Airvana)
- American Tower Corporation
- Qualcomm Technologies Inc.
- ATandT Inc.
- Verizon Communications Inc.
- Crown Castle International Corp.
- Airspan Networks Holdings Inc.
- Qucell Inc.
- Cirrus Core Networks
- Casa Systems Inc.
- Sercomm Corporation
- Baicells Technologies
- Comba Telecom Systems Holdings Ltd.
- IP.Access Ltd.
- Boingo Wireless Inc.
- Parallel Wireless Inc.
- JMA Wireless
- Corning Inc.(SpiderCloud)
第7章 市場機會與未來展望
According to Mordor Intelligence, small cell networks market size in 2026 is estimated at USD 37.14 billion, growing from 2025 value of USD 28.19 billion with 2031 projections showing USD 147.56 billion, growing at 31.74% CAGR over 2026-2031.
This report is Segmented by Cell Type (Femtocell, Picocell, Microcell, Metrocell, and Radio Dot Systems), Operating Environment (Indoor and Outdoor), End-User Vertical (BFSI, IT and Telecom, Healthcare, Retail, Power and Energy, and Smart City and Government), and Geography.
Global Small Cell Networks Market Trends and Insights
5G spectrum auctions accelerate network densification
Mid-band allocations are unlocking the spectral headroom needed for 5G. Independent economic modelling shows that every extra 100 MHz could add USD 264 billion to GDP. The forthcoming AWS-3 sale will reinforce this effect. Faster permitting has trimmed U.S. approval cycles from several years to months, enabling operators to scale from macro sites to thousands of street-level nodes per city. Because millimeter-wave signals decay sharply, achieving contiguous coverage can demand up to 10 times more small cells than legacy macrocells, driving orders for compact radios and integrated antennas.
Mobile-data explosion drives adoption
Annual traffic is rising 20%, and 5G will carry 75% of bits by 2029, according to Ericsson. Streaming UHD video, XR content, and cloud gaming create hotspot demand profiles that strain sectorized macros. Targeted clusters of small cells deliver localized capacity without full-scale overlays, enabling operators to throttle capex while preserving user experience. Deployments have already quadrupled over the past decade; industry associations expect an eight-fold increase in the next ten years.
Regulatory hurdles impede deployment velocity
Even after federal streamlining, local rules vary widely. Historic districts often impose design reviews, stretching approvals to 12-24 months and inflating construction budgets. Roughly 20 U.S. states now have small-cell statutes, yet inconsistent interpretation complicates multi-state builds. Operators are standardizing pole-top enclosures and leveraging street furniture leases to shorten cycles, but friction remains a brake on outdoor rollout.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise private networks create new growth vectors
- Neutral-host models transform deployment economics
- Semiconductor supply constraints threaten scaling
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Femtocells captured 36.40% of 2025 revenue, reflecting their affordability for homes and small offices. They handle up to six users within roughly 60 feet, making them the go-to for spot indoor remediation. Yet microcells are slated to grow fastest at 33.75% CAGR, benefiting from an ability to serve 200 users across 1,000 feet-ideal for dense shopping streets and transit stations. The small cell networks market size for the microcell tier is expected to expand swiftly as carriers combine these nodes with edge compute to support latency-sensitive use cases. Radio designs are also converging with Open RAN standards, enabling multi-vendor ecosystems that reduce lock-in and accelerate innovation.
Compatibility upgrades in picocells-covering 750 feet for mid-sized venues-are unlocking new enterprise contracts, while metrocells are rolling out along arterial roads to smooth hand-offs at pedestrian level. Indoor radio-dot architectures have passed 120 operators and deliver macro-parity speeds with minimal on-site equipment. Collectively, these trends underscore how the small cell networks market is becoming a multi-layered ecosystem rather than a single-device proposition.
Complete Report Scope:
- By Cell Type
- Femtocell
- Picocell
- Microcell
- Metrocell
- Radio Dot Systems
- By Operating Environment
- Indoor
- Outdoor
- By End-user Vertical
- BFSI
- IT and Telecom
- Healthcare
- Retail
- Power and Energy
- Smart City and Government
- By Geography
- North America
- South America
- Europe
- Asia-Pacific
- Middle East and Africa
Geography Analysis
North America held 34.20% revenue in 2025, anchored by early C-band auctions and federal siting reforms. The United States alone counted more than 452,000 outdoor nodes by 2022 and is budgeted to invest USD 9 billion via the 5G Fund for Rural America to expand beyond metro cores. A landmark USD 14 billion modernization project is replacing legacy basebands with open-architecture radios, illustrating carrier commitment to vendor diversity.
Asia Pacific is projected to deliver a 36.95% CAGR, the steepest regional trajectory. China has deployed more than 500,000 5G base stations, and India's Digital Communications Policy is easing right-of-way barriers nationwide. The regional mobile ecosystem added USD 880 billion to GDP in 2023, underscoring economic stakes. Flagship indoor small-cell implementations-such as KT's Radio Dot roll-out for smart offices-demonstrate the business case for enterprise-grade indoor coverage.
Europe emphasizes sustainability, pursuing solutions that cut site energy by up to 45%. National roadmaps-Germany's 5G Strategy being an example-prioritize tight-grid small cells to support automated driving and Industry 4.0. Operators in the region routinely embed compact radios on streetlamps; one London pilot added 80 cells across Westminster with minimal visual impact.
The Middle East and parts of Africa are scaling 5G for pilgrimage sites and smart-city corridors, as seen in Saudi Arabia's multi-vendor program that combines macro and small-cell layers.
List of Companies Covered in this Report:
- Huawei Technologies Co. Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- ZTE Corporation
- Samsung Electronics Co. Ltd.
- Cisco Systems Inc.
- CommScope Inc. (incl. Airvana)
- American Tower Corporation
- Qualcomm Technologies Inc.
- ATandT Inc.
- Verizon Communications Inc.
- Crown Castle International Corp.
- Airspan Networks Holdings Inc.
- Qucell Inc.
- Cirrus Core Networks
- Casa Systems Inc.
- Sercomm Corporation
- Baicells Technologies
- Comba Telecom Systems Holdings Ltd.
- IP.Access Ltd.
- Boingo Wireless Inc.
- Parallel Wireless Inc.
- JMA Wireless
- Corning Inc. (SpiderCloud)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G spectrum auctions and network densification mandates
- 4.2.2 Explosive mobile-data and video traffic growth
- 4.2.3 Enterprise demand for private 5G / LTE-A networks
- 4.2.4 Regulator-led spectrum-sharing and CBRS uptake
- 4.2.5 Neutral-host and shared-infrastructure investment wave
- 4.2.6 AI-driven self-optimising networks lowering OPEX
- 4.3 Market Restraints
- 4.3.1 Complex site-acquisition and municipal permitting
- 4.3.2 Backhaul fibre / power availability gaps
- 4.3.3 Rising energy-efficiency compliance costs
- 4.3.4 RF front-end chipset export controls and supply risk
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Investment and Funding Trends Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cell Type
- 5.1.1 Femtocell
- 5.1.2 Picocell
- 5.1.3 Microcell
- 5.1.4 Metrocell
- 5.1.5 Radio Dot Systems
- 5.2 By Operating Environment
- 5.2.1 Indoor
- 5.2.2 Outdoor
- 5.3 By End-user Vertical
- 5.3.1 BFSI
- 5.3.2 IT and Telecom
- 5.3.3 Healthcare
- 5.3.4 Retail
- 5.3.5 Power and Energy
- 5.3.6 Smart City and Government
- 5.4 By Geography
- 5.4.1 North America
- 5.4.2 South America
- 5.4.3 Europe
- 5.4.4 Asia-Pacific
- 5.4.5 Middle East and Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Huawei Technologies Co. Ltd.
- 6.4.2 Telefonaktiebolaget LM Ericsson
- 6.4.3 Nokia Corporation
- 6.4.4 ZTE Corporation
- 6.4.5 Samsung Electronics Co. Ltd.
- 6.4.6 Cisco Systems Inc.
- 6.4.7 CommScope Inc. (incl. Airvana)
- 6.4.8 American Tower Corporation
- 6.4.9 Qualcomm Technologies Inc.
- 6.4.10 ATandT Inc.
- 6.4.11 Verizon Communications Inc.
- 6.4.12 Crown Castle International Corp.
- 6.4.13 Airspan Networks Holdings Inc.
- 6.4.14 Qucell Inc.
- 6.4.15 Cirrus Core Networks
- 6.4.16 Casa Systems Inc.
- 6.4.17 Sercomm Corporation
- 6.4.18 Baicells Technologies
- 6.4.19 Comba Telecom Systems Holdings Ltd.
- 6.4.20 IP.Access Ltd.
- 6.4.21 Boingo Wireless Inc.
- 6.4.22 Parallel Wireless Inc.
- 6.4.23 JMA Wireless
- 6.4.24 Corning Inc. (SpiderCloud)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026-2034年全球5G小型基地台網路市場規模、佔有率、趨勢和成長分析報告
 亞太地區小型基地台:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)小型基地台5G網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 小型基地台5G網路市場:依組件、網路模型、網路架構、部署模式、頻段、最終用戶、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 小型基地台網路市場-2026-2032年全球市場預測小型基地台5G網路市場-2026-2032年全球市場預測
 小型基地台回程傳輸市場規模、佔有率和成長分析:按技術、頻率、應用、最終用戶和地區分類-2026-2033年產業預測
 小型基地台市場規模、佔有率和成長分析:按類型、技術、部署模式、最終用戶和地區分類-2026-2033年產業預測
 小型基地台市場預測至2034年—按基地台類型、無線技術、部署模式、應用、最終用戶和地區分類的全球分析
 小型基地台網路市場機會、成長要素、產業趨勢分析及2026-2035年預測