


 |
市場調查報告書
商品編碼
2122362
工業潤滑油:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Industrial Lubricants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,工業潤滑油市場將從 2025 年的 228.2 億公升成長到 2026 年的 236.1 億公升,然後在 2031 年達到 279.5 億公升,2026 年至 2031 年的複合年成長率為 3.44%。
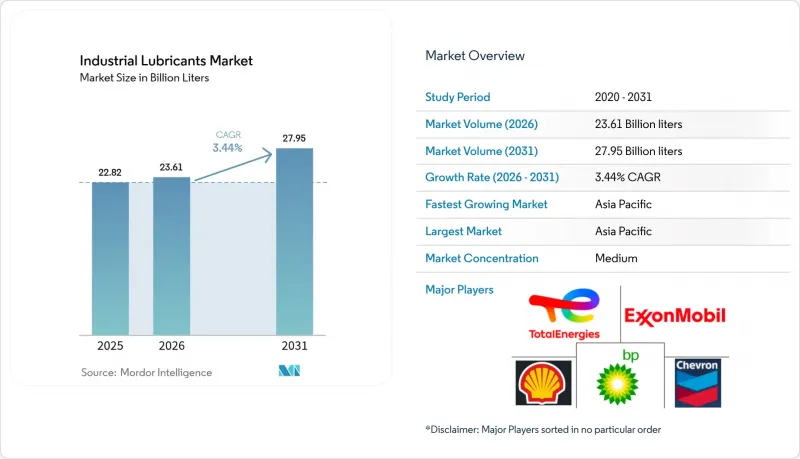
本報告按產品類型(引擎油、液壓油和變速箱油、切削液等)、終端用戶行業(發電、重型機械、食品飲料加工、冶金和金屬加工、化工和製程工業以及其他行業)和地區(亞太地區、北美地區等)進行細分。市場預測以銷售量(公升)為單位。
全球工業潤滑油市場趨勢與洞察
風力發電機機齒輪箱潤滑油的需求正在激增。
隨著全球風電裝置容量的擴張,對標準潤滑油無法滿足的專用變速箱油的需求日益成長。截至2023年12月,中國風電裝置容量已達440吉瓦,許多風機故障歸因於潤滑不足。含有抗磨劑和腐蝕抑制劑的合成油可將檢查週期從六個月延長至三年,從而降低離岸風電場的維護成本。對於偏遠地區的風力發電機而言,卓越的水分分離性能至關重要,可最大限度地減少直升機檢查和維護的需求。開發人員擴大指定使用ISO VG 320-460 PAO混合油,這種混合油可在寬廣的溫度範圍內保持黏度,即使在強風條件下也能保護兆瓦級齒輪箱。一台15兆瓦的離岸風力發電機每次維修週期消耗超過800公升潤滑油,隨著發電容量的成長,工業潤滑油市場的銷售量也隨之直接成長。
潤滑在工業自動化和工業4.0中的重要性
智慧工廠採用在更高溫度和更高速度運作的精密設備,對潤滑油的黏度公差要求極低,且對感測器的干擾也應盡可能小。自動化潤滑系統基於即時分析數據控制潤滑油的輸送,在降低30-40%油耗的同時,也能提高設備正常運轉率。潤滑油即使在磁性塞和紅外線異物監測條件下,也必須保持摩擦學穩定性,這對添加劑的溶解度和金屬離子含量提出了嚴格的要求。目前,人工智慧(AI)平台透過分析振動和溫度數據來調整配方建議,供應商也被要求開發可現場客製化的模組化添加劑包。這些趨勢正在推動工業潤滑油市場中高階合成和混合型產品的佔有率長期成長。
對廢油和洩漏事故實施更嚴格的監管
歐盟和美國多個州強制逐步淘汰 PFAS,迫使配方設計人員重新設計長期使用的產品。替代化學品的認證流程延長了產品上市時間,並增加了研發預算。在使用者層面,回收系統需要記錄「從生產到處置」的可追溯性,這增加了處置成本和用於密封的資本投入。洩漏預防指令要求使用雙層壁儲槽和即時洩漏警報系統,這增加了小規模工作場所的基礎設施成本。雖然這些障礙抑制了短期需求,但也為受監管的高利潤配方在工業潤滑油市場創造了一個利基市場。
細分市場分析
到2025年,機油將佔總銷售額的23.29%,為重工業領域的關鍵發電機和固定式壓縮機提供保護。這一佔有率凸顯了市場對引擎維護的重視,這種重視體現在對單級SAE 40和15W-40多級機油的偏好上,這些機油與老舊引擎相容。然而,隨著原始設備製造商(OEM)轉向換油週期更長的燃氣引擎,對引擎油的需求趨於平穩。相較之下,受機器人、射出成型機和風力發電機變槳系統的擴張推動,液壓油和變速箱油預計將以3.92%的複合年成長率成長。亞太地區對工具機的投資推動了金屬加工液市場的發展,其中離子液體切削液比基準礦物油產品能夠延長刀具壽命。
含二硫化鉬和石墨的合成潤滑脂在極壓軸承市場(該市場常年暴露於200 度C高溫烘箱出口)的市佔率不斷擴大。同時,對加工油的需求與中國、印度和美國石化產業瓶頸問題的解決直接相關。新興的電機冷卻液領域表明,隨著機械特性的不斷變化,工業潤滑油市場也持續重組。
區域分析
預計到2025年,亞太地區將佔全球銷售量的46.88%,並將以3.61%的複合年成長率持續成長至2031年。在該地區,中國煉油企業正透過整合化工產品來提高潤滑油的獲利能力。印度正吸引大量外資,路博潤計畫投資2億美元在奧蘭加巴德新建一座工廠,預計該工廠將成為該公司全球第二大工廠。由於工廠搬遷和可再生能源項目,東南亞國家對液壓油和齒輪油的需求不斷成長。在日本和韓國,精密製造業和嚴格的能源效率目標使得合成油的普及率高於平均水準。
在北美和歐洲,重點在於研發不含全氟烷基和多氟烷基物質(PFAS)的配方並提高碳效率。美國正在利用頁岩衍生的原料,但電動車(EV)的興起正在逐步抑制對傳統機油的需求。歐洲在推廣生物潤滑油方面處於主導地位,這促使配方迅速轉變。由於加拿大油砂開採,高溫潤滑油的需求仍然強勁,墨西哥汽車產業的投資正在擴大當地需求。
在中東和非洲,我們依靠碳氫化合物開採計畫來保障基礎油供應,並促進化工產品領域的多元化發展。沙烏地阿拉伯的Richful Farabi合資企業新建的添加劑工廠將縮短向區域調配商的供應路線。南非的深層礦場開發和奈及利亞煉油廠的維修正在創造利基市場商機。在南美洲,受巴西石化產業瓶頸的解決和智利銅礦擴張的推動,局部出現了高速成長,鞏固了其作為工業潤滑油供應商雖小但重要的市場地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 風力發電機機齒輪箱潤滑油的需求正在激增。
- 工業自動化和工業4.0對潤滑的需求不斷成長
- 過渡到合成和半合成長效潤滑油
- 擁有的採礦和施工機械數量增加
- 超低摩擦生物潤滑劑碳定價政策背後的驅動力
- 市場限制因素
- 加強對廢油和溢油的監管
- 原油衍生基礎油價格的波動
- 由於乾式驅動電動機的普及,石油需求減少。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 機油
- 液壓油,適用於液壓系統和變速箱
- 金屬加工用潤滑液
- 通用工業油
- 齒輪油
- 潤滑脂
- 加工油
- 其他
- 按最終用戶行業分類
- 發電
- 重型機械
- 食品/飲料加工
- 冶金/金屬加工
- 化工和加工工業
- 其他行業(紙漿和造紙、造船等)
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 印尼
- 泰國
- 越南
- 馬來西亞
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 南非
- 埃及
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- AMSOIL Inc.
- Bharat Petroleum Corp. Ltd
- Blaser Swisslube AG
- BP plc(Castrol)
- Carl Bechem GmbH
- Chevron Corporation
- China National Petroleum Corporation(PetroChina)
- China Petroleum & Chemical Corp.(Sinopec)
- ENEOS Corporation
- Eni SpA
- Exxon Mobil Corporation
- FUCHS SE
- Gazprom Neft PJSC
- GS Caltex Corporation
- Gulf Oil International
- Hindustan Petroleum Corp. Ltd
- Idemitsu Kosan Co. Ltd
- Indian Oil Corporation Ltd.
- Kluber Lubrication
- LUKOIL
- Motul
- Petrobras
- Petronas Lubricants International
- Phillips 66 Company
- PT Pertamina(Persero)
- Repsol
- ROCOL
- ROSNEFT
- Shell plc
- TotalEnergies SE
- Valvoline Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the industrial lubricants market size market is expected to grow from 22.82 billion liters in 2025 to 23.61 billion liters in 2026 and is forecast to reach 27.95 billion liters by 2031 at 3.44% CAGR over 2026-2031.
This report is Segmented by Product Type (Engine Oil, Hydraulic and Transmission Fluid, Metalworking Fluid, and More), End-User Industry (Power Generation, Heavy Equipment, Food and Beverage Processing, Metallurgy and Metalworking, Chemical and Process Industries, and Other Industries), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Volume (Liters).
Global Industrial Lubricants Market Trends and Insights
Surging Wind-Turbine Gearbox Lubricant Demand
Global wind-power build-outs are multiplying specialized gearbox-oil requirements that standard fluids cannot satisfy. China's installed wind capacity reached 440 GW by December 2023, with many turbine failures traced to lubrication shortcomings. Synthetic oils fortified with anti-wear and corrosion inhibitors extend service intervals from 6 months to 3 years, trimming offshore maintenance costs. Robust water-separation properties are essential because remote turbines must minimize helicopter-based servicing. Developers increasingly specify ISO VG 320-460 PAO blends that preserve viscosity across wide temperature swings, protecting multi-megawatt gearsets during harsh gust events. Each 15-MW offshore turbine can consume over 800 liters per service cycle, so the industrial lubricants market sees a direct volume lift from larger unit ratings.
Industrial Automation and Industry 4.0 Lubrication Intensity
Smart factories deploy precision equipment that runs hotter and faster, demanding fluids with narrow viscosity tolerances and negligible sensor interference. Automated lubrication systems meter doses based on real-time analytics, cutting consumption 30%-40% while boosting uptime. Fluids must keep tribological stability when exposed to magnetic-plug or infrared debris monitoring, so additive solubility and metal-ion content are tightly specified. Artificial-intelligence platforms now adjust formulation recommendations by reading vibration and temperature feeds, pushing suppliers to create modular additive packages for on-site customization. These developments anchor a long-term upward mix shift within the industrial lubricants market toward premium synthetic and hybrid products.
Stricter Waste-Oil and Spill Regulations
PFAS-phaseout mandates in the EU and several U.S. states force formulators to redesign long-standing products. Certification of alternative chemistries slows time-to-market and inflates R&D budgets. At the user level, collection systems must now document cradle-to-grave traceability, lifting disposal costs and capital outlays for containment. Spill-prevention directives require double-walled tanks and real-time leak alarms, raising infrastructure costs for small workshops. While these hurdles dampen short-term demand, they also open niches for compliant, higher-margin formulations within the industrial lubricants market.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Synthetic and Semi-Synthetic Long-Drain Oils
- Expansion of Mining and Construction Equipment Fleets
- Crude-Derived Base-Oil Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Engine oil contributed 23.29% of 2025 sales, safeguarding critical generators and stationary compressors across heavy industries. This share underscores deep-rooted maintenance routines that favor monograde SAE 40 and 15W-40 multigrades compatible with legacy engines. Yet demand plateaus as OEMs pivot to gas engines with longer drain specifications. Hydraulic and transmission fluids, in contrast, are set to grow at a 3.92% CAGR as robotics, injection-molding machines, and wind-turbine pitch systems expand. Metalworking fluids benefit from Asia-Pacific machine-tool investments, and ionic-liquid cutting oils deliver longer tool life than mineral benchmarks.
Synthetic grease blends incorporating molybdenum disulfide and graphite are grabbing share in extreme-pressure bearings exposed to 200 °C kiln outlets. Meanwhile, demand for process oils ties directly to petrochemical debottlenecking in China, India, and the U.S. Up-and-coming electric-motor cooling oils illustrate how evolving machinery profiles continuously reshape the industrial lubricants market.
Complete Report Scope:
- By Product Type
- Engine Oil
- Hydraulic and Transmission Fluid
- Metalworking Fluid
- General Industrial Oil
- Gear Oil
- Grease
- Process Oil
- Others
- By End-user Industry
- Power Generation
- Heavy Equipment
- Food and Beverage Processing
- Metallurgy and Metalworking
- Chemical and Process Industries
- Other Industries (Pulp and Paper, Marine, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Thailand
- Vietnam
- Malaysia
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 46.88% of 2025 volumes and is tracking a 3.61% CAGR through 2031, where Chinese refiners integrate chemicals to lift lubricant margins. India draws heavy foreign investment, with Lubrizol earmarking USD 200 million for a new Aurangabad plant that will be its second-largest worldwide. Southeast Asian countries welcome factory relocations and renewable-energy projects, driving hydraulic and gear oil uptake. Japan and South Korea sustain above-average synthetic penetration due to precision manufacturing and stringent energy-saving targets.
North America and Europe concentrate on PFAS-free formulations and carbon-linked efficiency gains. The U.S. leverages shale-derived feedstocks, yet EV adoption gradually curbs traditional engine oil demand. Europe leads the policy push that elevates bio-lubricants, compelling rapid formulation shifts. Canada's oil-sands mining keeps high-temperature lubricant requirements active, whereas Mexico's automotive investments broaden local demand.
The Middle-East and Africa rely on hydrocarbon extraction projects that underpin base oil supply and diversify into chemicals. A new additive plant from the Richful-Farabi venture in Saudi Arabia will shorten supply lines for regional blenders. South Africa's deep-level mining and Nigeria's refining upgrades contribute niche opportunities. South America shows pockets of high growth around Brazilian petrochemical debottlenecking and Chilean copper expansions, cementing its role as an important albeit smaller outlet for industrial lubricants market suppliers.
- AMSOIL Inc.
- Bharat Petroleum Corp. Ltd
- Blaser Swisslube AG
- BP p.l.c. (Castrol)
- Carl Bechem GmbH
- Chevron Corporation
- China National Petroleum Corporation (PetroChina)
- China Petroleum & Chemical Corp. (Sinopec)
- ENEOS Corporation
- Eni SpA
- Exxon Mobil Corporation
- FUCHS SE
- Gazprom Neft PJSC
- GS Caltex Corporation
- Gulf Oil International
- Hindustan Petroleum Corp. Ltd
- Idemitsu Kosan Co. Ltd
- Indian Oil Corporation Ltd.
- Kluber Lubrication
- LUKOIL
- Motul
- Petrobras
- Petronas Lubricants International
- Phillips 66 Company
- PT Pertamina (Persero)
- Repsol
- ROCOL
- ROSNEFT
- Shell plc
- TotalEnergies SE
- Valvoline Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging wind-turbine gearbox lubricant demand
- 4.2.2 Industrial automation and Industry 4.0 lubrication intensity
- 4.2.3 Shift toward synthetic and semi-synthetic long-drain oils
- 4.2.4 Expansion of mining and construction equipment fleets
- 4.2.5 Carbon-pricing pull for ultra-low-friction bio-lubricants
- 4.3 Market Restraints
- 4.3.1 Stricter waste-oil and spill regulations
- 4.3.2 Crude-derived base-oil price volatility
- 4.3.3 Dry-drive electric motors reducing oil demand
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Engine Oil
- 5.1.2 Hydraulic and Transmission Fluid
- 5.1.3 Metalworking Fluid
- 5.1.4 General Industrial Oil
- 5.1.5 Gear Oil
- 5.1.6 Grease
- 5.1.7 Process Oil
- 5.1.8 Others
- 5.2 By End-user Industry
- 5.2.1 Power Generation
- 5.2.2 Heavy Equipment
- 5.2.3 Food and Beverage Processing
- 5.2.4 Metallurgy and Metalworking
- 5.2.5 Chemical and Process Industries
- 5.2.6 Other Industries (Pulp and Paper, Marine, etc.)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Indonesia
- 5.3.1.6 Thailand
- 5.3.1.7 Vietnam
- 5.3.1.8 Malaysia
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 South Africa
- 5.3.5.4 Egypt
- 5.3.5.5 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AMSOIL Inc.
- 6.4.2 Bharat Petroleum Corp. Ltd
- 6.4.3 Blaser Swisslube AG
- 6.4.4 BP p.l.c. (Castrol)
- 6.4.5 Carl Bechem GmbH
- 6.4.6 Chevron Corporation
- 6.4.7 China National Petroleum Corporation (PetroChina)
- 6.4.8 China Petroleum & Chemical Corp. (Sinopec)
- 6.4.9 ENEOS Corporation
- 6.4.10 Eni SpA
- 6.4.11 Exxon Mobil Corporation
- 6.4.12 FUCHS SE
- 6.4.13 Gazprom Neft PJSC
- 6.4.14 GS Caltex Corporation
- 6.4.15 Gulf Oil International
- 6.4.16 Hindustan Petroleum Corp. Ltd
- 6.4.17 Idemitsu Kosan Co. Ltd
- 6.4.18 Indian Oil Corporation Ltd.
- 6.4.19 Kluber Lubrication
- 6.4.20 LUKOIL
- 6.4.21 Motul
- 6.4.22 Petrobras
- 6.4.23 Petronas Lubricants International
- 6.4.24 Phillips 66 Company
- 6.4.25 PT Pertamina (Persero)
- 6.4.26 Repsol
- 6.4.27 ROCOL
- 6.4.28 ROSNEFT
- 6.4.29 Shell plc
- 6.4.30 TotalEnergies SE
- 6.4.31 Valvoline Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 非洲重型設備潤滑油:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 工業潤滑油市場:依產品類型、基礎油、最終用戶及通路分類-2026-2032年全球市場預測
 全球工業潤滑油市場:依基礎油、產品類型、最終用途產業及地區分類-預測至2031年滑動表面油:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 工業潤滑油市場規模、佔有率、趨勢和預測:按產品類型、基礎油、最終用途行業和地區分類,2026-2034年
 工業潤滑脂市場:依基礎油類型、增稠劑類型、最終用途產業及地區分類
 工業潤滑油市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年
 工業潤滑油市場規模、佔有率和成長分析(按基礎油類型、產品類型、應用、最終用戶產業和地區分類)-2026-2033年產業預測
 工業潤滑油市場:依類型(液壓油、金屬加工油、齒輪油、壓縮機油、潤滑脂)及產業(建築與礦業、金屬生產、水泥與化工、發電、石油與天然氣)劃分-全球預測至2036年
 工業潤滑劑市場分析及預測(至2035年):類型、產品類型、應用、技術、最終用戶、功能、形態、材質類型、設備