


 |
市場調查報告書
商品編碼
2115884
非洲重型設備潤滑油:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Africa Heavy Equipment Lubricants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,非洲重型機械潤滑油市場將從 2025 年的 4.1649 億公升成長到 2026 年的 4.3565 億公升,然後在 2031 年達到 5.4542 億公升,2026 年至 2031 年的複合成長率為 4.60%。
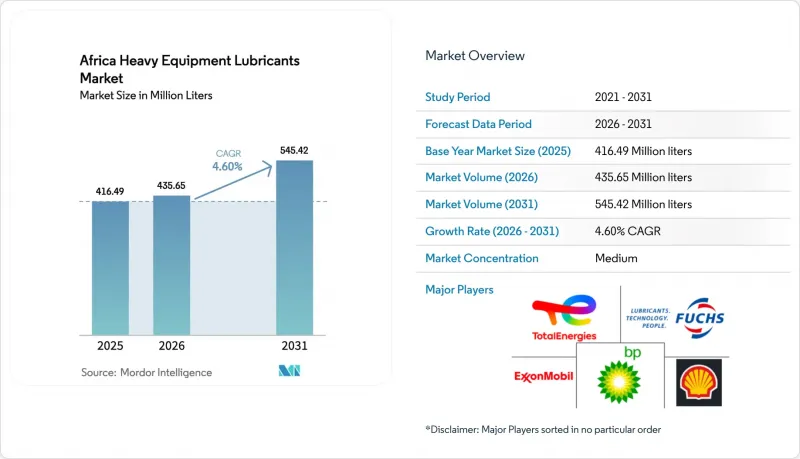
本報告按產品類型(引擎油、變速箱油和液壓油、通用工業油、齒輪油、潤滑脂、加工油及其他)、終端用戶行業(建築、採礦、農業、石油和天然氣)以及地區(埃及、南非、奈及利亞、阿爾及利亞、摩洛哥及其他)進行細分。市場預測以銷售量(公升)為單位。
非洲重型機械潤滑油市場趨勢及洞察。
非洲各地建築業支出增加
非洲的基礎設施投資正蓬勃發展,主要集中在公路、鐵路和雄心勃勃的城市發展項目。這些項目嚴重依賴運作運作的重型機械,導致每個工地潤滑油用量增加。在埃及的托什卡農業擴建計畫中,沃爾沃EC300D和A45G挖土機每天長時間運作。鑑於惡劣的沙漠環境,對高黏度指數液壓油的需求日益成長。在加納的地區道路改善計畫中,柳工機械於2024年投入使用,立即增加了當地的機油消耗量。在阿爾及利亞自2024年開始興建的西部礦山鐵路工程中,專用軌枕工廠的投入使用進一步推動了鐵路施工機械潤滑油的需求。 Mota-Engil公司最近為卡諾-馬拉迪鐵路引入利勃海爾鐵路挖土機,顯示對用於公路和鐵路聯運系統維護的特種潤滑脂的需求不斷成長。這些大規模專案不僅展現了各國對資本規劃的承諾,也保證了非洲重型機械市場對潤滑油的永續需求。
採礦活動擴張和商品價格上漲
採礦業的擴張正成為非洲重型機械潤滑油市場複合年成長率的主要驅動力。在幾內亞,西芒杜專案訂購了小松PC5500-11挖土機和徐工自動卸貨卡車,從而對引擎油、液壓油和極壓潤滑脂產生了強勁的需求。阿爾及利亞的加拉-傑維萊特礦已確保了採礦作業和鐵路車輛所需的潤滑油供應。 2025年3月,南非的莫加拉克韋納礦將引進非洲大陸首台小松P&H 4800XPC挖土機。這款重型機械的轉盤軸承需要高品質的磺酸鈣潤滑脂。由於銅和鋰等大宗商品價格穩定在長期平均水平以上,資本投資和產能運轉率保持強勁,從而帶動了潤滑油消耗量的成長。同時,剛果民主共和國、尚比亞、辛巴威和馬達加斯加等國的電池金屬生產也在擴大,進一步拓展了採礦業主導的潤滑油需求的地域範圍。
假冒劣質潤滑油的氾濫
坦尚尼亞於2025年1月發布的警告凸顯了不符合API和ACEA標準的仿冒品的規模之大。這些產品會導致過早磨損,並使原廠保固失效。儘管奈及利亞和肯亞制定了嚴格的石油潤滑油產業法規,但由於遍遠地區執法不力,非法貿易依然猖獗。彪馬能源公司正透過防篡改包裝和全像圖認證來打擊假冒產品,但品牌所有者仍在資助打擊行動、消費者教育和區塊鏈試點項目,這增加了合規成本。 2025年至2027年間,這項負擔將最為沉重,此後,隨著非洲大陸自由貿易區(AfCFTA)統一標準的實施,加強邊境檢查可望減少仿冒品的供應。
細分市場分析
2025年,機油佔非洲重型機械潤滑油市場的48.17%。這主要得益於柴油動力土木機械、運輸卡車和發電機的使用。預計到2031年,合成機油的複合年成長率將達到6.80%。這是由於高溫和粉塵加速氧化,迫使車隊轉向使用II/III類複合潤滑油。在丹格特煉油廠,徐工XE470D挖土機運作長時間運作。這些挖土機使用優質CK-4潤滑油,該潤滑油因其高黏度指數而被選中,以保護渦輪增壓器。同時,在埃及托什卡工廠,配備先進電液系統的沃爾沃EC480D挖土機依賴變速箱油和液壓油。這些油液是市場上第二大細分市場,因其抗磨添加劑和卓越的抗氧化性能而被選中。最後,在小鬆的P&H 4800XPC型連續換檔式繩索鏟車中,齒輪油和潤滑脂運作至關重要的作用。它們保護機器的最終傳動裝置和轉盤軸承。
為了象徵價值鏈的演變,雪佛龍與Gapuma合作,開始在奈及利亞銷售II類基礎油。此次合作凸顯了該地區合成潤滑油的發展趨勢。同時,Puma Energy的全面流體管理部門的審計顯示,延長換油週期可以顯著降低成本。這項發現正在推動潤滑油配方朝高附加價值方向發展。這些高級產品的零售通路正在不斷拓展。例如,南非的Makro超市現在銷售嘉實多、Engen和道達爾等品牌的合成潤滑油套裝。這種定價策略使得小規模承包商更容易獲得高階潤滑油。因此,預計合成潤滑油的市場佔有率將逐年穩定成長,非洲重型機械潤滑油市場中價值優先於銷售的趨勢也將進一步加強。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 非洲各地建築業支出增加
- 採礦活動擴張和商品價格上漲
- 非洲農業的快速機械化
- 政府車輛競標中強制性油品品質分析要求。
- 非公路用車輛預測性維護遠端資訊處理技術的發展
- 市場限制因素
- 假冒劣質潤滑劑的氾濫
- I類基礎油的全球合理化導致物價急劇上漲。
- 系統長期不穩定導致設備運作減少。
- 價值鏈分析
- 波特五力模型
- 基礎油供應情景
第5章 市場規模與成長預測
- 依產品類型
- 機油
- 變速箱液壓油
- 通用工業油
- 齒輪油
- 潤滑脂
- 加工油
- 其他
- 按最終用戶行業分類
- 建造
- 礦業
- 農業
- 石油和天然氣
- 按地區
- 埃及
- 南非
- 奈及利亞
- 阿爾及利亞
- 摩洛哥
- 其他非洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- BP PLC
- Chevron Corporation
- Conoil PLC
- Cooperative Societe Des Petroleum(Co-op)
- Engen Petroleum Ltd
- Exxon Mobil Corporation
- FUCH
- Hasspetroleum
- KenolKobil Limited
- Lake Oil Group
- Misr Petroleum Co.
- Oando PLC
- Puma Energy
- Sasol
- Shell PLC
- TotalEnergies
- Valvoline Inc
第7章 市場機會與未來展望
According to Mordor Intelligence, the Africa heavy equipment lubricants market size is expected to grow from 416.49 Million liters in 2025 to 435.65 Million liters in 2026 and is forecast to reach 545.42 Million liters by 2031 at 4.60% CAGR over 2026-2031.
This report is Segmented by Product Type (Engine Oil, Transmission and Hydraulic Fluid, General Industrial Oil, Gear Oil, Grease, Process Oil, Other and Product Types), End-User Industry (Construction, Mining, Agriculture, and Oil and Gas), and Geography (Egypt, South Africa, Nigeria, Algeria, Morocco, and Rest of Africa). The Market Forecasts are Provided in Terms of Volume (Litres).
Africa Heavy Equipment Lubricants Market Trends and Insights
Rising Construction-Sector Spend Across Africa
Infrastructure investments in Africa have surged, focusing on roads, railways, and ambitious urban projects. These initiatives are heavily reliant on high-hour fleets, leading to increased lubricant usage at each site. In Egypt's Toshka agricultural expansion, Volvo EC300D and A45G units run for extended hours daily. Given the abrasive desert conditions, there's a heightened demand for high-viscosity-index hydraulic fluids. Ghana's District Road Improvement Program, which welcomed LiuGong machines in 2024, saw an immediate uptick in local engine oil consumption. Algeria's Western Mining Railway, a project under construction since 2024, has introduced a dedicated sleeper plant, further driving lubricant needs for rail-construction machinery. Mota-Engil's recent acquisition of Liebherr rail excavators for the Kano-Maradi line highlights a growing demand for specialty greases, essential for safeguarding dual road-rail systems. These expansive programs not only signify a commitment to national capital plans but also ensure a sustained demand for lubricants in Africa's heavy equipment market.
Expansion of Mining Activities and Commodity Upswing
Mining expansion emerges as the primary driver for the Africa heavy equipment lubricants market's CAGR. In Guinea, the Simandou project has placed orders for Komatsu PC5500-11 excavators and XCMG dumpers, establishing a strong demand for engine oils, hydraulic fluids, and EP greases. Algeria's Gara Djebilet mine secures lubricant volumes for both its mining operations and rail rolling stock. In March 2025, South Africa's Mogalakwena introduced the continent's inaugural Komatsu P&H 4800XPC shovel, a hefty unit, with its slewing bearings dependent on premium calcium-sulfonate grease. With commodity prices for copper and lithium stabilizing above long-term averages, capital expenditures and equipment utilization remain robust, subsequently bolstering lubricant throughput. Concurrently, DRC, Zambia, Zimbabwe, and Madagascar are ramping up their output of battery metals, expanding the geographical reach of mining-driven lubricant demand.
Counterfeit and Sub-Standard Lubricant Prevalence
Tanzania's January 2025 warning underscored the scale of fake products that fail to meet API or ACEA specs, causing premature wear and voiding OEM warranties. Despite strict Petroleum Lubricant Operations Rules, limited rural enforcement enables illicit trade in Nigeria and Kenya. Puma Energy's tamper-evident packaging and hologram authentication fight back, yet brand owners still fund raids, consumer education, and blockchain pilots, adding compliance costs. The drag is most acute over 2025-2027, after which harmonized AfCFTA standards are expected to tighten border checks and shrink counterfeit supply.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Mechanisation in African Agriculture
- Mandatory Oil-Analysis Clauses in Government Fleet Tenders
- Global Group I Base-Oil Rationalisation Driving Price Spikes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Engine oil accounted for 48.17% of the Africa heavy equipment lubricants market size in 2025, underpinned by diesel-powered earthmovers, haul trucks, and generators. Synthetic engine oil is tracking a 6.80% CAGR to 2031 as high ambient temperatures and dust accelerate oxidation, pushing fleets toward Group II/III formulations. At Dangote Refinery, XCMG XE470D excavators routinely clock extensive operating hours each day. To protect their turbochargers, these excavators rely on premium CK-4 oils, chosen for their elevated viscosity index. Meanwhile, at Egypt's Toshka site, Volvo EC480D units, equipped with advanced electro-hydraulic systems, depend on transmission and hydraulic fluids. These fluids, the second-largest segment in the market, are selected for their anti-wear additives and robust oxidation resistance. Lastly, on Komatsu's P&H 4800XPC rope shovel, which operates in continuous shifts, gear oils and greases play a crucial role. They safeguard the machine's final drives and slewing bearings.
In a move highlighting the evolving supply chain, Chevron has teamed up with Gapuma to distribute Group II base oils in Nigeria. This partnership underscores the synthetic growth trend in the region. Meanwhile, audits from Puma Energy's Total Fluid Management reveal that longer drain intervals lead to significant cost savings. This finding is driving a shift towards higher-value fluid formulations. Retail visibility for these premium products is on the rise. For instance, Makro South Africa now offers synthetic packs from brands like Castrol, Engen, and Total. This pricing strategy makes premium lubricants more accessible to smaller contractors. Consequently, the forecast suggests a steady annual increase in the market share of synthetic lubricants, bolstering the Africa heavy equipment lubricants market's emphasis on value over volume.
Complete Report Scope:
- By Product Type
- Engine Oil
- Transmission and Hydraulic Fluid
- General Industrial Oil
- Gear Oil
- Grease
- Process Oil
- Other Product Types
- By End-user Industry
- Construction
- Mining
- Agriculture
- Oil and Gas
- By Geography
- Egypt
- South Africa
- Nigeria
- Algeria
- Morocco
- Rest of Africa
List of Companies Covered in this Report:
- BP PLC
- Chevron Corporation
- Conoil PLC
- Cooperative Societe Des Petroleum (Co-op)
- Engen Petroleum Ltd
- Exxon Mobil Corporation
- FUCH
- Hasspetroleum
- KenolKobil Limited
- Lake Oil Group
- Misr Petroleum Co.
- Oando PLC
- Puma Energy
- Sasol
- Shell PLC
- TotalEnergies
- Valvoline Inc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising construction-sector spend across Africa
- 4.2.2 Expansion of mining activities and commodity upswing
- 4.2.3 Rapid mechanisation in African agriculture
- 4.2.4 Mandatory oil-analysis clauses in government fleet tenders
- 4.2.5 Growth of predictive-maintenance telematics for off-highway fleets
- 4.3 Market Restraints
- 4.3.1 Counterfeit and sub-standard lubricant prevalence
- 4.3.2 Global Group I base-oil rationalisation driving price spikes
- 4.3.3 Chronic grid instability lowering equipment utilisation hours
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
- 4.6 Supply Scenario - Base Oils
5 Market Size and Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Engine Oil
- 5.1.2 Transmission and Hydraulic Fluid
- 5.1.3 General Industrial Oil
- 5.1.4 Gear Oil
- 5.1.5 Grease
- 5.1.6 Process Oil
- 5.1.7 Other Product Types
- 5.2 By End-user Industry
- 5.2.1 Construction
- 5.2.2 Mining
- 5.2.3 Agriculture
- 5.2.4 Oil and Gas
- 5.3 By Geography
- 5.3.1 Egypt
- 5.3.2 South Africa
- 5.3.3 Nigeria
- 5.3.4 Algeria
- 5.3.5 Morocco
- 5.3.6 Rest of Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information,Products and Services, and Recent Developments)
- 6.4.1 BP PLC
- 6.4.2 Chevron Corporation
- 6.4.3 Conoil PLC
- 6.4.4 Cooperative Societe Des Petroleum (Co-op)
- 6.4.5 Engen Petroleum Ltd
- 6.4.6 Exxon Mobil Corporation
- 6.4.7 FUCH
- 6.4.8 Hasspetroleum
- 6.4.9 KenolKobil Limited
- 6.4.10 Lake Oil Group
- 6.4.11 Misr Petroleum Co.
- 6.4.12 Oando PLC
- 6.4.13 Puma Energy
- 6.4.14 Sasol
- 6.4.15 Shell PLC
- 6.4.16 TotalEnergies
- 6.4.17 Valvoline Inc
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Development in Synthetic and Bio-based Lubricants

 工業潤滑油:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 工業潤滑油市場:依產品類型、基礎油、最終用戶及通路分類-2026-2032年全球市場預測
 全球工業潤滑油市場:依基礎油、產品類型、最終用途產業及地區分類-預測至2031年滑動表面油:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 工業潤滑油市場規模、佔有率、趨勢和預測:按產品類型、基礎油、最終用途行業和地區分類,2026-2034年
 工業潤滑脂市場:依基礎油類型、增稠劑類型、最終用途產業及地區分類
 工業潤滑油市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年
 工業潤滑油市場規模、佔有率和成長分析(按基礎油類型、產品類型、應用、最終用戶產業和地區分類)-2026-2033年產業預測
 工業潤滑油市場:依類型(液壓油、金屬加工油、齒輪油、壓縮機油、潤滑脂)及產業(建築與礦業、金屬生產、水泥與化工、發電、石油與天然氣)劃分-全球預測至2036年
 工業潤滑劑市場分析及預測(至2035年):類型、產品類型、應用、技術、最終用戶、功能、形態、材質類型、設備