


 |
市場調查報告書
商品編碼
2121951
歐洲發泡聚苯乙烯(EPS):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Europe Expanded Polystyrene (EPS) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
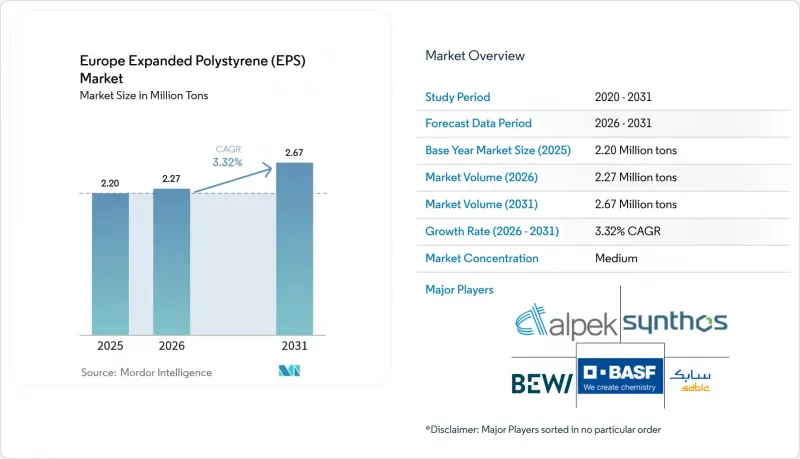
據 Mordor Intelligence 稱,2025 年歐洲發泡聚苯乙烯 (EPS) 市場價值為 220 萬噸,預計到 2031 年將達到 267 萬噸,高於 2026 年的 227 萬噸。
預測期(2026-2031 年)的複合年成長率預計為 3.32%。
本報告按產品類型(白色EPS、灰色和銀色EPS)、終端用戶產業(建築施工、電氣和電子設備、包裝等)以及地區(德國、英國、法國、義大利、西班牙、挪威、瑞典、丹麥、芬蘭及其他)進行細分。市場預測以噸為單位。
歐洲發泡聚苯乙烯(EPS)市場的趨勢與洞察
建築節能標準提倡對隔熱性能的要求。
各國及歐盟日益嚴格的能源標準要求開發商設計低U值(傳熱係數)的牆體、屋頂和地板,這提高了隔熱材料厚度的要求,並支撐了歐洲市場對發泡聚苯乙烯(EPS)保溫解決方案的穩定需求。德國的《建築能源法》已規定外牆U值約為0.20 W/(m²K),這通常需要12-16公分厚的EPS保溫層。儘管有基於高度的防火限制, 發泡材仍佔據了德國外牆系統40%的市場。法國和北歐國家正在擴大類似的性能要求,即將於2024年修訂的《建築能源性能指令》規定,2030年後新建建築必須實現淨零能耗,這進一步鞏固了隔熱材料的長期需求。此外,歐盟的翻維修規模的擴大,政府補貼也鼓勵住宅選擇價格適中且保溫性能優異的保溫系統。為了滿足這些監管要求,製造商正在擴大其產品線,將 Neopol 和石墨納入其中,從而在無需昂貴的結構維修的情況下獲得優異的 R 值。
擴大mRNA生物製藥的冷鏈
mRNA疫苗和先進療法的快速商業化需要從工廠到臨床全程維持2°C至8°C的穩定溫度控制。 EPS(發泡聚苯乙烯)運輸容器在該領域佔據主導地位,因為這種材料的閉孔結構能夠為長途空運和最後一公里配送提供可預測的隔熱和緩衝性能。像Cold Chain Technologies這樣的製造商已在荷蘭布雷達擴大了面向歐洲市場的產能,專門用於支持覆蓋歐盟主要城市(這些城市的GDP佔歐盟GDP的80%)的醫藥物流路線,這些城市都在六小時車程內。歐洲藥典補充11.7的更嚴格規定迫使包裝供應商對萃取物和洗脫液檢驗,因此優先選擇具有良好合規記錄的現有EPS配方。這項冷鏈業務機會帶來了高利潤率,部分抵銷了通用建築發泡材苯乙烯價格差的波動。
原料成本波動給利潤率帶來了壓力。
苯乙烯佔每股收益現金成本的70%之多,使得盈利極易受到苯和石腦油價格波動的影響。 Trinseo宣布2025年1月合約價格每噸上漲55歐元,顯示生產商正試圖保護其利潤率。 Versalis將於2025年4月關閉其位於布林迪西的裂解裝置,這將進一步加劇供應短缺,增加該地區對進口的依賴,並推高運輸成本和外匯風險。原料成本波動劇烈與固定價格的建設合約之間的不匹配,正給加工商的現金流帶來壓力,對整個西北歐的小規模工廠構成挑戰。
細分市場分析
在歐洲發泡聚苯乙烯(EPS)市場,白色EPS佔總消耗量的70.86%。白色EPS繼續用於中空牆、地坪和周邊排水板,在這些應用中,成本仍然是關鍵的選擇標準,而較薄的板材足以滿足建築規範的要求。同時,灰色和銀色EPS預計將擁有最高的成長率,到2031年複合年成長率將達到3.74%。這主要歸功於石墨紅外線反射顆粒將λ值降低至約0.030 W/(m·K)。在外牆保溫複合系統中,灰色EPS可以在保持相同U值的情況下,將層厚從16厘米減少到12厘米,從而實現場地邊界狹窄的都市區的立面維修。 BEWI的CIRCULUM系列產品將卓越的性能與再生珠粒配方相結合,幫助建築師實現節能和循環經濟的目標。製造商們正在投資線上發泡回收和連續塊狀成型,並透過在不影響機械性能的前提下加入更多回收材料,將灰色 EPS 定位為歐洲發泡聚苯乙烯市場中技術和環境方面更優越的選擇。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 從2025年起,建築能源標準將強制要求更高的R值。
- 增強基於mRNA的生技藥品的關鍵冷鏈能力
- 家用電器生產回歸日本,帶動了防護包裝市場的發展。
- 歐盟翻新維修計畫中灰色EPS的應用
- 低成本模組化住宅計劃
- 市場限制因素
- 苯乙烯單體價格波動與原油價差相關
- 菌絲體和模製紙漿替代品的商業化
- 碳定價正在推高石油基聚合物的範圍 3 排放量。
- 價值鏈分析
- 波特五力模型
- 進出口趨勢
第5章 市場規模與成長預測
- 依產品類型
- 白色 EPS
- 灰色和銀色 EPS
- 按最終用戶行業分類
- 建築/施工
- 電氣和電子設備
- 包裝
- 其他(農業和汽車)
- 按地區
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 挪威
- 瑞典
- 丹麥
- 芬蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率(%)** / 排名分析
- 公司簡介
- Alpek SAB de CV
- Austrotherm
- BASF
- BEWi
- Epsilyte LLC
- Ineos
- Kaneka Corporation
- Ravago
- SABIC
- SIBUR International GmbH
- Sunde Group
- Sunpor
- Synthos
- TotalEnergies
- Versalis SpA
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe expanded polystyrene market size was valued at 2.20 million tons in 2025 and estimated to grow from 2.27 million tons in 2026 to reach 2.67 million tons by 2031, at a CAGR of 3.32% during the forecast period (2026-2031).
This report is Segmented by Product Type (White EPS, Gray and Silver EPS), End-User Industry (Building and Construction, Electrical and Electronics, Packaging, Other End-User Industries), and Geography (Germany, United Kingdom, France, Italy, Spain, Norway, Sweden, Denmark, Finland, Rest of Europe). The Market Forecasts are Provided in Terms of Volume (Tons).
Europe Expanded Polystyrene (EPS) Market Trends and Insights
Building Energy Codes Drive Thermal Performance Requirements
Stricter national and EU-wide energy codes compel developers to design walls, roofs, and floors with lower U-values, lifting insulation thickness requirements and supporting steady volume demand for Europe's Expanded Polystyrene market solutions. Germany's Gebaudeenergiegesetz already specifies exterior wall U-values near 0.20 W/(m2K), which typically necessitates 12-16 cm of EPS, cementing roughly 40% share for the foam in German facade systems despite height-based fire-safety limits. France and the Nordics extend similar performance stipulations, and the 2024 recast of the Energy Performance of Buildings Directive sets a net-zero mandate for new structures from 2030, locking in long-range insulation demand. Retrofit volumes also rise under the EU Renovation Wave, with grants steering homeowners toward thermally efficient yet affordable systems. Producers broaden their Neopor and graphite-enriched lines in this compliance-driven landscape to deliver superior R-values without costly structural modifications.
mRNA Biologics Cold Chain Expansion
Rapid commercialization of mRNA vaccines and advanced therapeutics requires 2 °C-to-8 °C stability from factory to clinic. EPS shippers dominate this lane because the material's closed-cell matrix provides predictable insulation and cushioning over long-haul flights and last-mile parcels. Manufacturers such as Cold Chain Technologies have added European capacity in Breda, Netherlands, specifically to serve pharma corridors reaching 80% of EU GDP centers within a six-hour drive. Regulatory tightening under European Pharmacopoeia Supplement 11.7 pushes packaging suppliers to validate extractables and leachables, favoring incumbent EPS formulations with proven compliance records. The cold-chain opportunity carries premium margins that partially offset styrene spread volatility in commodity construction foam.
Feedstock Cost Volatility Pressures Margins
Styrene accounts for up to 70% of EPS cash costs, making profitability sensitive to benzene-and naphtha swings. January 2025 contract hikes of EUR 55 per ton announced by Trinseo illustrate producer attempts to defend margins. Structural tightness deepens as Versalis shutters its Brindisi cracker in April 2025, widening the region's import dependency and magnifying freight and currency risks. The mismatch between volatile raw-material outlays and fixed-price construction contracts squeezes converter cash flows, challenging smaller plants across Northwest Europe.
Other drivers and restraints analyzed in the detailed report include:
- Appliance Manufacturing Reshoring Momentum
- EU Renovation Wave Accelerates Gray EPS Adoption
- Sustainable Alternatives Gain Market Traction
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Europe's Expanded Polystyrene market size for white grades accounted for 70.86% share of overall consumption. White EPS persists in cavity walls, slab-on-grade floors, and perimeter drainage boards where cost remains the critical selector and modest panel thicknesses suffice for code compliance. However, gray and silver grades register the fastest 3.74% CAGR to 2031 as graphite's infrared-reflective particles lower λ-values to around 0.030 W/(m*K). In external thermal insulation composite systems, gray EPS reduces layer thickness from 16 cm to 12 cm for the same U-value, unlocking facade renovation in urban districts with tight lot lines. BEWI's CIRCULUM line couples the performance edge with recycled bead content, helping architects reconcile energy and circularity targets. Producers invest in in-line blowing-agent recovery and continuous block molding to embed more reclaim without sacrificing mechanical properties, positioning gray EPS as a technical and eco-credential upgrade within the Europe Expanded Polystyrene market.
Complete Report Scope:
- By Product Type
- White EPS
- Gray and Silver EPS
- By End-user Industry
- Building and Construction
- Electrical and Electronics
- Packaging
- Other End-user Industries (Agriculture and Automotive)
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Norway
- Sweden
- Denmark
- Finland
- Rest of Europe
List of Companies Covered in this Report:
- Alpek SAB de CV
- Austrotherm
- BASF
- BEWi
- Epsilyte LLC
- Ineos
- Kaneka Corporation
- Ravago
- SABIC
- SIBUR International GmbH
- Sunde Group
- Sunpor
- Synthos
- TotalEnergies
- Versalis S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Building-energy codes mandating higher R-values from 2025
- 4.2.2 Mandatory cold-chain capacity additions for mRNA-class biologics
- 4.2.3 Re-shoring of appliance production boosting domestic protective packaging
- 4.2.4 Grey-EPS adoption in EU "Renovation Wave" retrofit projects
- 4.2.5 Low-cost modular housing programmes
- 4.3 Market Restraints
- 4.3.1 Styrene monomer price volatility tracking crude-oil spreads
- 4.3.2 Commercialisation of mycelium and moulded-pulp substitutes
- 4.3.3 Carbon-pricing schemes inflating Scope-3 footprints of petro-polymers
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Import-Export Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 White EPS
- 5.1.2 Gray and Silver EPS
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Electrical and Electronics
- 5.2.3 Packaging
- 5.2.4 Other End-user Industries (Agriculture and Automotive)
- 5.3 By Geography
- 5.3.1 Germany
- 5.3.2 United Kingdom
- 5.3.3 France
- 5.3.4 Italy
- 5.3.5 Spain
- 5.3.6 Norway
- 5.3.7 Sweden
- 5.3.8 Denmark
- 5.3.9 Finland
- 5.3.10 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Alpek SAB de CV
- 6.4.2 Austrotherm
- 6.4.3 BASF
- 6.4.4 BEWi
- 6.4.5 Epsilyte LLC
- 6.4.6 Ineos
- 6.4.7 Kaneka Corporation
- 6.4.8 Ravago
- 6.4.9 SABIC
- 6.4.10 SIBUR International GmbH
- 6.4.11 Sunde Group
- 6.4.12 Sunpor
- 6.4.13 Synthos
- 6.4.14 TotalEnergies
- 6.4.15 Versalis S.p.A.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 2026年全球發泡聚苯乙烯市場報告
 2026-2030年全球發泡聚苯乙烯市場
 美國發泡聚苯乙烯(EPS):市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 發泡聚苯乙烯市場報告:依產品、終端用途產業及地區分類(2026-2034 年)
 發泡聚苯乙烯市場:依形態、等級、最終用途產業、通路和應用程式分類-2026-2032年全球市場預測發泡聚苯乙烯增密設備市場:按機器類型、操作模式、類別、應用和最終用戶分類 - 全球預測 2026-2032
 發泡聚苯乙烯市場-全球產業規模、佔有率、趨勢、機會及預測(依產品類型、最終用途、地區及競爭格局分類,2021-2031年)發泡聚苯乙烯(EPS):市佔率分析、產業趨勢與統計、成長預測(2026-2031)
 發泡聚苯乙烯包裝市場規模、佔有率和成長分析(按產品類型、最終用途產業、密度、形狀、應用和地區分類)-2026-2033年產業預測
 珠狀聚苯乙烯(EPS)泡沫包裝市場規模、佔有率、成長及全球產業分析:按類型、應用和地區劃分的洞察與預測(2024-2032 年)