


 |
市場調查報告書
商品編碼
2121695
亞太地區防爆設備:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Asia-Pacific Explosion Proof Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
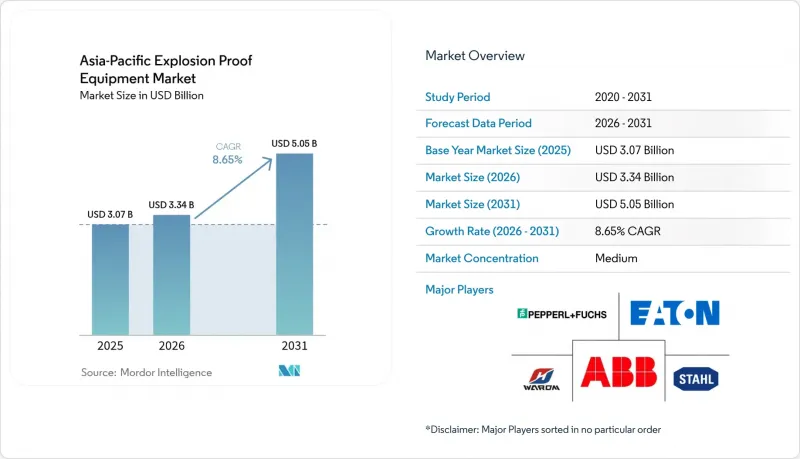
根據 Mordor Intelligence 預測,亞太地區防爆設備市場規模將從 2025 年的 30.7 億美元成長到 2026 年的 33.4 億美元,然後在 2031 年達到 50.5 億美元,2026 年至 2031 年的複合年成長率為 8.65%。
本報告按類型(防爆、防爆、防爆隔離)、區域(0區、1區、2區及其他)、最終用戶(石油天然氣、化工及石化、及其他)、系統(電力系統、物料輸送、及其他)及國家(中國、印度、及其他)進行細分。市場預測以美元計價,並基於現有數據。
亞太地區防爆設備市場趨勢與洞察
加強危險區域法規的執行力道
ATEX 和 IECEx 的合規範圍已從最初僅限於石油和天然氣行業擴展到涵蓋製藥、食品加工、電池材料等更廣泛的領域。中國 2024 年修訂的 GB-3836 標準提高了 0 區和 20 區的防護等級,促使大量設備維修。印度的 PESO 系統收緊了進口核准,加快了老舊設備的更換週期。澳洲和紐西蘭已將 ANZEx 與 IECEx 相協調,方便跨國公司在多個國家獲得認證。這種協調降低了設計複雜性,並促成了區域產品平台的建立,從而降低了開發成本並縮短了產品上市時間。隨著越來越多的工廠尋求對其 2020 年前安裝的設備進行重新認證,亞太防爆設備市場出現了大量重複訂單。
亞洲新興經濟體石油、天然氣和採礦業產能擴張進展
印尼國家石油公司(Pertamina)已累計200億美元用於其上游業務,目標是在2030年前實現這一目標,這需要堅固耐用的耐火電機、加壓分析儀器防護罩和Ex p型通風撬裝設備。越南龍山石化中心和澳洲關鍵礦產資源的開採熱潮分別顯著擴大了1區和20區的安裝面積。向海上開採鑽機和偏遠礦山延伸的供應鏈,推動了對低維護需求和狀態監測功能的防爆照明和驅動裝置的需求成長。項目通常會整合包括馬達、控制設備、攝影機和氣體探測器在內的多系統組件,這推高了平均訂單金額,並進一步加劇了供應商鎖定問題。
防爆設備的資本支出(CAPEX)和安裝成本較高。
防爆馬達、驅動器和控制面板的價格比標準產品高出 150% 至 300%。此外,認證安裝、剛性金屬導管和加壓硬體還會使專案預算增加 40% 至 60%。新興國家的中小型企業通常會等到檢查員提出整改建議後才進行設備升級,導致需求激增而非穩定成長。美元外匯波動會增加進口成本,尤其是從美國和歐洲採購的感測器和晶片組組件。儘管政府提供信貸額度,但發展緩慢的處理器市場接受度正在下降,融資資金籌措依然巨大。
細分市場分析
到2025年,防爆外殼將佔據亞太地區防爆設備市場佔有率的55.12%,這主要得益於石油和天然氣產業的成熟應用。然而,本質安全型和加壓型外殼預計將以10.05%的複合年成長率穩步成長至2031年,顯著提升亞太地區防爆設備市場規模,尤其是在數據密集型控制室和感測器網路中。製造商正利用半導體小型化技術,在不超出熱極限的前提下,將更高功率整合到Ex i電路中,從而將應用範圍擴展到閥門執行器和小型馬達。加壓系統在處理多種氣體流的分析儀器室中日益普及,而集中式空氣吹掃撬裝系統透過同時保護多個設備外殼,降低了生命週期成本。封裝和粉末填充解決方案正在高壓驅動和精密儀器領域開闢新的市場,尤其因其在製藥行業潔淨室中的無污染設計而備受青睞。
第二代預防性解決方案整合了一個微控制器,用於記錄壓力、溫度和吹掃循環,並將診斷資訊傳輸到SCADA平台。韌體更新支援遠端校準,無需現場維護,確保符合審核要求。服務模式正從部件更換轉向基本契約,以確保洩漏率達到閾值。競爭對手正在探索積層製造(3D列印)外殼,以最佳化氣流並減輕高達25%的重量,從而降低起重機和地基的安裝成本。
1區佔銷售額的33.45%,優先考慮氣體和蒸氣頻繁存在的區域的設備,並持續對成熟煉油廠進行維修。同時,粉塵較多的20區以11.35%的複合年成長率成為市場上成長最快的區域,因為片劑包覆、麵粉加工和電池材料研磨生產線重新定義了危險區域的優先順序。澳洲的幾家鋰加工廠已為球磨機指定了混合型Ex t/Ex p防護等級,這推動了雙等級防護設計的創新。設備製造商正在開發符合IEC 60079-31(粉塵)和60079-2(壓力)標準的通用安裝套件,從而可以使用單一SKU管理不同工廠區域的庫存。
0 區仍然是一個特殊區域,僅限於持續暴露於危險環境(例如儲存槽內部)的區域。新型 Ex ia 級超音波厚感測器能夠對運作中的儲罐頂部進行檢測,從而減少高溫作業許可證的數量和停機時間。 2 區仍然廣泛應用於可以接受間歇性風險的場所,原始設備製造商 (OEM) 正致力於開發兼顧合規性和價格的成本效益型外殼,以與來自灰色市場的進口產品競爭。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 調查假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加強危險區域法規的執行(ATEX/IECEx、IEC 60079系列、中國GB-3836修訂版)
- 亞洲新興經濟體石油、天然氣和採礦業產能擴張進展
- 加快向防爆LED照明和智慧感測器的過渡
- 工業自動化技術的快速發展推動了對本質安全控制系統日益成長的需求。
- 通過認證測試實驗室本地化縮短審核前置作業時間。
- 亞太地區蓬勃發展的製藥製造群需要符合GMP標準的防爆設備。
- 市場限制因素
- 防爆設備的資本支出(CAPEX)和安裝成本較高。
- 安裝和維護經認證的防爆設備人員短缺。
- 仿冒品產品的氾濫導致消費者信心下降。
- 由於銅和稀土元素磁鐵價格波動,馬達成本不斷上漲。
- 產業價值鏈分析
- 宏觀經濟因素的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 防爆(阻燃/Ex d)
- 防爆(本質安全型防爆/Ex i,加壓型防爆/Ex p)
- 爆炸分離(封裝/Ex m,粉末填充/Ex q)
- 區
- 0區
- 1區
- 2區
- 20區
- 21區
- 22區
- 最終用戶
- 石油和天然氣
- 化工/石油化工
- 能源和發電
- 礦業
- 製藥
- 食品加工
- 其他
- 系統特定
- 電源系統(變壓器、開關設備)
- 物料輸送(起吊裝置、輸送機)
- 馬達驅動
- 自動化和控制系統(PLC、SCADA)
- 監控(攝影機、氣體探測器)
- 照明系統(LED燈、螢光)
- 國家
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 印尼
- 泰國
- 越南
- 馬來西亞
- 亞太其他地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB Ltd.
- Eaton Corporation plc
- R. Stahl AG
- Pepperl+Fuchs SE
- Warom Technology Inc.
- Bartec GmbH
- Emerson Electric Co.
- Siemens AG
- Honeywell International Inc.(RAE Systems)
- Marechal Electric SA
- Adalet Industries LLC
- Phoenix Mecano AG
- Alloy Industry Co. Ltd.
- Cordex Instruments Ltd.
- GM International srl
- CZ Electric Co. Ltd.
- Feice Explosion-Proof Electric Co. Ltd.
- Wolong Electric Group Co. Ltd.
- WEG Equipamentos Eletricos SA
- Toshiba International Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the Asia-Pacific explosion-proof equipment market size is expected to grow from USD 3.07 billion in 2025 to USD 3.34 billion in 2026 and is forecast to reach USD 5.05 billion by 2031 at 8.65% CAGR over 2026-2031.
This report is Segmented by Type (Explosion Proof, Explosion Prevention, and Explosion Segregation), Zone (Zone 0, Zone 1, Zone 2, and More), End User (Oil and Gas, Chemical and Petrochemical, and More), System (Power Supply Systems, Material Handling, and More), and Country (China, India, and More). The Market Forecasts are Provided in Terms of Value (USD), Based On Availability.
Asia-Pacific Explosion Proof Equipment Market Trends and Insights
Stricter Regulatory Enforcement Across Hazardous Zones
ATEX and IECEx compliance have expanded from a narrow focus on oil and gas to a broader mandate encompassing pharmaceuticals, food processing, and battery materials. China's GB-3836 upgrade in 2024 imposed higher protection levels for Zone 0 and Zone 20, prompting widespread retrofits. India's PESO regime tightened import approvals, accelerating replacement cycles for legacy gear. Australia and New Zealand have aligned the ANZEx with IECEx, easing multi-country certifications for multinationals. The convergence reduces engineering complexity, enabling regional product platforms that lower development costs and accelerate time-to-market. As plants seek recertification of equipment installed before 2020, the Asia-Pacific explosion-proof equipment market records sizable repeat orders.
Rising Oil, Gas and Mining Capacity Expansions in Emerging Asian Economies
Indonesia's Pertamina has earmarked USD 20 billion for upstream projects through 2030, necessitating robust flameproof motors, pressurized analyzer shelters, and Ex p ventilation skids. Vietnam's Long Son petrochemical hub and Australia's critical minerals rush add large Zone 1 and Zone 20 footprints, respectively. Extended supply lines in offshore rigs and remote mines amplify the need for low-maintenance, condition-monitored Ex lighting and drives. Projects often bundle multi-system packages, such as motors, controls, cameras, and gas detectors, which boosts average order values and deepens vendor lock-in.
High CAPEX and Installation Cost of Explosion-Proof Equipment
Explosion-proof motors, drives, and control panels cost 150-300% more than their general-purpose equivalents. Additionally, certified installation, rigid metallic conduit, and pressurization hardware increase project budgets by an extra 40-60%. SMEs in emerging economies often defer upgrades until inspectors issue notices, causing demand spikes rather than steady growth. Currency swings against the USD raise import bills, especially for sensor and chipset components sourced from the U.S. and Europe. Financing gaps remain acute despite government credit lines, as the uptake among cash-constrained processors slows.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Shift Toward Explosion-Proof LED Lighting and Smart Sensors
- Rapid Industrial Automation Driving Demand for Intrinsically-Safe Control Systems
- Shortage of Certified Ex Installation and Maintenance Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Explosion-proof enclosures retained 55.12% of the Asia-Pacific explosion-proof equipment market share in 2025, driven by entrenched oil and gas usage. Still, intrinsic safety and pressurization drive a vigorous 10.05% CAGR through 2031, lifting their contribution to the Asia-Pacific explosion-proof equipment market size, particularly in data-intensive control rooms and sensor networks. Manufacturers exploit semiconductor miniaturization to embed higher power levels into Ex i circuits without exceeding thermal limits, broadening applicability to valve actuators and small motors. Pressurization systems are gaining ground in analyzer houses that handle multiple gas streams; centralized air-purge skids protect several cabinets simultaneously, reducing lifecycle costs compared to per-device enclosures. Encapsulation and powder-fill solutions carve out niches in high-voltage drives and precision instruments, prized for their contamination-free design, especially in clean-room pharmaceuticals.
Second-generation prevention solutions integrate micro-controllers that log pressure, temperature, and purge cycles, transmitting diagnostics to SCADA platforms. Firmware updates enable remote calibration, eliminating the need for site visits and ensuring audit readiness. Service models shift from parts replacement to outcome-based contracts guaranteeing leak-rate thresholds. Competitors are exploring additive-manufactured housings that optimize airflow and reduce weight by up to 25%, thereby lowering crane and footing costs during installation.
Zone 1 retained 33.45% revenue as operators prioritized equipment for areas with frequent gas-vapor presence, sustaining steady retrofits in mature refineries. Conversely, dust-heavy Zone 20 posts the market's fastest 11.35% CAGR, propelled by tablet coating, flour milling, and battery-materials grinding lines that redefine hazardous-area priorities. Several lithium-processing plants in Australia specify hybrid Ex t/Ex p protection for ball mills, which has spurred innovations in dual-rating designs. Equipment makers develop universal mounting kits compliant with both IEC 60079-31 (dust) and 60079-2 (pressurization), enabling single-SKU stocking across varied plant zones.
Zone 0 remains a specialist zone, limited to constant-exposure environments, such as storage tank interiors. New ultrasonic thickness sensors rated Ex ia allow in-service tank-roof inspections, reducing hot-work permits and downtime. Zone 2 retains widespread appeal where intermittent risk suffices; OEMs focus on cost-optimized enclosures that balance compliance and price to counter grey-market imports.
Complete Report Scope:
- By Type
- Explosion Proof (Flameproof/Ex d)
- Explosion Prevention (Intrinsic Safety/Ex i, Pressurisation/Ex p)
- Explosion Segregation (Encapsulation/Ex m, Powder-filling/Ex q)
- By Zone
- Zone 0
- Zone 1
- Zone 2
- Zone 20
- Zone 21
- Zone 22
- By End User
- Oil and Gas
- Chemical and Petrochemical
- Energy and Power
- Mining
- Pharmaceutical
- Food Processing
- Other End Users
- By System
- Power Supply Systems (Transformers, Switchgear)
- Material Handling (Hoists, Conveyors)
- Motors and Drives
- Automation and Control Systems (PLC, SCADA)
- Surveillance and Monitoring (Cameras, Gas Detectors)
- Lighting Systems (LED, Fluorescent)
- By Country
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Thailand
- Vietnam
- Malaysia
- Rest of Asia Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Eaton Corporation plc
- R. Stahl AG
- Pepperl+Fuchs SE
- Warom Technology Inc.
- Bartec GmbH
- Emerson Electric Co.
- Siemens AG
- Honeywell International Inc. (RAE Systems)
- Marechal Electric SA
- Adalet Industries LLC
- Phoenix Mecano AG
- Alloy Industry Co. Ltd.
- Cordex Instruments Ltd.
- G.M. International srl
- CZ Electric Co. Ltd.
- Feice Explosion-Proof Electric Co. Ltd.
- Wolong Electric Group Co. Ltd.
- WEG Equipamentos Eletricos S.A.
- Toshiba International Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter regulatory enforcement across hazardous zones (ATEX/IECEx, IEC 60079 series, China GB-3836 upgrade)
- 4.2.2 Rising oil, gas and mining capacity expansions in emerging Asian economies
- 4.2.3 Accelerating shift toward explosion-proof LED lighting and smart sensors
- 4.2.4 Rapid industrial automation driving demand for intrinsically-safe control systems
- 4.2.5 Localisation of certification labs reducing approval lead-times
- 4.2.6 Booming Asia-Pacific pharmaceutical manufacturing clusters needing GMP-compliant Ex equipment
- 4.3 Market Restraints
- 4.3.1 High CAPEX and installation cost of explosion-proof equipment
- 4.3.2 Shortage of certified Ex installation and maintenance talent
- 4.3.3 Proliferation of counterfeit/non-certified devices eroding buyer confidence
- 4.3.4 Volatile copper and rare-earth magnet prices inflating motor costs
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Explosion Proof (Flameproof/Ex d)
- 5.1.2 Explosion Prevention (Intrinsic Safety/Ex i, Pressurisation/Ex p)
- 5.1.3 Explosion Segregation (Encapsulation/Ex m, Powder-filling/Ex q)
- 5.2 By Zone
- 5.2.1 Zone 0
- 5.2.2 Zone 1
- 5.2.3 Zone 2
- 5.2.4 Zone 20
- 5.2.5 Zone 21
- 5.2.6 Zone 22
- 5.3 By End User
- 5.3.1 Oil and Gas
- 5.3.2 Chemical and Petrochemical
- 5.3.3 Energy and Power
- 5.3.4 Mining
- 5.3.5 Pharmaceutical
- 5.3.6 Food Processing
- 5.3.7 Other End Users
- 5.4 By System
- 5.4.1 Power Supply Systems (Transformers, Switchgear)
- 5.4.2 Material Handling (Hoists, Conveyors)
- 5.4.3 Motors and Drives
- 5.4.4 Automation and Control Systems (PLC, SCADA)
- 5.4.5 Surveillance and Monitoring (Cameras, Gas Detectors)
- 5.4.6 Lighting Systems (LED, Fluorescent)
- 5.5 By Country
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 South Korea
- 5.5.5 Australia
- 5.5.6 Indonesia
- 5.5.7 Thailand
- 5.5.8 Vietnam
- 5.5.9 Malaysia
- 5.5.10 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Eaton Corporation plc
- 6.4.3 R. Stahl AG
- 6.4.4 Pepperl+Fuchs SE
- 6.4.5 Warom Technology Inc.
- 6.4.6 Bartec GmbH
- 6.4.7 Emerson Electric Co.
- 6.4.8 Siemens AG
- 6.4.9 Honeywell International Inc. (RAE Systems)
- 6.4.10 Marechal Electric SA
- 6.4.11 Adalet Industries LLC
- 6.4.12 Phoenix Mecano AG
- 6.4.13 Alloy Industry Co. Ltd.
- 6.4.14 Cordex Instruments Ltd.
- 6.4.15 G.M. International srl
- 6.4.16 CZ Electric Co. Ltd.
- 6.4.17 Feice Explosion-Proof Electric Co. Ltd.
- 6.4.18 Wolong Electric Group Co. Ltd.
- 6.4.19 WEG Equipamentos Eletricos S.A.
- 6.4.20 Toshiba International Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 防爆比例閥市場:全球市場預測(2026-2032年)
 防爆灌裝機市場規模、佔有率和成長分析:按機器類型、填充技術、產品類型、應用、最終用戶產業和地區分類 - 2026-2033 年產業預測
 南美洲防爆裝置:市場佔有率分析、產業趨勢與統計數據以及成長預測(2026-2031 年)防爆設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026年全球防爆設備市場報告
 全球防爆設備市場規模、佔有率、趨勢及成長分析報告(2026-2034年)2026年全球防爆艙市場報告防爆電梯市場:按產品、類型、安裝方式、負載容量、速度和最終用戶分類-2026-2032年全球預測防爆加濕器市場按類型、濕度輸出、應用、最終用戶和分銷管道分類,全球預測(2026-2032)
 防爆設備市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、材質、設備、最終用戶、安裝類型分類