


 |
市場調查報告書
商品編碼
2121540
積層製造與材料:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Additive Manufacturing And Materials - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
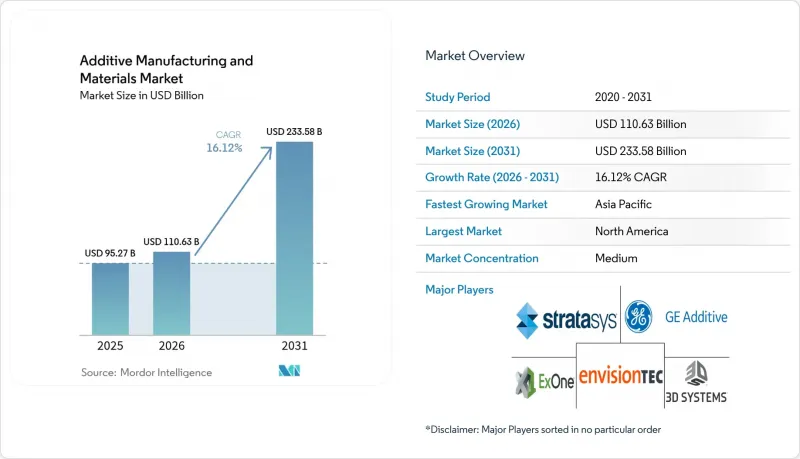
根據 Mordor Intelligence 預測,積層製造和材料市場將從 2025 年的 952.7 億美元成長到 2026 年的 1106.3 億美元,到 2031 年將達到 2335.8 億美元,2026 年至 2031 年的複合年成長率為 16.12%。
本報告按技術(聚合物基、金屬基、陶瓷基等)、材料類型(聚合物、金屬、陶瓷、複合材料等)、最終用戶(航太與國防、汽車、醫療、工業機械、消費品、建築、教育與研究等)和地區進行細分。市場預測以美元計價。
全球積層製造及材料市場趨勢及洞察
汽車和航太領域對輕量化零件的需求
航太原始設備製造商 (OEM) 正在將多部件組件整合為單一 3D 列印零件,以減輕飛機重量並降低維護成本。通用電氣航空集團 (GE Aviation) 的 3D 列印燃油噴嘴可取代 20 個零件,使航空公司每架飛機的全生命週期營運成本降低 160 萬美元。波音公司在其 787 飛機上採用了鈦合金格柵支架,在滿足結構標準的前提下,降低了 200 萬至 300 萬美元的零件成本。汽車製造商也在電池外殼和煞車系統中尋求類似的零件整合,以延長電動車的續航里程。拓樸最佳化軟體能夠實現機械加工無法實現的有機形狀,為早期採用者帶來效能優勢。 ASTM F2792 標準規範了術語和測試方法,使認證機構能夠更快地批准飛行關鍵零件。
針對每位患者量身訂製的醫療植入的快速普及
粉末層熔融技術能夠製造出根據個體解剖結構量身定做的多孔鈦植入,從而促進骨整合並降低失敗率。史賽克公司已生產超過200萬個此類植入物,證明了醫院級積層製造工作流程的擴充性。美國FDA的「即時護理」指南允許獲得認證的醫院自行列印手術導板,從而縮短前置作業時間並降低庫存成本。分散式生產將價值中心從集中式工廠轉移到臨床環境,縮小了物流規模。儘管航太領域的資源分配緊張,但不斷成長的高階需求正迫使鈷鉻合金和鈦粉供應商擴大其霧化能力。
高性能金屬和聚合物高成本
PEEK、PEKK 和航太級鈦粉的價格居高不下,中小型代工製造商難以負擔。霧化器產能有限以及高能耗的等離子體製程推高了原料成本,而買家則要求批量折扣。供應商進退兩難:一方面是尋求折扣的客戶,另一方面是要求研發投入的投資者,這導致下一代材料的市場推廣被延緩。因此,在成本曲線改善之前,汽車和消費品產業只能採購原型產品和高利潤零件。
細分市場分析
定向能量沉積 (DED) 的複合年成長率 (CAGR) 為 16.98%。這主要得益於航太維修的需求,該領域需要製造米級零件,其層體積超過了粉末層熔融 (PBD) 的極限。該領域受益於線材原料的優勢,線材比粉末便宜 30% 至 50%,並且能夠重複利用其他系統中原本會被浪費的材料。同時,熔融沈積成型 (FDM) 由於其在教育、設計和低應力工業夾具等領域的廣泛應用,在積層製造和材料市場中保持著 39.68% 的佔有率。混合型數控積層製造平台結合了雷射覆層和五軸銑床,可在單次裝夾中實現所需的公差和表面粗糙度目標。
粉末層熔融(PBF)仍然是植入和火箭渦輪泵部件的標準製造程序,這些部件大量採用晶格結構,且層厚要求小於 80 µm。黏著劑噴塗成型(BJ)技術正在發展應用於鋼製泵殼和砂型鑄造模具的製造,一旦燒結製程瓶頸得到解決,它將在產能方面具有優勢。新興的微波體積熔融系統有望實現數量級更快的加工速度,預示著未來製造時間將不再是決定成本效益的主要因素。
區域分析
預計到2025年,北美將佔據積層製造和材料市場36.45%的佔有率,主要得益於其國防預算、NASA的深空探勘舉措以及成熟的供應商生態系統。聯邦稅收優惠和第174條研發費用累計規則正在鼓勵對新生產線進行資本投資。 FDA關於3D列印植入的510(k)指南正在縮短醫療設備OEM廠商的產品上市時間,並促進國內粉末消費。
亞太地區成長最快,複合年成長率達16.55%,這主要得益於中國大力扶持國內領先的3D列印機企業,以減少對進口引擎零件的依賴。新加坡國家積層製造叢集正通過認證航太合金和培訓工程師,將新加坡打造為區域出口中心。印度的生產連結獎勵計畫計劃(PLI)為汽車和能源行業的金屬3D列印機採購津貼,而澳洲的合作研究中心(CRC)則致力於推廣使用本地礦石的鈦粉霧化技術。
歐洲正著力發展永續性,歐盟的「Fit-for-55」計畫正推動汽車製造商採用3D列印技術製造輕量化支架,以減少車輛排放氣體。歐洲太空總署(ESA)在國際太空站(ISS)上展示了首批3D列印的不銹鋼零件,證實了3D列印技術在微重力環境下對月球基礎設施的有效性。德國汽車製造商聯合開發了一種鋁矽合金,可實現無縫焊接,且不會產生熱裂紋缺陷,為碰撞安全相關應用樹立了新標準。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 汽車和航太領域對輕量化零件的需求
- 個人化醫療植入在患者身上的快速普及
- 聚合物和金屬粉末價格下降
- 政府資助和標準協調
- 透過回收材料促進循環經濟
- 為太空和遠端任務提供本地化、小規模生產
- 市場限制因素
- 高性能金屬和聚合物高成本
- 對智慧財產權保護的擔憂
- 嚴格的奈米粉末處理環境、健康與安全 (EHS) 法規
- 關鍵合金元素的供應鏈波動
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素的影響
- 波特五力分析
第5章:預測市場規模與成長率
- 透過技術
- 基於聚合物的技術
- FDM(熔融沈積成型)
- SLA(立體光刻技術)
- DLP(數位光處理)
- 材料噴塗(PolyJet)
- 黏著劑噴塗成型- 聚合物
- 金屬技術
- 粉末層熔融(SLM,EBM)
- 定向能量沉積
- 陶瓷技術
- 陶瓷SLA
- 陶瓷黏著劑噴塗成型
- 其他技術
- 基於聚合物的技術
- 依材料類型
- 聚合物
- 通用熱塑性塑膠(ABS、PLA)
- 工程塑膠(PA、PEEK)
- 光聚合樹脂
- 高性能熱塑性塑膠(ULTEM、PEKK)
- 金屬
- 鈦合金
- 鋁合金
- 不銹鋼
- 鎳基高溫合金
- 貴金屬
- 陶瓷
- 氧化鋁
- 氧化鋯
- 碳化矽
- 複合材料和其他新興材料
- 聚合物
- 最終用戶
- 航太/國防
- 車
- 醫療保健
- 醫療器材
- 牙科
- 工業機械
- 日常必需品
- 建造
- 教育/研究
- 其他最終用戶
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 東南亞
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- BASF 3D Printing Solutions GmbH
- Evonik Industries AG
- Arkema SA
- Sandvik AB
- Hoganas AB
- Stratasys Ltd.
- 3D Systems Corporation
- General Electric Company(GE Additive)
- EOS GmbH
- Materialise NV
- Desktop Metal Inc.
- Markforged Holding Corporation
- Carpenter Technology Corporation
- Heraeus Holding GmbH
- GKN Powder Metallurgy Holdings GmbH
- HP Inc.
- Prodways Group SA
- SLM Solutions Group AG
- Henkel AG and Co. KGaA
- DSM-Covestro Additive Manufacturing(Covestro AG)
- ExOne Company(Desktop Metal)
第7章 市場機會與未來展望
According to Mordor Intelligence, the additive manufacturing and materials market size is expected to grow from USD 95.27 billion in 2025 to USD 110.63 billion in 2026 and is forecast to reach USD 233.58 billion by 2031 at 16.12% CAGR over 2026-2031.
This report is Segmented by Technology (Polymer-Based, Metal-Based, Ceramic-Based, and More), Material Type (Polymers, Metals, Ceramics, Composite, and More), End User (Aerospace and Defense, Automotive, Healthcare, Industrial Machinery, Consumer Products, Construction, Education and Research, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Additive Manufacturing And Materials Market Trends and Insights
Demand for lightweight components in automotive and aerospace
Aerospace OEMs condense multi-part assemblies into single printed geometries to trim aircraft weight and maintenance. GE Aviation's printed fuel nozzle replaces twenty components and saves carriers USD 1.6 million in lifetime operating costs per aircraft.Boeing integrates titanium lattice brackets on the 787 that cut part cost by USD 2-3 million while meeting structural standards. Automotive firms replicate this consolidation in battery housings and brake systems to extend electric-vehicle range. Topology-optimization software unlocks organic shapes unattainable with machining, giving early adopters a performance edge. ASTM F2792 definitions standardize terminology and testing, helping certifiers approve flight-critical parts faster.
Rapid adoption of patient-specific healthcare implants
Powder-bed fusion enables porous titanium implants that match individual anatomy, improving osseointegration and cutting failure rates. Stryker has produced over 2 million such devices, proving the scalability of hospital-grade additive workflows.The U.S. FDA's point-of-care guidance lets certified hospitals print surgical guides onsite, reducing lead times and inventory costs. Distributed production shifts value from centralized factories to clinical settings, shrinking logistics footprints. Premium demand pushes cobalt-chrome and titanium powder suppliers to scale atomization capacity despite tight aerospace allocation.
High cost of high-performance metals and polymers
PEEK, PEKK, and aerospace-grade titanium powders trade at premiums that smaller job shops struggle to absorb. Limited atomizer capacity and energy-intensive plasma processes elevate raw-material costs just as buyers push for volume pricing. Suppliers face a squeeze between customers requesting discounts and investors demanding R&D spending, delaying next-generation material rollouts. Automotive and consumer sectors therefore confine purchases to prototypes or high-margin components until cost curves fall.
Other drivers and restraints analyzed in the detailed report include:
- Government funding and standards harmonization
- Supply-chain volatility in critical alloying elements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Directed Energy Deposition posts a 16.98% CAGR, underpinned by aerospace engine repair where meter-scale parts eclipse powder-bed build volumes. This segment benefits from wire feedstock that costs 30-50% less than powder and recoups material unused in other systems. Fused Deposition Modeling, however, retains 39.68% additive manufacturing and materials market share due to its ubiquity in education, design, and low-stress industrial fixtures. Hybrid CNC-additive platforms merge laser cladding with five-axis milling to meet tolerance and surface roughness targets in a single setup.
Powder Bed Fusion remains the benchmark for lattice-rich implants and rocket turbopump components requiring sub-80 µm layer heights. Binder Jetting evolves for steel pump housings and sand casting molds, offering throughput advantages when sintering bottlenecks are solved. Emerging microwave volumetric systems promise order-of-magnitude speed gains, foreshadowing a future where build time no longer dictates unit economics.
Complete Report Scope:
- By Technology
- Polymer-based Technologies
- Fused Deposition Modeling (FDM)
- Stereolithography (SLA)
- Digital Light Processing (DLP)
- Material Jetting (PolyJet)
- Binder Jetting - Polymers
- Metal-based Technologies
- Powder Bed Fusion (SLM, EBM)
- Directed Energy Deposition
- Ceramic-based Technologies
- Ceramic SLA
- Ceramic Binder Jetting
- Other Technologies
- Polymer-based Technologies
- By Material Type
- Polymers
- Commodity Thermoplastics (ABS, PLA)
- Engineering Plastics (PA, PEEK)
- Photopolymer Resins
- High-performance Thermoplastics (ULTEM, PEKK)
- Metals
- Titanium Alloys
- Aluminum Alloys
- Stainless Steels
- Nickel Super-alloys
- Precious Metals
- Ceramics
- Alumina
- Zirconia
- Silicon Carbide
- Composite and Other Emerging Material Feedstocks
- Polymers
- By End User
- Aerospace and Defense
- Automotive
- Healthcare
- Medical Devices
- Dental
- Industrial Machinery
- Consumer Products
- Construction
- Education and Research
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America commands 36.45% additive manufacturing and materials market size in 2025, supported by defense budgets, NASA deep-space initiatives, and a mature supplier ecosystem. Federal tax incentives and Section 174 R&D expensing rules reward capital investment in new production lines. FDA 510(k) guidance for 3D-printed implants accelerates time-to-market for device OEMs, reinforcing domestic powder consumption.
Asia Pacific is the fastest-growing region at a 16.55% CAGR as China funds domestic printer champions to lessen dependence on imported engine parts. Singapore's National Additive Manufacturing cluster certifies aerospace alloys and trains technicians, turning the island into a regional export hub.India's Production-Linked Incentive program subsidizes metal-printer purchases for automotive and energy verticals, while Australia's Cooperative Research Centre advances titanium powder atomization from local ore.
Europe focuses on sustainability; the EU's Fit-for-55 package spurs OEMs to print lightweight brackets that reduce vehicle emissions. The European Space Agency demonstrates the first stainless-steel part fabricated aboard the ISS, validating micro-gravity printing for lunar infrastructure. German carmakers co-develop aluminum-silicon alloys that weld seamlessly without hot-crack defects, setting a benchmark for crash-relevant applications.
- BASF 3D Printing Solutions GmbH
- Evonik Industries AG
- Arkema S.A.
- Sandvik AB
- Hoganas AB
- Stratasys Ltd.
- 3D Systems Corporation
- General Electric Company (GE Additive)
- EOS GmbH
- Materialise NV
- Desktop Metal Inc.
- Markforged Holding Corporation
- Carpenter Technology Corporation
- Heraeus Holding GmbH
- GKN Powder Metallurgy Holdings GmbH
- HP Inc.
- Prodways Group SA
- SLM Solutions Group AG
- Henkel AG and Co. KGaA
- DSM-Covestro Additive Manufacturing (Covestro AG)
- ExOne Company (Desktop Metal)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for lightweight components in automotive and aerospace
- 4.2.2 Rapid adoption of patient-specific healthcare implants
- 4.2.3 Falling polymer and metal powder prices
- 4.2.4 Government funding and standards harmonisation
- 4.2.5 Circular-economy push for recycled feedstocks
- 4.2.6 On-site micro-production for space and remote missions
- 4.3 Market Restraints
- 4.3.1 High cost of high-performance metals and polymers
- 4.3.2 Intellectual-property protection concerns
- 4.3.3 Stringent EHS rules for nano-powder handling
- 4.3.4 Supply-chain volatility in critical alloying elements
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Polymer-based Technologies
- 5.1.1.1 Fused Deposition Modeling (FDM)
- 5.1.1.2 Stereolithography (SLA)
- 5.1.1.3 Digital Light Processing (DLP)
- 5.1.1.4 Material Jetting (PolyJet)
- 5.1.1.5 Binder Jetting - Polymers
- 5.1.2 Metal-based Technologies
- 5.1.2.1 Powder Bed Fusion (SLM, EBM)
- 5.1.2.2 Directed Energy Deposition
- 5.1.3 Ceramic-based Technologies
- 5.1.3.1 Ceramic SLA
- 5.1.3.2 Ceramic Binder Jetting
- 5.1.4 Other Technologies
- 5.1.1 Polymer-based Technologies
- 5.2 By Material Type
- 5.2.1 Polymers
- 5.2.1.1 Commodity Thermoplastics (ABS, PLA)
- 5.2.1.2 Engineering Plastics (PA, PEEK)
- 5.2.1.3 Photopolymer Resins
- 5.2.1.4 High-performance Thermoplastics (ULTEM, PEKK)
- 5.2.2 Metals
- 5.2.2.1 Titanium Alloys
- 5.2.2.2 Aluminum Alloys
- 5.2.2.3 Stainless Steels
- 5.2.2.4 Nickel Super-alloys
- 5.2.2.5 Precious Metals
- 5.2.3 Ceramics
- 5.2.3.1 Alumina
- 5.2.3.2 Zirconia
- 5.2.3.3 Silicon Carbide
- 5.2.4 Composite and Other Emerging Material Feedstocks
- 5.2.1 Polymers
- 5.3 By End User
- 5.3.1 Aerospace and Defense
- 5.3.2 Automotive
- 5.3.3 Healthcare
- 5.3.3.1 Medical Devices
- 5.3.3.2 Dental
- 5.3.4 Industrial Machinery
- 5.3.5 Consumer Products
- 5.3.6 Construction
- 5.3.7 Education and Research
- 5.3.8 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia and New Zealand
- 5.4.4.6 Southeast Asia
- 5.4.4.7 Rest of Asia Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Egypt
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BASF 3D Printing Solutions GmbH
- 6.4.2 Evonik Industries AG
- 6.4.3 Arkema S.A.
- 6.4.4 Sandvik AB
- 6.4.5 Hoganas AB
- 6.4.6 Stratasys Ltd.
- 6.4.7 3D Systems Corporation
- 6.4.8 General Electric Company (GE Additive)
- 6.4.9 EOS GmbH
- 6.4.10 Materialise NV
- 6.4.11 Desktop Metal Inc.
- 6.4.12 Markforged Holding Corporation
- 6.4.13 Carpenter Technology Corporation
- 6.4.14 Heraeus Holding GmbH
- 6.4.15 GKN Powder Metallurgy Holdings GmbH
- 6.4.16 HP Inc.
- 6.4.17 Prodways Group SA
- 6.4.18 SLM Solutions Group AG
- 6.4.19 Henkel AG and Co. KGaA
- 6.4.20 DSM-Covestro Additive Manufacturing (Covestro AG)
- 6.4.21 ExOne Company (Desktop Metal)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 高速大尺寸切割系統市場:全球市場預測,2026-2032年
 2026-2030年全球積層製造市場
 2034 年積層製造材料市場預測-按材料類型、材料形式、與製造技術的兼容性、最終用戶和地區進行全球分析。
 積層製造設備市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測
 雷射積層製造監測市場-全球及區域分析:按應用、產品與國家分類-分析與預測,2026-2035年混合積層製造設備市場:全球市場預測,2026-2032年全球積層製造設備市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 全球積層製造後後處理設備市場:市場機會、成長要素、產業趨勢分析及2026-2035年預測銅積層製造市場:依製造流程、材料類型、服務類型、應用和最終用途產業分類-2026-2032年全球市場預測
 2026年全球混合積層製造設備市場報告