


 |
市場調查報告書
商品編碼
2121502
壓鑄:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Die Casting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
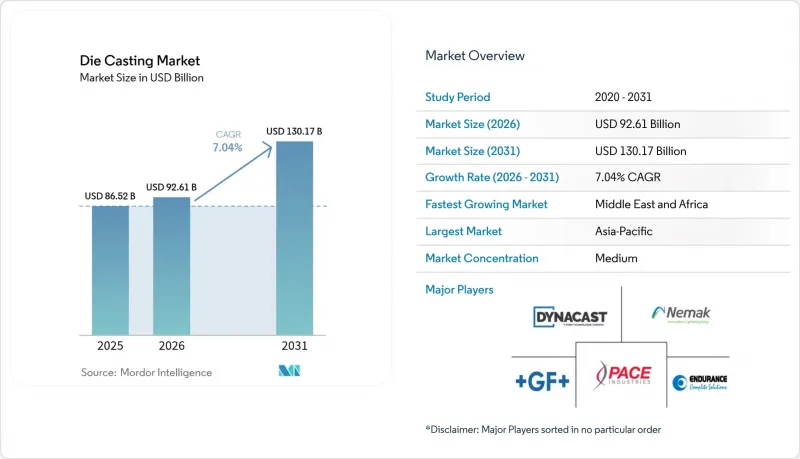
2025年壓鑄市場價值為865.2億美元,預計到2031年將達到1301.7億美元,而2026年為926.1億美元,預測期(2026-2031年)複合年成長率為7.04%。
本報告按應用領域(汽車、電氣和電子設備等)、製程(壓鑄、真空壓鑄等)、原料(鋁、鎂等)、鑄造機夾緊力(低於4000 kN、4001–10000 kN、其他)和地區(北美、南美、其他)進行細分。市場預測以美元計價。
全球壓鑄市場趨勢及洞察
推動從內燃機汽車到電動車的結構部件輕量化
儘管電池式電動車(BEV) 透過減少零件數量來簡化設計,但電池外殼、馬達框架和整合底盤等關鍵結構部件仍需要更大尺寸的一體式壓鑄件。特斯拉用於後底盤的巨型壓鑄件就是一個典型的例子,它整合了多個沖壓成型的零件。這表明,無論總產量如何波動,壓鑄製程在每輛車中的戰略重要性和價值都在不斷提升。研究表明,結構巨型壓鑄件可以將整車重量減輕 10% 至 15%,降低組裝複雜性,同時顯著提高續航里程。
用於 Gigapress 的近淨成形白車身壓力壓鑄
巨型壓機(Gigapress)這種龐大的機器,使得以往需要多個焊接零件才能製造的結構,現在可以一次生產出來。傳統汽車製造商正將這些壓機整合到其新型電動車平台中,而小規模的鑄造廠則面臨初始廢品率高、模具調整成本高成本挑戰。同時,先進的生產線正在縮短生產週期,從而顯著降低資本投資成本,壓鑄行業也正在整合為數量更少但規模更大的生產單位。
從2026年起,中國實施出口限制將帶來鎂供應風險。
中國仍然是鎂的主要供應國。然而,其近期訂定的出口許可措施表明,供應管控正在收緊。這些舉措可能會擾亂下游鑄造合約。西方冶煉廠需要數年才能投入運作,目前正面臨價格波動的困擾,這使得汽車平台的長期規劃變得更加複雜。那些利用鎂比鋁更輕的重量優勢的汽車和航太項目,如今面臨著重新設計零件還是囤積材料的艱難抉擇。
細分市場分析
預計到2025年,汽車應用將佔壓鑄件銷售額的61.73%,並在2031年之前以8.02%的複合年成長率成長,其中電動車結構件的應用將抵消內燃機(ICE)的下滑。電池外殼、馬達外殼和底盤鑄件的壓鑄市場規模預計將在預測期結束時顯著擴大。汽車製造商正在將數十個沖壓件整合到少數幾個大型鑄件中,這推動了籌資策略的轉變。汽車製造商現在優先考慮精通巨型壓鑄製程的供應商,尤其是那些推出週期完美的供應商。除了汽車產業外,可再生能源和電信等產業的需求也在穩定成長。
同時,航太產業對鈦合金和高強度鋁合金作為下一代機身材料的興趣日益濃厚。這一行業趨勢正推動韌性合金和真空輔助填充技術的研究與開發不斷加強,以滿足日益嚴格的碰撞安全標準。先前主要專注於引擎零件的一級供應商,如今正在調整戰略重心。他們正在改造熔爐,並安裝大規模鑄造單元,以專注於結構件和電池托盤的生產。這些趨勢提高了中小鑄造廠的進入門檻,整個產業正朝著一體化中心發展,將加工和組裝無縫地整合在原始設備製造商(OEM)的車身工廠附近。
儘管高壓鑄造在2025年仍將佔銷售額的55.02%,但真空鑄造預計將以8.93%的複合年成長率成長,因為電動車結構件對熱處理和可焊接零件的需求日益成長,而安全性至關重要。孔隙率降低60-80%將使汽車製造商能夠對鋁製零件進行T6熱處理,而無需擔心爆裂風險,並透過雷射焊接將其整合到多材料框架中。這項技術將使每公斤售價提高高達30%,同時即使合金成本上漲,也能維持較高的利潤率。因此,壓鑄市場正在出現工廠增設真空室或將冷室改造為混合配置的情況。
從長遠來看,擠壓鑄造和半固體鑄造製程能夠滿足航太等特定應用領域以及重型卡車轉向節等需要鍛造級微觀結構的應用需求。然而,這些製程的周期仍然較長,因此,在大批量生產的行業中,壓力鑄造和真空鑄造,結合增強的模內冷卻和製程監控,仍然是首選製程。
區域分析
到2025年,亞太地區將佔全球銷售額的56.21%,這主要得益於中國龐大的汽車、家電和電子叢集。數十年來累積的專業知識、豐富的廢鋁供應以及垂直整合的模具鋼生態系統,確保了該地區持續的高成本競爭力。韓國和日本正致力於控制系統創新,而印度則利用與生產掛鉤的獎勵來資金籌措新的輕量化零件生產線。隨著整車製造商(OEM)採購管道的多元化,東南亞正在擴大其在低複雜度零件和預生產能力方面的佔有率,從而增強其在東協壓鑄市場的影響力。
中東和非洲地區是成長最快的地區,年複合成長率達8.42%。波灣合作理事會(GCC)成員國正利用「2030願景」計畫的資金在國內生產太陽能逆變器、風力渦輪機外殼和電動車充電器。像NEOM這樣的大型企劃正在推動對能夠鑄造鋁製外牆節點和結構連接件的大噸位壓平機的需求。土耳其的汽車出口和埃及的工業園區政策進一步促進了該地區的訂單,但在冶煉廠擴大規模之前,上游鋁錠供應仍依賴進口。
在北美和歐洲,成長主要由技術變革驅動,而非工廠數量的增加。美國的稅額扣抵鼓勵採購國產電池和動力傳動系統,促使原始設備製造商(OEM)在俄亥俄州、阿拉巴馬州和安大略省的組裝廠附近建立大型鑄造廠。歐洲的碳邊境調節機制(CBAM)提升了使用可再生能源運作的再生鋁熔爐的區域鑄造廠的競爭力。這兩個地區都在透過強制淘汰全氟烷基和多氟烷基物質(PFAS)和進行生命週期碳審計、加快設備現代化改造以及採用數位化可追溯性模組,進一步擴大壓鑄市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 推動從內燃機汽車到電動車的結構部件輕量化
- 用於 Gigapress 的近淨成形高壓鑄白車身應用。
- 實現零缺陷「一次成型」品質的套模感測器。
- 循環經濟中強制性的鋁回收利用正在推動對再生高壓壓鑄件的需求。
- 利用鑄造廠現場可再生能源進行能源價格對沖
- 3D 砂型列印核心零件實現了電動車的複雜形狀。
- 市場限制因素
- 從2026年起,中國實施出口限制將帶來鎂供應風險。
- 更嚴格的潤滑油中 PFAS 排放標準
- Gigapress 的 OEM內部資源正在降低一級製造商的產量。
- 歐盟的碳關稅提高了高能耗鑄造製程的成本基礎。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 透過使用
- 車
- 電氣和電子設備
- 工業機械
- 航太/國防
- 電器產品
- 其他
- 透過流程
- 壓力壓鑄
- 真空壓鑄
- 擠壓壓鑄
- 重力鑄造
- 按成分
- 鋁
- 鎂
- 鋅
- 銅
- 其他(鉛、錫合金)
- 鑄造機夾緊力
- 4,000 kN 或更小
- 4,001~10,000 kN
- 10,000 kN 或以上
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 泰國
- 印尼
- 馬來西亞
- 澳洲
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Form Technologies Inc.(Dynacast)
- Nemak SAB de CV
- Endurance Technologies Limited
- Sundaram Clayton Ltd
- Shiloh Industries, inc.
- Georg Fischer Ltd
- Gibbs Die Casting Corporation
- Bocar Group
- Engtek Group
- Rheinmetall AG
- Rockman Industries Limited
- Ryobi Die Casting
- Linamar Corporation
- Meridian Lightweight Technologies Inc.
- Sandhar Group
- Alcoa Corporation
- Pace Industries Inc.
- CIE Automotive
- China Hongqiao Group Limited
- Consolidated Metco, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the die casting market size was valued at USD 86.52 billion in 2025 and estimated to grow from USD 92.61 billion in 2026 to reach USD 130.17 billion by 2031, at a CAGR of 7.04% during the forecast period (2026-2031).
This report is Segmented by Application (Automotive, Electrical and Electronics, and More), Process (Pressure Die Casting, Vacuum Die Casting, and More), Raw Material (Aluminum, Magnesium, and More), Casting-Machine Clamping Force (<=4, 000 KN, 4, 001-10, 000 KN, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Die Casting Market Trends and Insights
ICE-to-EV Structural-Parts Lightweighting Push
Battery-electric vehicles streamline their design with fewer components, yet they demand larger, integrated castings for essential structures such as battery housings, motor frames, and unified chassis sections. A prime example is Tesla's rear underbody megacasting, which consolidates several stamped parts. This underscores the rising strategic significance and value of die casting in each vehicle, regardless of fluctuations in overall production volumes. Studies indicate structural megacasting can reduce curb weight by 10-15%, bringing critical range benefits while lowering assembly complexity .
Near-Net-Shape Pressure-Die-Casting for Giga-Press Body-in-White
Ultra-large giga-presses now create single-piece structures, a feat that once demanded multiple welded components. While traditional automakers are integrating these presses into their new electric vehicle platforms, smaller foundries grapple with challenges like high initial scrap rates and expensive die adjustments. Meanwhile, advanced equipment lines are achieving quicker cycle times, a move that mitigates hefty capital costs and pushes the die-casting industry towards consolidating into fewer, yet significantly larger, production cells.
Post-2026 Magnesium Supply Risk from China Export Controls
China continues to lead as the primary source of magnesium. However, recent export licensing measures from the country hint at tighter supply controls. Such moves could potentially disrupt downstream casting contracts. Western smelters, taking years to ramp up, are grappling with price volatility, complicating long-term vehicle platform planning. Programs in the automotive and aerospace sectors, which have relied on magnesium's lightweight benefits over aluminum, now confront difficult decisions: redesigning components or stockpiling the material.
Other drivers and restraints analyzed in the detailed report include:
- In-Mold Sensors Enabling Zero-Defect "First-Shot" Quality
- Circular-Economy Aluminum-Recycling Mandates Spur Secondary HPDC Demand
- Tightening PFAS Emissions Norms on Lubricants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automotive applications contributed 61.73% of 2025 revenues and will deliver an 8.02% CAGR to 2031, illustrating how EV structural content offsets ICE decline. The die casting market size for battery enclosures, motor housings, and under-body castings will grow significantly by the end of the forecast period. Automakers are consolidating dozens of stamped components into just a few large castings, leading to a shift in sourcing strategies. They're now favoring suppliers adept at giga-press operations, especially those with flawless startup cycles. Beyond the automotive realm, sectors like renewable energy and telecom are witnessing a steady uptick in demand.
Meanwhile, the aerospace industry is showing heightened interest in titanium and high-strength aluminum, eyeing them for next-generation airframes. This industry-wide transition is spurring intensified R&D efforts into ductile alloys and vacuum-assisted filling, all in a bid to meet stringent crash safety standards. Tier-1 suppliers, previously centered on engine parts, are now pivoting. They're retrofitting furnaces and setting up massive casting cells, focusing on structural components and battery trays. Such trends are elevating entry barriers for smaller foundries and nudging the industry towards integrated hubs, seamlessly blending machining and assembly close to OEM body shops.
While pressure casting still owns 55.02% of 2025 billings, vacuum casting will clock a 8.93% CAGR as safety-critical EV structures require heat-treatable, weldable parts. When pore content falls 60-80%, automakers can T6-treat aluminum parts without blow-out risk and laser-weld them into multi-material frames. That capability lifts price realizations by up to 30% per kilogram, keeping margin potential high even where alloy cost rises. Consequently, the die casting market sees plants adding vacuum chambers or converting cold-chamber cells to hybrid configurations.
Longer term, squeeze casting and semi-solid processes address niche aerospace and heavy-truck steering knuckles that need forged-like microstructures. Yet their cycle times remain slower, so high-volume industries still favor pressure or vacuum options supplemented by in-die cooling and intensified process monitoring.
Complete Report Scope:
- By Application
- Automotive
- Electrical and Electronics
- Industrial Machinery
- Aerospace and Defense
- Consumer Appliances
- Others
- By Process
- Pressure Die Casting
- Vacuum Die Casting
- Squeeze Die Casting
- Gravity Die Casting
- By Raw Material
- Aluminum
- Magnesium
- Zinc
- Copper
- Others (Lead, Tin Alloys)
- By Casting-Machine Clamping Force
- <=4,000 kN
- 4,001-10,000 kN
- Above 10,000 kN
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Indonesia
- Malaysia
- Australia
- Rest of Asia-Pacific
- Middle-East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific generated 56.21% of global sales in 2025, anchored by China's vast auto, appliance and electronics clusters. Decades of cumulative know-how, high scrap-aluminum availability, and vertically integrated tool-steel ecosystems keep cost positions sharp. Korea and Japan contribute control-system innovation, while India rides production-linked incentives that fund new lightweight-component lines. As OEMs diversify sourcing, Southeast Asia gains share for low-complexity parts and back-up capacity, broadening the die casting market footprint across ASEAN.
The Middle East & Africa region is the fastest riser at 8.42% CAGR. Gulf Cooperation Council states use Vision 2030 funds to manufacture solar inverters, wind housings, and EV chargers domestically. Megaprojects like NEOM draw demand for high-tonnage presses able to cast aluminum facade nodes and structural connectors. Turkey's auto exports and Egypt's industrial-park policies further energize regional orders, though upstream ingot supply relies on imports until smelters scale.
North America and Europe grow chiefly through technology shifts rather than plant count. United States tax credits favor domestic battery and drivetrain sourcing, causing OEMs to localize megacasting next to assembly plants in Ohio, Alabama, and Ontario. Europe's Carbon Border Adjustment Mechanism boosts competitive standing for regional shops running recycled aluminum furnaces on renewable power. Both regions further the die casting market by enforcing PFAS phase-outs and lifecycle carbon audits, spurring capital upgrades and digital traceability modules.
- Form Technologies Inc. (Dynacast)
- Nemak S.A.B. de C.V.
- Endurance Technologies Limited
- Sundaram Clayton Ltd
- Shiloh Industries, inc.
- Georg Fischer Ltd
- Gibbs Die Casting Corporation
- Bocar Group
- Engtek Group
- Rheinmetall AG
- Rockman Industries Limited
- Ryobi Die Casting
- Linamar Corporation
- Meridian Lightweight Technologies Inc.
- Sandhar Group
- Alcoa Corporation
- Pace Industries Inc.
- CIE Automotive
- China Hongqiao Group Limited
- Consolidated Metco, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 ICE-to-EV Structural-Parts Lightweighting Push
- 4.2.2 Near-Net-Shape Pressure-Die-Casting for Giga-Press Body-in-White
- 4.2.3 In-Mold Sensors Enabling Zero-Defect "First-Shot" Quality
- 4.2.4 Circular-Economy Aluminum-Recycling Mandates Spur Secondary HPDC Demand
- 4.2.5 Energy-Price Hedging via On-Site Renewables at Foundries
- 4.2.6 3D-Sand-Printed Cores Unlocking Complex EV Geometries
- 4.3 Market Restraints
- 4.3.1 Post-2026 Magnesium Supply Risk from China Export Controls
- 4.3.2 Tightening PFAS Emissions Norms on Lubricants
- 4.3.3 OEM Insourcing with Giga-Pressing Reducing Tier-1 Volumes
- 4.3.4 EU Carbon-Border Taxes Raising Cost Base for Energy-Intensive Foundries
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Application
- 5.1.1 Automotive
- 5.1.2 Electrical and Electronics
- 5.1.3 Industrial Machinery
- 5.1.4 Aerospace and Defense
- 5.1.5 Consumer Appliances
- 5.1.6 Others
- 5.2 By Process
- 5.2.1 Pressure Die Casting
- 5.2.2 Vacuum Die Casting
- 5.2.3 Squeeze Die Casting
- 5.2.4 Gravity Die Casting
- 5.3 By Raw Material
- 5.3.1 Aluminum
- 5.3.2 Magnesium
- 5.3.3 Zinc
- 5.3.4 Copper
- 5.3.5 Others (Lead, Tin Alloys)
- 5.4 By Casting-Machine Clamping Force
- 5.4.1 <=4,000 kN
- 5.4.2 4,001-10,000 kN
- 5.4.3 Above 10,000 kN
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Thailand
- 5.5.4.6 Indonesia
- 5.5.4.7 Malaysia
- 5.5.4.8 Australia
- 5.5.4.9 Rest of Asia-Pacific
- 5.5.5 Middle-East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Form Technologies Inc. (Dynacast)
- 6.4.2 Nemak S.A.B. de C.V.
- 6.4.3 Endurance Technologies Limited
- 6.4.4 Sundaram Clayton Ltd
- 6.4.5 Shiloh Industries, inc.
- 6.4.6 Georg Fischer Ltd
- 6.4.7 Gibbs Die Casting Corporation
- 6.4.8 Bocar Group
- 6.4.9 Engtek Group
- 6.4.10 Rheinmetall AG
- 6.4.11 Rockman Industries Limited
- 6.4.12 Ryobi Die Casting
- 6.4.13 Linamar Corporation
- 6.4.14 Meridian Lightweight Technologies Inc.
- 6.4.15 Sandhar Group
- 6.4.16 Alcoa Corporation
- 6.4.17 Pace Industries Inc.
- 6.4.18 CIE Automotive
- 6.4.19 China Hongqiao Group Limited
- 6.4.20 Consolidated Metco, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 2026-2030年全球鋅壓鑄微型零件市場
 壓鑄機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)重力鑄造:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 壓鑄和鍛造市場:全球市場預測,2026-2032年壓鑄市場:全球市場預測,2026-2032年壓鑄機械市場-2026-2032年全球市場預測鋁零件重力鑄造市場-2026-2032年全球市場預測工業鑄造市場:按類型、材料、應用和最終用戶產業分類-2026-2032年全球市場預測真空鋁鑄造市場:依製程類型、合金類型、產品類型及應用分類,2026-2032年全球預測燃燒室鑄件市場:按部件類型、鑄造工藝、材料類型、鑄造工藝技術和最終用途行業分類,全球預測,2026-2032年