


 |
市場調查報告書
商品編碼
2121451
聯網汽車設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)Connected Car Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
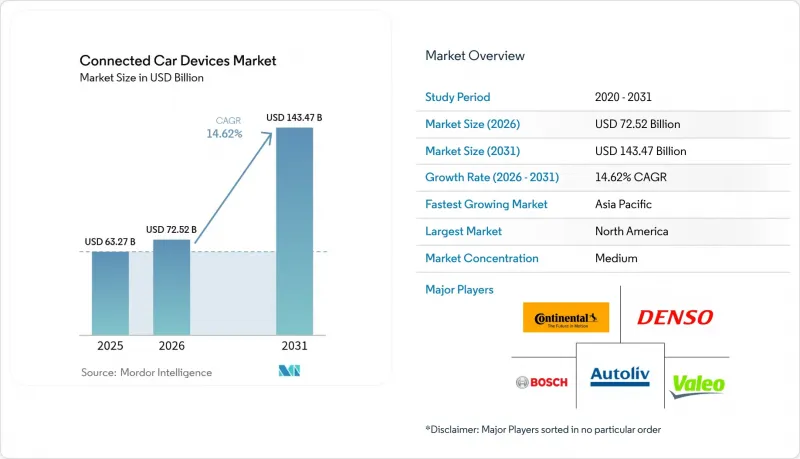
據估計,到 2026 年,聯網汽車設備市場價值將達到 725.2 億美元,高於 2025 年的 632.7 億美元,預計到 2031 年將達到 1,434.7 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 14.62%。
本報告按最終用戶類型(OEM 和售後市場)、通訊類型(V2V、V2I 等)、產品類型(駕駛輔助系統 (DAS)、車載資訊系統等)、連接技術(嵌入式、整合式等)、車輛驅動系統(內燃機和電動)以及地區進行細分。市場預測以美元計價。
全球聯網汽車設備市場趨勢與洞察
5G的快速部署以及電信業者與OEM廠商之間的合作
預計到2027年,汽車5G連接服務的收入將呈指數級成長。思科和TELUS已在其自動化平台上為超過150萬輛支援5G的汽車提供服務,將對自動駕駛至關重要的延遲降低到接近即時的水平。如今,透過夥伴關係,整合了連接、邊緣運算和開發者工具的解決方案正在交付,使原始設備製造商(OEM)能夠更快地推出新服務。隨著營運商的角色從單純的頻寬供應商轉變為策略技術合作夥伴,這些合作正在改變供應商產業的格局。由此產生的服務平台將支援高級資訊娛樂、遠端診斷和高清地圖,有助於提高每位用戶平均收入(ARPU)。
對電子呼叫和ADAS的強制性監管
美國國家公路交通安全管理局 (NHTSA) 強制要求所有輕型車輛在 2029 年 9 月前配備行人偵測功能的自動緊急煞車系統,預計每年合規成本為 3.54 億美元,終身收益超過 58.2 億美元。在歐洲,通用安全法規強制要求車輛配備 e-Call 緊急呼叫系統和一系列駕駛輔助功能。在中國,北京已安裝超過 7,000 個 5G-A 基地台,以擴展車輛、道路和雲端互聯的示範計畫。這些法規消除了部署計畫的不確定性,並鼓勵原始設備製造商 (OEM) 將連網感測器作為標準配置。供應商將受益於可預測的產量,而消費者將享受到降低事故率的通用安全功能。
網路安全漏洞和召回
「Pwn2Own Automotive 2024」競賽凸顯了遠端攻擊的易如反掌,其中一項針對Alpine Halo 9車載資訊娛樂系統的零點擊攻擊被發現,其成功率高達96%。 2023年,與軟體相關的召回事件影響了超過3000萬輛汽車,而美國國家標準與技術研究院(NIST)註冊的CVE-2023-6248漏洞則允許攻擊者完全控制常見的車載資訊服務閘道。隨著汽車逐漸成為“移動資料中心”,攻擊面不斷擴大,售後修補成本和聲譽損失也隨之增加。監管機構要求“安全設計”,強制供應商在硬體中整合信任根,實施安全的空中下載(OTA)更新框架,並進行持續的滲透測試。
細分市場分析
到2025年,汽車製造商(OEM)將佔據聯網汽車設備市場62.68%的佔有率。這是因為原廠安裝的硬體與車輛診斷、電源管理和保固系統深度整合。汽車製造商在組裝過程中組裝各種模組,以確保符合e-Call和ADAS的法規要求,簡化空中升級流程,並增強品牌對資料的控制。隨著對軟體定義架構的依賴性不斷增強,汽車製造商透過將連網功能與遠端功能啟動和預測性維護等產生收入服務相結合,鞏固了主導地位。
同時,隨著保險公司和車隊管理公司對現有車輛維修,售後市場供應商正以15.51%的複合年成長率快速擴張。即插即用的加密狗和有線黑盒子可提供即時使用數據,為基於行為模式的保費設定和資產追蹤提供基礎。哈曼的「即裝即用」升級套件就是一個典型的例子,它為需要快速安裝並與其他品牌相容的混合車隊提供客製化解決方案。儘管原始設備製造商(OEM)的主導地位依然穩固,但由價格敏感的私人車主和商業營運商驅動的平行售後市場,持續確保著聯網汽車設備市場的競爭多樣性。
預計到2025年,車對車(V2V)通訊將佔據聯網汽車設備市場39.05%的佔有率,因為它無需路邊設備即可提供碰撞預警。成熟的標準和經證實有效的安全改進正促使汽車製造商優先採用V2V技術,尤其是在旨在獲得五星級安全評級的量產車型中。在商用車隊中,由於前向碰撞警報可以減少停機時間和保險成本,因此改裝應用也正在迅速擴展。
預計到2031年,車地互聯(V2G)技術將以14.92%的複合年成長率成長,這主要得益於電力公司和汽車製造商之間的合作,旨在透過高比例可再生能源來穩定電網。雙向充電樁結合互聯技術,將使電動車能夠向電網輸送儲存的電力,從而為車主和電網營運商創造新的收入來源。車路互聯(V2I)和車行互聯(V2P)領域的成長與智慧城市的投資密切相關,而智慧城市的建設又依賴更廣泛的公共投資。未來,整合化的V2X平台將融合所有交通方式,但隨著生態系統的成熟,車路互聯(V2V)仍將是其基礎。
區域分析
到2025年,北美將佔據聯網汽車設備市場38.26%的佔有率。這一成長主要得益於聯邦政府根據《基礎設施投資與就業法案》提供的資金支持,以及消費者對配備高級駕駛輔助系統(ADAS)、高清資訊娛樂系統和5G熱點的高階SUV的需求。美國運輸部和5G汽車協會正在進行的試點計畫增強了人們對車聯網(C-V2X)技術的信心,而嚴格的網路安全和隱私法規也正在影響採購規範。加拿大和墨西哥受益於一體化的供應鏈,使得區域內的OEM工廠能夠實現聯網模組和軟體堆疊的標準化。這些因素共同促成了北美地區健康的更換週期和售後服務訂閱模式。
預計到2031年,亞太地區將以15.02%的複合年成長率實現最高成長。中國的「車路雲」計畫正在推動公共和私人投資,光是在北京就已安裝了超過7,000個5G-A基地台,用於智慧運輸。國內品牌正在將互聯功能融入產品,以在競爭激烈的電動車市場中脫穎而出,而區域供應商則為摩托車和微型車提供成本最佳化的車載資訊服務解決方案。日本和韓國正利用其半導體製造專長和早期5G部署經驗,測試下一代C-V2X側鏈功能。由於更嚴格的安全標準和精通智慧型手機、需要始終在線資訊娛樂的消費者,印度正在成為大規模的市場機遇,但由於價格敏感性,有線解決方案仍然非常重要。
在歐洲,在強制使用e-Call和通用安全法規(GSR)等統一法規的推動下,互聯汽車的發展勢頭穩步增強。德國、英國和法國引領這一趨勢,豪華汽車品牌已將互聯功能作為高階車型的標準配置,中端品牌也紛紛效仿。在提高能源效率和減少碳排放目標的驅動下,將電動車充電與可再生能源發電相結合的車網互動(V2G)試點計畫日益受到關注。嚴格的資料主權法律正在影響雲端託管的選擇,使歐洲供應商更具優勢。歐盟範圍內的網路安全認證標準正在製定中,預計將簡化跨境型式認證流程,並進一步刺激聯網汽車和設備市場的發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 5G的快速部署以及電信業者與OEM製造商之間的合作
- 美國、歐盟和中國關於電子呼叫和ADAS的強制法規
- OEM公司訂閱營收目標
- 邊緣人工智慧晶片可實現車載推理
- 按里程計費的保險正在推動售後遠端資訊處理市場的發展。
- 跨產業應用商店生態系統
- 市場限制因素
- 網路安全漏洞和召回
- 多頻段V2X模組的物料清單成本較高
- 出站資料雲端費用正在為OEM服務利潤率帶來壓力。
- 半導體供應鏈中的脆弱性
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按最終用戶類型
- OEM
- 售後市場
- 依溝通類型
- V2V
- V2I
- V2P
- V2N
- V2G
- 依產品類型
- 駕駛輔助系統(ADAS)
- 車載資訊系統
- 車載資訊娛樂系統
- 網路安全硬體
- 透過連接技術
- 嵌入式
- 融合的
- 有線連接
- DSRC
- C-V2X(4G/5G)
- 車輛驅動系統
- 內燃機車
- 電動車
- 電池式電動車
- 油電混合車
- 燃料電池汽車
- 插電式混合動力電動車
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Continental AG
- Robert Bosch GmbH
- Denso Corporation
- ZF Friedrichshafen AG
- Harman International
- Valeo SA
- Magna International
- Panasonic Corp.
- Visteon Corp.
- Autoliv Inc.
- Infineon Technologies AG
- Autotalks Ltd.
- Qualcomm Inc.
- NXP Semiconductors
- NVIDIA Corp.
- Sierra Wireless
- Cisco Systems
- Huawei Technologies
- AT&T
- Verizon
- Vodafone Group
- Ericsson
- LG Electronics
- Telit
第7章 市場機會與未來展望
According to Mordor Intelligence, connected car devices market size in 2026 is estimated at USD 72.52 billion, growing from 2025 value of USD 63.27 billion with 2031 projections showing USD 143.47 billion, growing at 14.62% CAGR over 2026-2031.
This report is Segmented by End-User Type (OEM and Aftermarket), Communication Type (V2V, V2I, and More), Product Type (Driver Assistance System (DAS), Telematics, and More), Connectivity Technology (Embedded, Integrated, and More), Vehicle Propulsion Type (IC Engine and Electric), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Connected Car Devices Market Trends and Insights
Rapid 5G Roll-Out and Carrier-OEM Partnerships
Automotive 5G connections are forecast to grow exponentially in enablement revenues by 2027. Cisco and TELUS already provision more than 1.5 million 5G vehicles on automated platforms, cutting latency to near-real-time levels critical for autonomous features. Partnerships now bundle connectivity, edge computing, and developer tools into unified offerings that let OEMs launch new services faster. These alliances change the supplier landscape because carriers shift from bandwidth providers to strategic technology partners. The resulting service platforms underpin premium infotainment, remote diagnostics, and high-definition maps, supporting higher average revenue per user.
Mandatory E-Call and ADAS Regulations
The National Highway Traffic Safety Administration requires automatic emergency braking with pedestrian detection on all light vehicles by September 2029, carrying USD 354 million in annual compliance costs and lifetime benefits topping USD 5.82 billion. Europe enforces e-Call and a suite of driver-assistance functions under the General Safety Regulation, while China scales vehicle-road-cloud pilots with more than 7,000 5G-A base stations in Beijing. These mandates remove uncertainty around timelines, prompting OEMs to integrate connected sensors as standard equipment. Suppliers benefit from predictable volumes, and consumers gain universal safety features that lower accident rates.
Cyber-Security Vulnerabilities and Recalls
The Pwn2Own Automotive 2024 contest exposed a zero-click exploit in Alpine's Halo9 infotainment unit with a 96% success rate, highlighting the ease of remote compromise. Software-related recalls affected over 30 million vehicles in 2023, and the NIST-listed CVE-2023-6248 flaw enables full device takeover of popular telematics gateways. As vehicles become rolling data centres, their attack surface expands, raising the cost of post-sale patches and reputational damage. Regulators demand security-by-design, pushing suppliers to embed hardware root-of-trust, secure over-the-air frameworks, and continuous penetration testing.
Other drivers and restraints analyzed in the detailed report include:
- Subscription-Based Revenue Targets
- Edge AI Chips for In-Vehicle Inferencing
- High BOM Cost of Multi-Band V2X Modules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
OEM installations captured 62.68% of the connected car devices market share in 2025 because factory-fitted hardware integrates deeply with vehicle diagnostics, power management, and warranty frameworks. Automakers embed modules during assembly to ensure compliance with e-Call and ADAS mandates, streamline over-the-air upgrades, and bolster brand control over data. Growing reliance on software-defined architectures cements this channel's leadership as OEMs link connectivity to revenue-generating services such as remote feature activation and predictive maintenance.
However, aftermarket providers are expanding quickly, with a 15.51% CAGR, as insurers and fleet managers retrofit legacy assets. Plug-and-play dongles and hardwired black boxes supply real-time usage data that underpins behaviour-based premiums and asset tracking. HARMAN's ready-upgrade kits exemplify solutions tailored for mixed fleets needing installation speed and cross-brand compatibility. While OEM control remains strong, price-sensitive owners and commercial operators continue to drive a parallel aftermarket, ensuring competitive variety within the connected car devices market.
Vehicle-to-vehicle links represented 39.05% of the connected car devices market revenue share in 2025 because they deliver collision warnings without requiring roadside units. Mature standards and demonstrated safety gains encourage OEMs to adopt V2V first, particularly in high-volume models aiming for five-star safety ratings. Retrofits also proliferate in commercial fleets where forward-collision alerts cut downtime and insurance costs.
Vehicle-to-grid capability is projected to post a 14.92% CAGR to 2031 as energy utilities partner with automakers to stabilise renewable-heavy grids. Bidirectional chargers paired with connectivity let electric cars feed stored power back to the network, creating new revenue for owners and grid operators. Growth in vehicle-to-infrastructure and vehicle-to-pedestrian segments follows smart-city spending, yet these depend on broader public investment. Over time, integrated V2X suites will blend all modes, but V2V will remain the cornerstone while ecosystems mature around it.
Complete Report Scope:
- By End-User Type
- OEM
- Aftermarket
- By Communication Type
- V2V
- V2I
- V2P
- V2N
- V2G
- By Product Type
- Driver Assistance System (ADAS)
- Telematics
- In-Car Infotainment
- Cyber-security Hardware
- By Connectivity Technology
- Embedded
- Integrated
- Tethered
- DSRC
- C-V2X (4G/5G)
- By Vehicle Propulsion Type
- Internal-Combustion Engine Vehicles
- Electric Vehicles
- Battery Electric Vehicle
- Hybrid Electric Vehicle
- Fuel-cell Electric Vehicle
- Plug-in Hybrid Electric Vehicle
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for 38.26% of the connected car devices market share in 2025. Uptake is driven by federal funding under the Infrastructure Investment and Jobs Act and consumer appetite for premium SUVs brimming with ADAS, high-definition infotainment, and 5G hotspots. Ongoing pilots with the U.S. Department of Transportation and the 5G Automotive Association boost confidence in C-V2X, while tight cybersecurity and privacy rules shape procurement specifications. Canada and Mexico benefit from integrated supply chains, enabling regional OEM plants to standardise connected modules and software stacks. These factors sustain healthy replacement cycles and after-sales subscriptions across North America.
Asia-Pacific is on track for the fastest 15.02% CAGR to 2031. China's vehicle-road-cloud blueprint anchors public and private spending, with Beijing alone hosting more than 7,000 5G-A base stations for intelligent mobility. Domestic brands embed connectivity to differentiate in a crowded electric-vehicle arena, while regional suppliers deliver cost-optimised telematics for two-wheelers and microcars. Japan and South Korea leverage chip-making prowess and early 5G roll-outs to test next-generation C-V2X sidelink features. India emerges as a high-volume opportunity as safety norms tighten and smartphone-savvy buyers demand always-on infotainment, though price sensitivity keeps tethered solutions relevant.
Europe maintains steady momentum under harmonised regulations such as mandatory e-Call and the General Safety Regulation. Germany, the United Kingdom, and France lead adoption as luxury marques bundle connectivity into premium trim lines, and mid-range brands follow suit. Energy-efficiency and carbon-reduction goals drive interest in vehicle-to-grid pilots that align EV charging with renewable output. Strict data sovereignty laws influence cloud-hosting choices, giving European-based providers an edge. Pan-EU standards for cybersecurity certification are under development, promising to streamline cross-border homologation and further stimulate the connected car devices market.
- Continental AG
- Robert Bosch GmbH
- Denso Corporation
- ZF Friedrichshafen AG
- Harman International
- Valeo SA
- Magna International
- Panasonic Corp.
- Visteon Corp.
- Autoliv Inc.
- Infineon Technologies AG
- Autotalks Ltd.
- Qualcomm Inc.
- NXP Semiconductors
- NVIDIA Corp.
- Sierra Wireless
- Cisco Systems
- Huawei Technologies
- AT&T
- Verizon
- Vodafone Group
- Ericsson
- LG Electronics
- Telit
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid 5G Roll-Out and Carrier-OEM Partnerships
- 4.2.2 Mandatory E-Call and ADAS Regulations in US, EU, CN
- 4.2.3 Subscription-Based Revenue Targets by OEMs
- 4.2.4 Edge AI Chips Enabling In-Vehicle Inferencing
- 4.2.5 Usage-Based-Insurance Driving Aftermarket Telematics
- 4.2.6 Cross-Industry App-Store Ecosystems
- 4.3 Market Restraints
- 4.3.1 Cyber-Security Vulnerabilities and Recalls
- 4.3.2 High BOM Cost of Multi-Band V2X Modules
- 4.3.3 Data-Cloud Egress Fees Eroding OEM Service Margins
- 4.3.4 Semiconductor Supply-Chain Fragility
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By End-User Type
- 5.1.1 OEM
- 5.1.2 Aftermarket
- 5.2 By Communication Type
- 5.2.1 V2V
- 5.2.2 V2I
- 5.2.3 V2P
- 5.2.4 V2N
- 5.2.5 V2G
- 5.3 By Product Type
- 5.3.1 Driver Assistance System (ADAS)
- 5.3.2 Telematics
- 5.3.3 In-Car Infotainment
- 5.3.4 Cyber-security Hardware
- 5.4 By Connectivity Technology
- 5.4.1 Embedded
- 5.4.2 Integrated
- 5.4.3 Tethered
- 5.4.4 DSRC
- 5.4.5 C-V2X (4G/5G)
- 5.5 By Vehicle Propulsion Type
- 5.5.1 Internal-Combustion Engine Vehicles
- 5.5.2 Electric Vehicles
- 5.5.2.1 Battery Electric Vehicle
- 5.5.2.2 Hybrid Electric Vehicle
- 5.5.2.3 Fuel-cell Electric Vehicle
- 5.5.2.4 Plug-in Hybrid Electric Vehicle
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Italy
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Continental AG
- 6.4.2 Robert Bosch GmbH
- 6.4.3 Denso Corporation
- 6.4.4 ZF Friedrichshafen AG
- 6.4.5 Harman International
- 6.4.6 Valeo SA
- 6.4.7 Magna International
- 6.4.8 Panasonic Corp.
- 6.4.9 Visteon Corp.
- 6.4.10 Autoliv Inc.
- 6.4.11 Infineon Technologies AG
- 6.4.12 Autotalks Ltd.
- 6.4.13 Qualcomm Inc.
- 6.4.14 NXP Semiconductors
- 6.4.15 NVIDIA Corp.
- 6.4.16 Sierra Wireless
- 6.4.17 Cisco Systems
- 6.4.18 Huawei Technologies
- 6.4.19 AT&T
- 6.4.20 Verizon
- 6.4.21 Vodafone Group
- 6.4.22 Ericsson
- 6.4.23 LG Electronics
- 6.4.24 Telit
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


