


 |
市場調查報告書
商品編碼
2121279
居家護理包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Home Care Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,家居護理包裝市場預計到 2026 年價值 391.8 億美元,高於 2025 年的 373 億美元,預計到 2031 年將達到 500.7 億美元。
預計從 2026 年到 2031 年,年複合成長率將達到 5.03%。
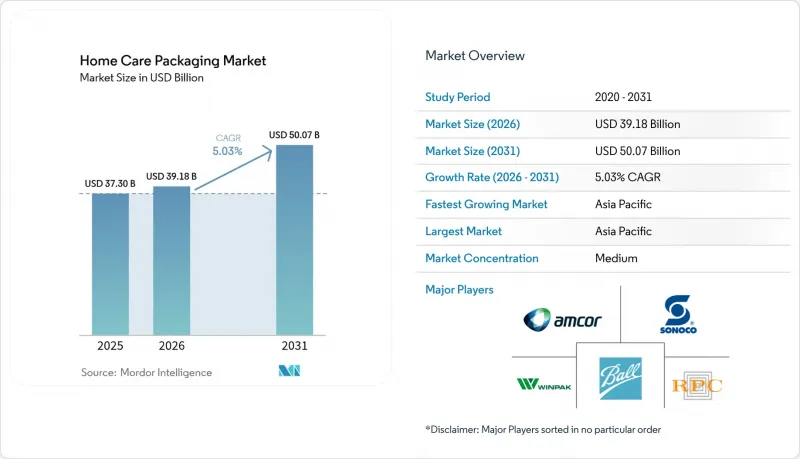
本報告按材料(塑膠、紙張等)、包裝類型(瓶裝和硬容器、軟袋等)、產品類型(清潔劑、殺蟲劑等)、形態(液體、粉末等)和地區細分產業。市場預測以價值(美元)表示。
全球居家護理包裝市場趨勢及洞察
品牌主導推動了優質化進程和 SKU 數量的增加。
消費者對高階清潔產品的需求正推動包裝創新,使其超越單純的功能性儲存。各大品牌紛紛採用先進的阻隔性能、智慧的開合機制以及獨特的設計,以支撐更高的價格。例如,汰漬(Tide)於2024年推出的evo纖維包裝,採用可溶性六層層級構造而非塑膠,瞄準高階消費者。預計到2027年,中東地區美容相關支出將達到470億美元,也帶動了人們對居家護理包裝的類似期望。分配器和專用瓶蓋的製造商從中受益,例如,Silgan公司2024年第四季的銷售額飆升至6.394億美元。優質化推動了更小巧、更美觀的包裝形式,同時也增強了利潤率對樹脂成本波動的抵禦能力。這一趨勢在已開發市場和新興市場均通用,正在重塑居家護理包裝市場的競爭格局。
關於可回收單一材料包裝的循環經濟法規
監管機構正敦促生產商採用便於回收的設計。歐盟的《塑膠包裝和容器法規》(PPWR) 規定,到2030年,一次性塑膠飲料瓶必須100%可回收,且其中至少30%為再生材料,這促使生產商轉向使用單一材料。聯合利華的紙質清潔劑瓶清楚地展示了企業研發如何與這些緊迫的指標保持一致。目前,已有63個國家正式實施了生產者延伸責任制(EPR),將處置成本從市政當局轉移到製造商,並鼓勵採用可回收設計。單一材料薄膜領域的加工商將獲得定價權,而多層阻隔材料供應商將被迫升級設備,否則將面臨訂單減少的困境。從長遠來看,對合規性的投資預計將趨於穩定,從而支撐家居護理產品包裝市場的整體成長。
石化樹脂價格波動
聚乙烯 (PE) 和聚丙烯 (PP) 的價格波動對加工商的利潤率帶來壓力,並使定價策略變得更加複雜。由於停產和原物料價格飆升,PE 在 2024 年至 2025 年間多次上漲,漲幅達每磅 5 美分。熱帶風暴「艾伯特」造成的供應中斷導致 PET 價格上漲 1.1%。小規模加工商缺乏避險工具,被迫將成本轉嫁給消費者或降低居家照護包裝市場的利潤率。價格波動促使人們對更輕質的材料和替代基材產生興趣。能夠快速轉向生物基或再生材料的加工商可以減輕石化燃料價格波動的影響。
細分市場分析
到2025年,塑膠將佔家庭護理產品包裝市場佔有率的62.35%,再次鞏固其在需要具成本效益和阻隔性的應用領域的強勢地位。這一領域將繼續利用其成熟的供應鏈和多樣化的加工技術。然而,生質塑膠正以11.55%的複合年成長率成長,隨著監管機構和品牌商優先考慮可再生材料,生物塑膠在設計討論中扮演越來越重要的角色。
紙張和紙板因其高回收率和低碳足跡而重新受到關注,但其重量和易受潮性使其不太適合用於一般液體清潔劑。金屬在加壓氣霧劑產品中仍佔有一席之地,而玻璃由於在電子商務中易碎,其應用非常有限。生質塑膠的發展勢頭正推動對聚乳酸(PLA)和聚羥基脂肪酸酯(PHA)樹脂的投資,加工商正在測試滿足氧氣阻隔性要求的單一材料薄膜。隨著對再生材料含量的監管日益嚴格,消費後再生材料(PCR)與生物基原料的相容性混合物可以提高家庭護理包裝市場的供應穩定性和成本競爭力。
到2025年,瓶裝和硬質容器將佔家居護理包裝市場46.40%的佔有率,這反映了傳統生產線的現狀以及消費者對傳統形狀的熟悉程度。輕質高密度聚乙烯(HDPE)和聚對苯二甲酸寶特瓶因其優異的抗跌落衝擊性能和作為品牌廣告的功能而繼續佔據主導地位。然而,可重複填充的包裝袋和分配器系統正以9.42%的複合年成長率快速成長,透過循環利用實現材料節約和便利性,重新定義了價值提案。 Aptar公司用於皮膚化妝品的可回收無氣瓶和B-CAP公司的環保分配器蓋就是一個很好的例子,它們展示了創新如何能夠使即使是傳統的包裝形狀也煥然一新。
軟包裝袋能夠提高物流效率,減輕商品重量和體積,這對電商盈利至關重要。將可重複使用的分配器與輕巧的填充用軟包裝袋結合使用,可減少生命週期排放,並符合生產者延伸責任制(EPR)的收費系統。同時,金屬罐和條狀包裝在需要特定包裝形式的專業清潔產品中仍扮演著重要角色。對於所有類型的包裝,加工商都在包裝上添加帶有回收說明的QR碼,以方便消費者參與循環經濟體系,並提高合規指標,從而支持家居護理包裝市場的未來成長。
區域分析
預計到2025年,亞太地區將引領家居護理產品包裝市場,佔據38.45%的市場。這反映了中國、印度和東南亞地區快速的都市化、電子商務的蓬勃發展以及中產階級的壯大。中國即將實施的食品接觸用再生塑膠法規將為全部區域建立新的合規標準。日本的老齡化社會正在推動對易拉包裝和適合小型家庭使用的單次使用清潔劑的需求。預計到2024年,該地區對包裝器材的投資將超過180億美元,有助於加工商業務的擴張。
中東是成長最快的地區,預計到2031年將以7.41%的複合年成長率成長,這主要得益於波灣合作理事會(GCC)市場的優質化。該地區美容和個人護理行業的支出預計到2027年將達到470億美元,從而帶動對高階家居護理包裝的強勁需求。炎熱潮濕的氣候要求顏料具備更強的阻隔性能和紫外線穩定性,這也影響了供應商的規格要求。沙烏地阿拉伯在海灣合作理事會藥品銷售額中佔比高達34.6%,凸顯了衛生初級包裝領域的龐大商機。
北美和歐洲仍然至關重要,但它們面臨日益嚴格的監管挑戰。光是歐盟的《包裝廢棄物法規》(PPWR) 就促使全球品牌所有者增加了包裝重新設計的預算。同時,奧勒岡州和科羅拉多將於2025年7月前推出《生產者責任回收》(EPR) 計劃,擴大生產者自籌資金的回收模式。拉丁美洲也開始湧現新的機會。預計原物料成本上漲將推高2025年紙質包裝價格,顯示市場已趨於成熟(fastmarkets.com)。整體而言,區域性法規和消費者行為共同作用,使居家照護包裝市場呈現出微妙的成長態勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 品牌主導推動了優質化進程和 SKU 數量的增加。
- 可回收單一材料包裝的循環經濟要求
- 電子商務的快速發展正在加速對耐損性能的需求。
- 亞洲都市區家庭喜歡方便的單份包裝。
- 物聯網賦能的智慧分配器與補充裝生態系統
- 市場限制因素
- 石化樹脂價格波動
- 歐洲的生產者延伸責任制(EPR)費用
- 供不應求,無法滿足品牌承諾
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 材料
- 塑膠
- 紙張和紙板
- 金屬
- 玻璃
- 生質塑膠
- 按包裝類型
- 瓶子和硬質容器
- 小袋和袋子
- 瓦楞紙箱和紙盒
- 金屬罐和氣霧劑
- 填充用包裝袋和分發系統
- 條狀包裝和小袋
- 產品類型
- 衣物洗護
- 洗碗
- 表面和廁所清潔劑
- 空氣清淨
- 殺蟲劑
- 研磨劑和特殊清潔劑
- 按外形規格
- 液體
- 粉末
- 膠囊/片劑
- 凝膠
- 噴霧/泡沫
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Ball Corporation
- RPC Group(Berry Global)
- Winpak Ltd
- Aptar Group Inc.
- Sonoco Products Company
- Silgan Holdings
- Constantia Flexibles GmbH
- DS Smith plc
- Can-Pack SA
- ProAmpac LLC
- Berry Global Group
- Mondi plc
- Huhtamaki Oyj
- Smurfit Kappa Group
- Sealed Air Corp.
- WestRock Company
- Albea Group
- Gerresheimer AG
- Tetra Pak
第7章 市場機會與未來展望
According to Mordor Intelligence, the home care packaging market size in 2026 is estimated at USD 39.18 billion, growing from 2025 value of USD 37.3 billion with 2031 projections showing USD 50.07 billion, growing at 5.03% CAGR over 2026-2031.
This report Segments the Industry Into Material (Plastic, Paper and More), Packaging Type (Bottles and Rigid Containers, Pouches and Bags and More), Product Category (Dishwashing, Insecticides and More), Form Factor(Liquids, Powders and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Home Care Packaging Market Trends and Insights
Rising Premiumisation and Brand-Led SKU Proliferation
Demand for upscale cleaning products drives packaging innovation beyond functional containment. Brands deploy advanced barriers, smart closures, and distinctive aesthetics to justify higher price points. Tide evo fibre tiles, launched in 2024, replace plastic with a dissolvable six-layer fibre structure and target premium shoppers. Middle East beauty spending, set to hit USD 47 billion by 2027, fuels similar expectations for home-care packs. Manufacturers of dispensing and specialty closures benefit, as evidenced by Silgan's Q4 2024 sales jump to USD 639.4 million. Premiumisation simultaneously promotes smaller, design-rich formats and boosts margin resilience against resin cost swings. The trend cuts across developed and emerging markets, reshaping shelf competition within the home care packaging market.
Circular-Economy Mandates for Recyclable Mono-Material Packs
Regulators push producers toward designs that enable straightforward recycling. The EU's PPWR stipulates 100% recyclability by 2030 and 30% recycled content for single-use plastic beverage bottles, compelling shifts to mono-material structures. Unilever's paper-based detergent bottle underscores how corporate R&D aligns with looming quotas. Sixty-three countries now run formal EPR schemes, moving disposal costs from municipalities to producers and rewarding design-for-recycling approaches. Converters positioned in mono-material films gain pricing power, whereas multi-layer barrier suppliers must retool or face declining order books. Over the long term, compliance investments are expected to stabilise and support the broader home care packaging market trajectory.
Petro-chemical Resin Price Volatility
Fluctuating polyethylene and polypropylene prices compress converter margins and complicate pricing strategy. PE registered several 5 ¢/lb hikes in 2024 - 2025 due to outages and feedstock spikes. PET saw a 1.1% jump after Tropical Storm Alberto disrupted supply. Smaller converters lack hedging tools, forcing cost-pass through or margin erosion in the home care packaging market. Volatility accelerates interest in lightweighting and alternative substrates. Converters able to shift to bio-based or recycled inputs faster can cushion against fossil-fuel price swings.
Other drivers and restraints analyzed in the detailed report include:
- E-commerce Boom Accelerating Demand for Shatter-Proof Formats
- Urban Asian Households Favouring Single-Dose Convenience Packs
- Extended-Producer-Responsibility Fees in Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics captured 62.35% of the home care packaging market share in 2025, underlining their entrenched role in cost-effective, barrier-rich applications. The segment continues to leverage mature supply chains and versatile processing techniques. However, bioplastics, propelled by a 11.55% CAGR, increasingly command design conversations as regulators and brands prioritise renewable feedstocks.
Paper and paperboard regain relevance through high recycling rates and lower carbon footprints, yet weight and moisture sensitivity keep them from mainstream liquid detergents. Metal retains niche importance in pressurised aerosols, and glass sees marginal use due to breakage risks in e-commerce. Bioplastics' momentum spurs investment in PLA and PHA resins, with converters trialling mono-material films that still meet oxygen-barrier demands. As recycled-content mandates tighten, compatibilised blends of PCR and bio-based inputs can bolster supply stability and cost competitiveness for the home care packaging market.
Bottles and rigid containers accounted for 46.40% of the home care packaging market size in 2025, reflecting legacy production lines and consumer familiarity with traditional formats. Lightweight HDPE and PET bottles remain prevalent thanks to excellent drop-impact resistance and brand-billboard capability. Yet refill pouches and dispensing systems, expanding at a 9.42% CAGR, are redefining value propositions through material savings and circular-loop convenience. Aptar's recyclable airless bottle for dermocosmetics and B-CAP's eco dosing cap demonstrate how innovation modernises even established formats.
Pouches deliver logistics efficiencies, shaving freight weight and cubic volume, crucial for e-commerce profitability. Reusable dispensers coupled with lightweight refill sachets reduce life-cycle emissions, resonating with EPR fee structures. Meanwhile, metal cans and stick packs maintain roles in specialty cleaners requiring specific delivery modes. Across all types, converters integrate QR codes for recycling instructions, aiming to ease consumer participation in circular schemes and boost compliance metrics that underpin the future growth of the home care packaging market.
Complete Report Scope:
- By Material
- Plastics
- Paper and Paperboard
- Metal
- Glass
- Bioplastics
- By Packaging Type
- Bottles and Rigid Containers
- Pouches and Bags
- Cartons and Corrugated Boxes
- Metal Cans and Aerosols
- Refill Pouches and Dispensing Systems
- Stick Packs and Sachets
- By Product Category
- Laundry Care
- Dishwashing
- Surface and Toilet Cleaners
- Air Care
- Insecticides
- Polishes and Specialty Cleaners
- By Form Factor
- Liquids
- Powders
- Capsules/Tabs
- Gels
- Sprays/Foams
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific dominated with 38.45% home care packaging market share in 2025, reflecting rapid urbanisation, e-commerce growth, and middle-class expansion in China, India, and Southeast Asia. China's forthcoming rules for recycled food-contact plastics will set new compliance benchmarks regionally. Japan's ageing society drives demand for easy-open packs and single-dose detergents suited to smaller households. Investment in regional packaging machinery is forecast to surpass USD 18 billion by 2024, underpinning scale-up for converters.
The Middle East is the fastest-growing territory, with a 7.41% CAGR through 2031, supported by premiumisation in Gulf Cooperation Council markets. Regional beauty and personal-care outlays-from which spillover demand for upscale home-care packs emerges-will hit USD 47 billion by 2027. Hot climates necessitate barrier enhancements and UV-stable pigments, shaping supplier specifications. Saudi Arabia's 34.6% share of GCC pharmaceutical sales highlights parallel opportunities for hygienic primary packs.
North America and Europe remain pivotal yet face tightening regulatory nets. The EU PPWR alone drives redesign budgets for global brand owners. Meanwhile, Oregon and Colorado introduce EPR schemes by July 2025, broadening producer-funded recycling models. Latin America shows emerging promise: higher raw-material costs push paper-pack prices up in 2025, signalling market maturation fastmarkets.com. Collectively, region-specific rules and consumer behaviours maintain nuanced growth paths across the home care packaging market.
- Amcor plc
- Ball Corporation
- RPC Group (Berry Global)
- Winpak Ltd
- Aptar Group Inc.
- Sonoco Products Company
- Silgan Holdings
- Constantia Flexibles GmbH
- DS Smith plc
- Can-Pack SA
- ProAmpac LLC
- Berry Global Group
- Mondi plc
- Huhtamaki Oyj
- Smurfit Kappa Group
- Sealed Air Corp.
- WestRock Company
- Albea Group
- Gerresheimer AG
- Tetra Pak
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising premiumisation and brand-led SKU proliferation
- 4.2.2 Circular-economy mandates for recyclable mono-material packs
- 4.2.3 E-commerce boom accelerating demand for shatter-proof formats
- 4.2.4 Urban Asian households favouring single-dose convenience packs
- 4.2.5 IoT-enabled smart dispensers and refill ecosystems
- 4.3 Market Restraints
- 4.3.1 Petro-chemical resin price volatility
- 4.3.2 Extended-producer-responsibility (EPR) fees in Europe
- 4.3.3 Scarcity of food-grade PCR resin for brand pledges
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Material
- 5.1.1 Plastics
- 5.1.2 Paper and Paperboard
- 5.1.3 Metal
- 5.1.4 Glass
- 5.1.5 Bioplastics
- 5.2 By Packaging Type
- 5.2.1 Bottles and Rigid Containers
- 5.2.2 Pouches and Bags
- 5.2.3 Cartons and Corrugated Boxes
- 5.2.4 Metal Cans and Aerosols
- 5.2.5 Refill Pouches and Dispensing Systems
- 5.2.6 Stick Packs and Sachets
- 5.3 By Product Category
- 5.3.1 Laundry Care
- 5.3.2 Dishwashing
- 5.3.3 Surface and Toilet Cleaners
- 5.3.4 Air Care
- 5.3.5 Insecticides
- 5.3.6 Polishes and Specialty Cleaners
- 5.4 By Form Factor
- 5.4.1 Liquids
- 5.4.2 Powders
- 5.4.3 Capsules/Tabs
- 5.4.4 Gels
- 5.4.5 Sprays/Foams
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Israel
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Turkey
- 5.5.5.5 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Ball Corporation
- 6.4.3 RPC Group (Berry Global)
- 6.4.4 Winpak Ltd
- 6.4.5 Aptar Group Inc.
- 6.4.6 Sonoco Products Company
- 6.4.7 Silgan Holdings
- 6.4.8 Constantia Flexibles GmbH
- 6.4.9 DS Smith plc
- 6.4.10 Can-Pack SA
- 6.4.11 ProAmpac LLC
- 6.4.12 Berry Global Group
- 6.4.13 Mondi plc
- 6.4.14 Huhtamaki Oyj
- 6.4.15 Smurfit Kappa Group
- 6.4.16 Sealed Air Corp.
- 6.4.17 WestRock Company
- 6.4.18 Albea Group
- 6.4.19 Gerresheimer AG
- 6.4.20 Tetra Pak
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 歐洲消費品包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 消費品包裝市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。快速消費品包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 居家照護套餐市場-2026-2032年全球市場預測
 消費性包裝市場預測至2034年-按材料、包裝類型、產品類型、永續性類型、功能、應用和地區分類的全球分析居家護理產品包裝市場規模、佔有率、成長率及全球市場分析:按類型、應用和地區分類,並提供2026-2034年的洞察與預測
 居家照護包裝市場規模、佔有率、趨勢和預測:按產品類型、材料、包裝形式和地區分類,2026-2034年快速消費品包裝市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年日常消費品包裝市場規模、佔有率、趨勢及預測(按包裝類型、材料、最終用途行業和地區分類,2026-2034年)
 2026年全球居家護理產品包裝市場報告