


 |
市場調查報告書
商品編碼
2121261
歐洲數位鑑識:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Digital Forensics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
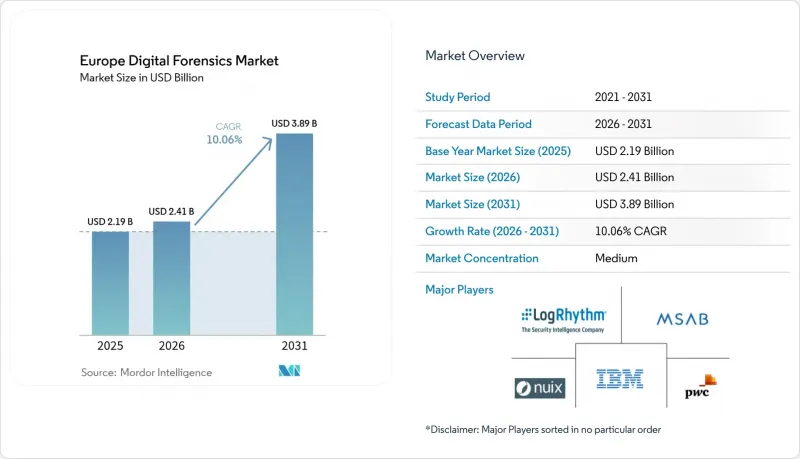
據 Mordor Intelligence 稱,2025 年歐洲數位取證市值為 21.9 億美元,預計到 2031 年將從 2026 年的 24.1 億美元成長至 38.9 億美元,預測期(2026-2031 年)的複合年成長率為 10.06%。
本報告按組件(硬體、軟體、服務)、類型(電腦、行動裝置、網路、雲端、其他)、工具(資料收集和儲存、資料恢復、其他)、企業規模(大型企業、中小企業)、最終用戶產業(政府和執法機關、銀行、金融服務和保險 (BFSI)、IT 和電信、醫療保健、其他)以及地區進行細分。市場預測以美元 (USD) 為單位。
歐洲數位鑑識市場趨勢與洞察
透過遵守歐盟的 DORA 和 NIS2 標準,加速法醫回應系統的發展。
自2025年1月17日起,歐盟境內的金融機構必須證明其持續監控、事件記錄和第三方監督能力,這使得取證能力從一項可選附加功能轉變為一項監管標準。隨著監管機構開始審核資訊通訊技術(ICT)提供者的註冊訊息,各銀行正在部署公司範圍內的證據庫,這些證據庫可直接連接到其安全資訊和事件管理(SIEM)系統,並自動發送違規通知。與NIS2的協調將類似的義務擴展到能源公司和數位服務供應商,從而將歐洲數位鑑識市場擴展到核心金融領域之外。預算重新分配有利於提供監管鏈檢驗功能的多租戶雲端平台,從而改善軟體供應商的持續收入來源。
加密通訊應用程式的普及推高了對行動取證的需求。
由於 iOS 18 預設啟用端對端加密和自動刪除訊息功能,負責人不得不採用結合邏輯擷取、備份分析和人工智慧模式匹配的進階繞過技術。研究表明,借助高級工具,可以透過通知痕跡恢復 83.33% 的已刪除 WhatsApp訊息。隨著技術複雜性的增加,專業服務變得至關重要,推動了服務業的兩位數成長。
GDPR對證據蒐集的隱私限制
目前,大多數大規模取證案件都需要進行隱私影響評估,這導致專案週期延長,而小規模的實驗室則被迫推遲複雜的跨境操作。由於各國對監管規定的解讀各不相同,在一個國家合法收集的證據在另一個國家可能受到質疑,從而加重了法律審查的負擔。選擇性收集軟體的投資正在不斷增加,這類軟體能夠對個人識別資訊進行哈希處理和標記,而不是提取整個磁碟鏡像,從而推進符合資料最小化原則的實踐。
細分市場分析
預計到2025年,軟體仍將佔據歐洲數位鑑識市場最大佔有率,達到44.62%。這主要得益於可擴展的訂閱定價模式以及涵蓋行動端、雲端和SaaS平台的持續功能更新。儘管隨著資料擷取工作轉向虛擬機,硬體支出成長放緩,但用於提取線索的專用加密狗和高速寫入保護器在重大刑事調查中仍然至關重要。整體而言,以服務為中心的營運模式能夠幫助供應商在預算不斷成長的同時,保障客戶免受技能短缺的影響。
2026年至2031年間,服務業的複合年成長率最高,達11.01%。這是因為企業將複雜的證據收集工作外包給營運遠距實驗室和提供按需分析的專業團隊。大型金融機構正在簽訂多年期的取證管理協議,其中包括在DORA規定的彈性測試週期內,安排顧問駐團辦公室。供應商透過提供可立即提交法庭的文檔工作流程以及與電子取證套件的API整合來脫穎而出,從而減少向法律負責人移交證據時的摩擦。
到2025年,行動平台將佔歐洲數位鑑識市場34.58%的佔有率,反映出智慧型手機在個人和商業工作流程中的廣泛應用。負責人正致力於整合加密聊天記錄、感測器融合資料和證據時間線,以重建使用者行為管道。穿戴式裝置則為取證增添了新的維度,進一步鞏固了行動電話分析作為一項基礎分析領域的地位。
由於多租戶SaaS的普及,關鍵證據轉移到了雲端,雲端取證正以11.23%的複合年成長率成長。服務提供者現在提供簡介工具,可以凍結虛擬執行個體並自動進行管轄權映射,以確保法律效力。雖然電腦取證的佔有率正在下降,但終端痕跡仍然是內部威脅和詐欺調查的基礎。新興的車輛和物聯網相關證據類型正在推動整合平台的發展,這些平台可以將來自ECU、智慧感測器和中央雲的日誌資料整合到單一案件文件中。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 透過遵守歐盟的 DORA 和 NIS2 標準,加速法醫回應系統的發展。
- 由於加密通訊應用的廣泛普及,對行動取證的需求日益成長。
- 德國、奧地利和瑞士以及比荷盧經濟聯盟國家勒索軟體事件的激增,使得事件回應取證的重要性日益凸顯。
- 聯網汽車的成長為汽車/物聯網取證服務帶來了新的需求。
- 5G 的部署將促進對人工智慧驅動的網路取證的投資。
- 市場限制因素
- GDPR 對證據蒐集的隱私限制
- 端對端加密導致調查時間和成本增加。
- 由於警務採購預算細分,導致實施延誤
- 歐洲ISO/IEC 17025認證檢測實驗室短缺
- 價值供應鏈分析
- 監理展望
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 硬體
- 軟體
- 服務
- 按類型
- 電腦取證
- 行動裝置取證
- 網路取證
- 雲取證
- 資料庫取證
- 物聯網和嵌入式設備的取證
- 工具
- 數據採集和存儲
- 資料恢復與重建
- 法醫數據分析
- 審核和報告撰寫
- 取證解密與密碼破解
- 按公司規模
- 大公司
- 小型企業
- 按最終用戶行業分類
- 政府和執法機關
- BFSI
- 資訊科技/通訊
- 衛生保健
- 零售與電子商務
- 能源與公共產業
- 製造業
- 運輸/物流
- 國防/航太
- 教育
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 北歐的
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- MSAB AB
- LogRhythm Inc.
- IBM Corporation
- PricewaterhouseCoopers LLP
- Nuix Ltd.
- Cellebrite DI Ltd.
- Magnet Forensics Inc.
- OpenText Corp.(Guidance Software)
- FireEye Inc.(Trellix)
- Envista Forensics
- Cellebrite(Digital Intelligence)
- ADF Solutions LLC
- AccessData(Exterro)
- Oxygen Forensics Inc.
- Paraben Corp.
- BAE Systems Applied Intelligence
- Atos SE(Evidian)
- Sytech Digital Forensics
- CCL Solutions Group Ltd.
- Evidence Talks Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe digital forensics market size was valued at USD 2.19 billion in 2025 and estimated to grow from USD 2.41 billion in 2026 to reach USD 3.89 billion by 2031, at a CAGR of 10.06% during the forecast period (2026-2031).
This report is Segmented by Component (Hardware, Software, Services), Type (Computer, Mobile Device, Network, Cloud, and More), Tool (Data Acquisition and Prevention, Data Recovery, and More), Enterprise Size (Large Enterprises, Smes), End-User (Government, BFSI, IT, Healthcare, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe Digital Forensics Market Trends and Insights
EU DORA & NIS2 Compliance Accelerating Forensic Readiness
Since 17 January 2025, financial entities across the bloc must prove continuous monitoring, incident logging, and third-party oversight, turning forensic readiness from an optional add-on into a regulatory baseline. Supervisors now audit registers of ICT providers, so banks procure enterprise-wide evidence repositories that plug directly into SIEM stacks and automate breach notification. Harmonisation with NIS2 extends similar obligations to energy utilities and digital service providers, widening the European digital forensics market beyond core finance. Budget reallocations favour multi-tenant cloud platforms offering chain-of-custody validation, which lifts recurring revenue for software vendors.
Proliferation of Encrypted Messaging Apps Boosting Mobile Forensics Demand
End-to-end encryption in iOS 18 and disappearing-message defaults push investigators toward advanced bypass techniques that combine logical extraction, backup parsing, and AI pattern matching. Research shows 83.33% of deleted WhatsApp messages remain recoverable through notification artefacts when sophisticated tooling is used.Greater technical complexity makes professional services indispensable, fuelling the services segment's double-digit growth trajectory.
GDPR Privacy Limits on Evidence Acquisition
Privacy Impact Assessments now accompany most large-scale forensic cases, lengthening engagement cycles and pushing smaller labs to defer complex cross-border work. National differences in supervisory interpretation mean evidence gathered legally in one state may face challenge in another, adding legal-review overhead. Investment is shifting toward selective-collection software that can hash and flag personally identifiable data instead of extracting entire disk images, aligning practice with data-minimisation rules.
Other drivers and restraints analyzed in the detailed report include:
- Spike in Ransomware Incidents Across DACH & Benelux Elevating Incident-Response Forensics
- Connected-Vehicle Growth Creating New Vehicle/IoT Forensics Workloads
- End-to-End Encryption Increasing Investigation Time & Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software retains the dominant 44.62% slice of the European digital forensics market in 2025, thanks to scaled subscription pricing and continuous feature updates covering mobile, cloud, and SaaS artefact parsing. Hardware spend slows as acquisition tasks shift into virtual machines, yet proprietary dongles for chip-off extraction and high-speed write-blockers stay necessary for severe criminal investigations. Overall, a service-centric operating model positions providers to capture expansion budgets while protecting customers from skills shortages.
Services recorded the quickest 11.01% CAGR between 2026-2031 as corporates outsource complex evidence collection to specialised teams that operate remote labs and on-demand analytics. Large financial institutions sign multi-year managed forensics contracts that embed consultants during resilience-testing cycles mandated by DORA.Vendors differentiate through court-ready documentation workflows and API integrations with e-discovery suites, reducing hand-off friction for legal counsel
Mobile platforms captured 34.58% of the Europe digital forensics market size in 2025, reflecting smartphone ubiquity across personal and enterprise workflows. Investigators focus on encrypted chat artefacts, sensor fusion data, and artefact timeline stitching to recreate user journeys. Companion wearables add another evidence layer, further cementing handset analysis as a foundational discipline.
Cloud forensics grows at 11.23% CAGR as multi-tenant SaaS moves key evidence off-premise. Providers now supply snapshot tooling that freezes virtual instances and automates jurisdiction mapping to maintain legal validity. Computer forensics share declines, though endpoint artefacts still anchor insider-threat and fraud probes. Emergent vehicle and IoT evidence types spur integrated platforms able to stitch log data from ECUs, smart sensors, and central clouds in a single case file.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Type
- Computer Forensics
- Mobile Device Forensics
- Network Forensics
- Cloud Forensics
- Database Forensics
- IoT and Embedded Device Forensics
- By Tool
- Data Acquisition and Preservation
- Data Recovery and Reconstruction
- Forensic Data Analysis
- Review and Reporting
- Forensic Decryption and Password Cracking
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By End-user Industry
- Government and Law Enforcement Agencies
- BFSI
- IT and Telecom
- Healthcare
- Retail and E-commerce
- Energy and Utilities
- Manufacturing
- Transportation and Logistics
- Defense and Aerospace
- Education
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
List of Companies Covered in this Report:
- MSAB AB
- LogRhythm Inc.
- IBM Corporation
- PricewaterhouseCoopers LLP
- Nuix Ltd.
- Cellebrite DI Ltd.
- Magnet Forensics Inc.
- OpenText Corp. (Guidance Software)
- FireEye Inc. (Trellix)
- Envista Forensics
- Cellebrite (Digital Intelligence)
- ADF Solutions LLC
- AccessData (Exterro)
- Oxygen Forensics Inc.
- Paraben Corp.
- BAE Systems Applied Intelligence
- Atos SE (Evidian)
- Sytech Digital Forensics
- CCL Solutions Group Ltd.
- Evidence Talks Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU DORA and NIS2 Compliance Accelerating Forensic Readiness
- 4.2.2 Proliferation of Encrypted Messaging Apps Boosting Mobile Forensics Demand
- 4.2.3 Spike in Ransomware Incidents Across DACH and Benelux Elevating Incident-Response Forensics
- 4.2.4 Connected-Vehicle Growth Creating New Vehicle/IoT Forensics Workloads
- 4.2.5 5G Roll-out Driving AI-based Network Forensics Investments
- 4.3 Market Restraints
- 4.3.1 GDPR Privacy Limits on Evidence Acquisition
- 4.3.2 End-to-End Encryption Increasing Investigation Time and Cost
- 4.3.3 Fragmented Police Procurement Budgets Slowing Adoption
- 4.3.4 Shortage of ISO/IEC 17025-Accredited Labs in Europe
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Type
- 5.2.1 Computer Forensics
- 5.2.2 Mobile Device Forensics
- 5.2.3 Network Forensics
- 5.2.4 Cloud Forensics
- 5.2.5 Database Forensics
- 5.2.6 IoT and Embedded Device Forensics
- 5.3 By Tool
- 5.3.1 Data Acquisition and Preservation
- 5.3.2 Data Recovery and Reconstruction
- 5.3.3 Forensic Data Analysis
- 5.3.4 Review and Reporting
- 5.3.5 Forensic Decryption and Password Cracking
- 5.4 By Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By End-user Industry
- 5.5.1 Government and Law Enforcement Agencies
- 5.5.2 BFSI
- 5.5.3 IT and Telecom
- 5.5.4 Healthcare
- 5.5.5 Retail and E-commerce
- 5.5.6 Energy and Utilities
- 5.5.7 Manufacturing
- 5.5.8 Transportation and Logistics
- 5.5.9 Defense and Aerospace
- 5.5.10 Education
- 5.6 By Country
- 5.6.1 United Kingdom
- 5.6.2 Germany
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Nordics
- 5.6.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 MSAB AB
- 6.4.2 LogRhythm Inc.
- 6.4.3 IBM Corporation
- 6.4.4 PricewaterhouseCoopers LLP
- 6.4.5 Nuix Ltd.
- 6.4.6 Cellebrite DI Ltd.
- 6.4.7 Magnet Forensics Inc.
- 6.4.8 OpenText Corp. (Guidance Software)
- 6.4.9 FireEye Inc. (Trellix)
- 6.4.10 Envista Forensics
- 6.4.11 Cellebrite (Digital Intelligence)
- 6.4.12 ADF Solutions LLC
- 6.4.13 AccessData (Exterro)
- 6.4.14 Oxygen Forensics Inc.
- 6.4.15 Paraben Corp.
- 6.4.16 BAE Systems Applied Intelligence
- 6.4.17 Atos SE (Evidian)
- 6.4.18 Sytech Digital Forensics
- 6.4.19 CCL Solutions Group Ltd.
- 6.4.20 Evidence Talks Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 數位調查解決方案市場:全球市場預測,2026-2032年
 數位鑑識:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026-2030年全球數位鑑識市場品牌活化服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 數位取證市場報告:按組件、類型、工具、最終用戶和地區分類(2026-2034 年)
 數位取證市場:按取證類型、組件、工具、產業和地區分類
 數位取證工具市場預測至2034年:按組件、取證類型、部署模式、組織規模、應用、最終用戶和地區分類的全球分析
 數位取證市場分析及預測(至2035年):按類型、產品類型、服務、技術、組件、應用、設備、流程、部署模式和最終用戶分類數位取證市場:2026-2032年全球市場預測(按解決方案、取證類型、應用、部署模式和最終用戶產業分類)
 2026年全球數位鑑識市場報告